
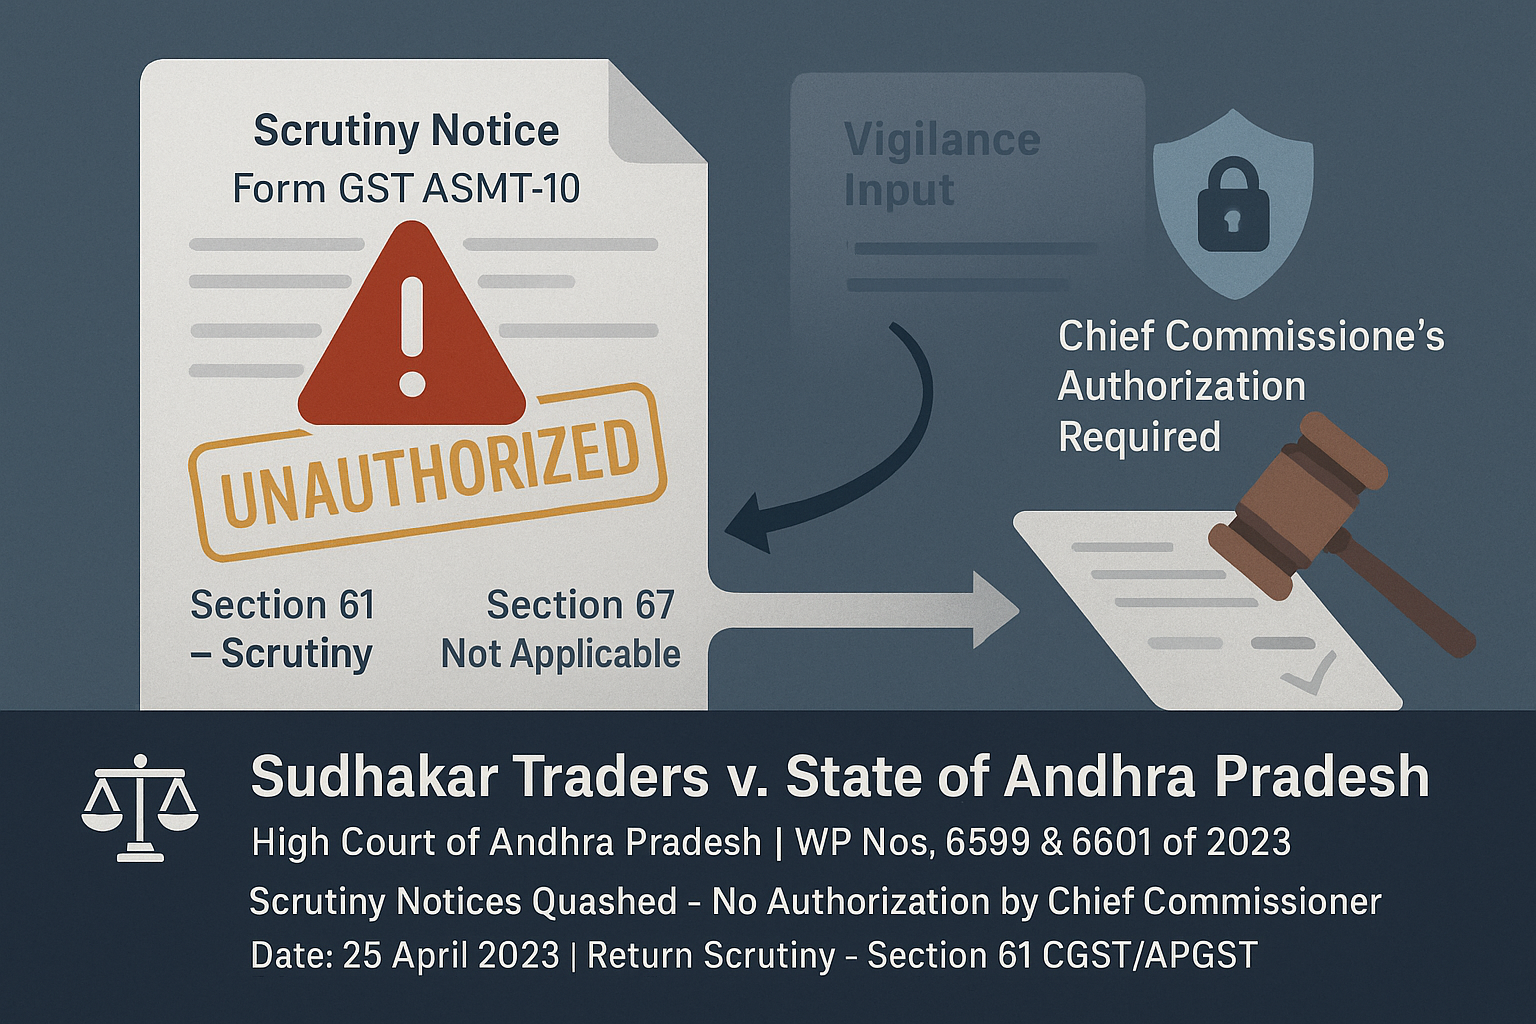
Case Title: Sudhakar Traders vs. State of Andhra Pradesh
Court: High Court of Andhra Pradesh
Petition No.: W.P. Nos. 6599 and 6601 of 2023
Category of Dispute: Scrutiny of Returns – Validity of Notices
Date of Judgement: April 25, 2023
Relevant Sections:
Section 61, 67, 72 of the APGST Act, 2017
Rule 99 of the APGST Rules, 2017
Facts of the Case [Paras 1–3]
- The petitioner, Sudhakar Traders, a registered dealer under the APGST Act, supplied iron and steel and filed returns for the periods April 2019–March 2020 and April 2020–March 2021.
- The 3rd respondent (Deputy Commissioner) issued notices in Form GST ASMT-10 on 28.02.2023 based on an alert note from the 2nd respondent (Regional Vigilance & Enforcement Officer), alleging suppression of turnover [Para 2].
- Petitioner challenged these notices, contending lack of authority of the 2nd respondent to conduct inspections and questioned the validity of the notices for want of proper authorization under GST law [Para 4].
Questions in Consideration
- Whether the 2nd respondent had statutory authority to inspect the petitioner’s premises and send an alert note to the 3rd respondent? [Para 7(1)]
- Whether the impugned notices issued under Rule 99 read with Section 61 are unsustainable for want of authorization under Section 67 of the APGST Act? [Para 7(2)]
Observations of the Court
- On Role of Vigilance Department:
The Court held that the 2nd respondent’s inspection was valid under G.O.Ms.No.504 dated 25.11.1997. The V&E Department was empowered to prevent revenue leakages and assist tax departments. Sharing the alert note was within their lawful authority [Paras 9–11]. - On Use of Section 67:
The Court agreed with the Revenue that the impugned notices were not issued under Section 67 (inspection/search/seizure) but under Rule 99 read with Section 61 (scrutiny of returns), which does not require action under Section 67 [Para 12]. - On Authorization by Proper Officer:
However, the Court found that as per Section 2(91) of the Act, a “Proper Officer” includes only those officers assigned such functions by the Chief Commissioner. The Deputy Commissioner (3rd respondent) had not shown any such authorization. Therefore, the notices were vitiated due to lack of jurisdiction [Para 13].
Judgement of the Court [Para 14]
The writ petitions were allowed. The impugned notices dated 28.02.2023 were set aside for want of authorization from the Chief Commissioner. However, liberty was granted to issue fresh notices under Rule 99 read with Section 61, duly authorized by the Chief Commissioner, and accompanied by relevant documents referred to in the alert note.
Between Fine Lines
- The Vigilance & Enforcement Department is empowered to assist tax authorities and can conduct inspections for preventing tax evasion.
- Notices for scrutiny of returns under Rule 99 r/w Section 61 do not require Section 67 authorization.
- However, only a “Proper Officer” (authorized by the Chief Commissioner) can issue such scrutiny notices.
- Lack of authorization renders the notices illegal.
- The department can reinitiate proceedings with proper delegation and procedure.
Summary of Referred Cases
| Name | Citation | Summary | Verdict/Use in Case |
| Prakashsinh Hathisinh Udavat v. State of Gujarat | [2019] 112 taxmann.com 124 / 31 GSTL 583 (Guj.) | Assistant Commissioner seized goods without proper authorization under Section 67(2). | Cited by petitioner, but held inapplicable as seizure was not in issue. |
Takeaway:
“Authorization First: Scrutiny Notices Without Proper Delegation Invalidated”



