
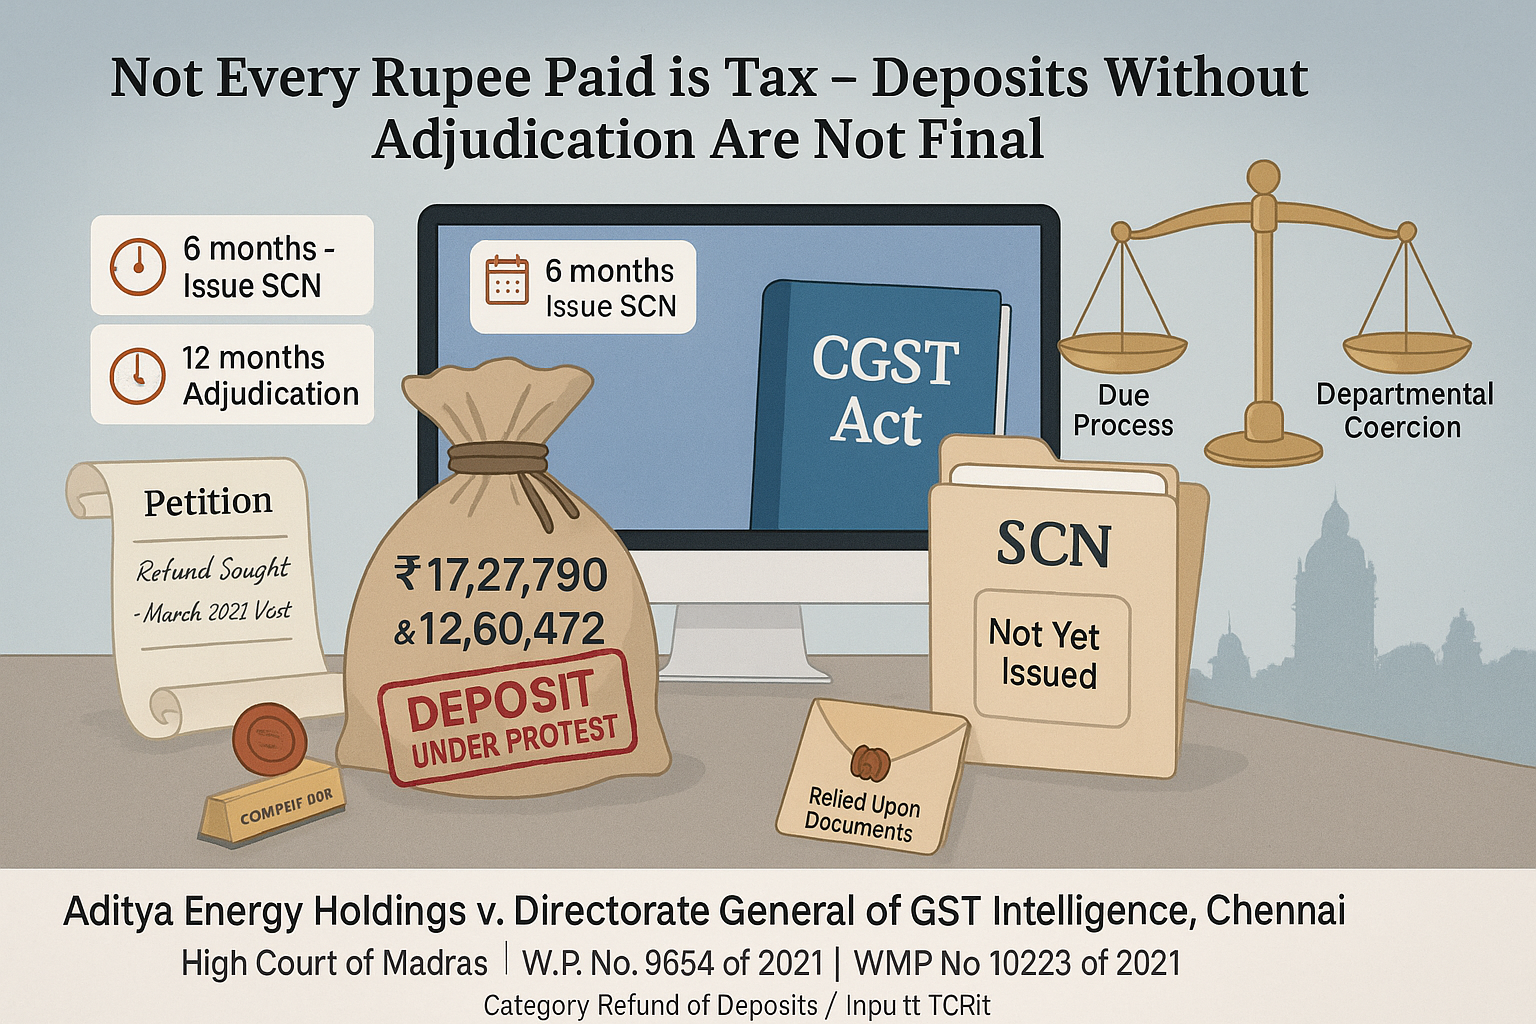
Case Title: Aditya Energy Holdings v. Directorate General of GST Intelligence, Chennai
Court: High Court of Madras
Petition No.: W.P. No. 9654 of 2021, WMP No. 10223 of 2021
Category of Dispute: Refund of Deposits / Input Tax Credit
Date of Judgment: 10 December 2021
Relevant Sections: Section 73 and 74 of the CGST Act, 2017
Facts of the Case
[Para 1–2, 5]
- The petitioner, Aditya Energy Holdings, sought a writ of mandamus for the refund of ₹17,27,790 and ₹12,60,472 paid during a visit by GST intelligence officers investigating alleged wrongful availment of Input Tax Credit.
- The petitioner claimed the payments were made under coercion during the search and seizure operation conducted in March 2021.
- A representation was also sent by the petitioner on 01.04.2021 regarding the matter.
Questions in Consideration
[Para 1, 2, 6]
- Whether the payments made by the petitioner during investigation are refundable as they were allegedly made under coercion?
- Whether such payments are to be treated as voluntary tax payments or mere deposits pending adjudication under Section 73/74 of the CGST Act?
Observation of Court
[Para 5–7]
- The Court noted that the amounts paid by the petitioner during investigation were only “deposits” and not final payments, pending adjudication under Sections 73 or 74 of the CGST Act.
- It was observed that the seizure and summoning took place on the same date, suggesting that the investigation was ongoing.
- The Court instructed the respondent to treat the payments as made “under protest”.
- The respondent must issue a show cause notice within six months, enclosing all Relied Upon Documents and reasons for demand/appropriation of said amounts.
- Respondents were also directed to return copies and original documents that are not required for investigation.
Judgment of the Court
[Para 6–8]
- The Writ Petition was disposed of with a direction that the amounts paid shall be treated as under protest.
- The investigation must be completed and a show cause notice issued within six months, and final adjudication must occur within twelve months.
- If no demand is established in the show cause proceedings, the amount collected must be refunded.
- The petitioner is obligated to cooperate and file a reply within 30 days of the show cause notice.
Between Fine Lines
- The court emphasized that payments made during an investigation without formal adjudication do not amount to tax payments.
- Such payments are treated as deposits and subject to refund if no liability is determined under Section 73/74.
- Authorities must ensure due process with issuance of proper show cause notices.
- Taxpayers must be given an opportunity to contest the demand before appropriation of deposited amounts.
- Procedural compliance and documentation transparency (Relied Upon Documents) are vital for legal sustainability.
Summary of Referred Cases
| Name | Citation | Summary | Verdict |
| No specific case cited in judgment | – | – | – |
Takeaway:
“Not Every Rupee Paid is Tax – Deposits Without Adjudication Are Not Final.”



