
Case Title: BCC Developers and Promoters (P.) Ltd. v. Principal Commissioner of Central Goods and Services Tax
Court: High Court of Delhi
Petition No.: W.P. (C) No. 13075 of 2023
Category of Dispute: Refund – Credit lying in non-migrated GSTIN
Date of Judgement: 01 March 2024
Relevant Sections: Not specifically mentioned; relates to transitional provisions and administrative functioning of GST portal
Facts of the Case [¶1–7]:
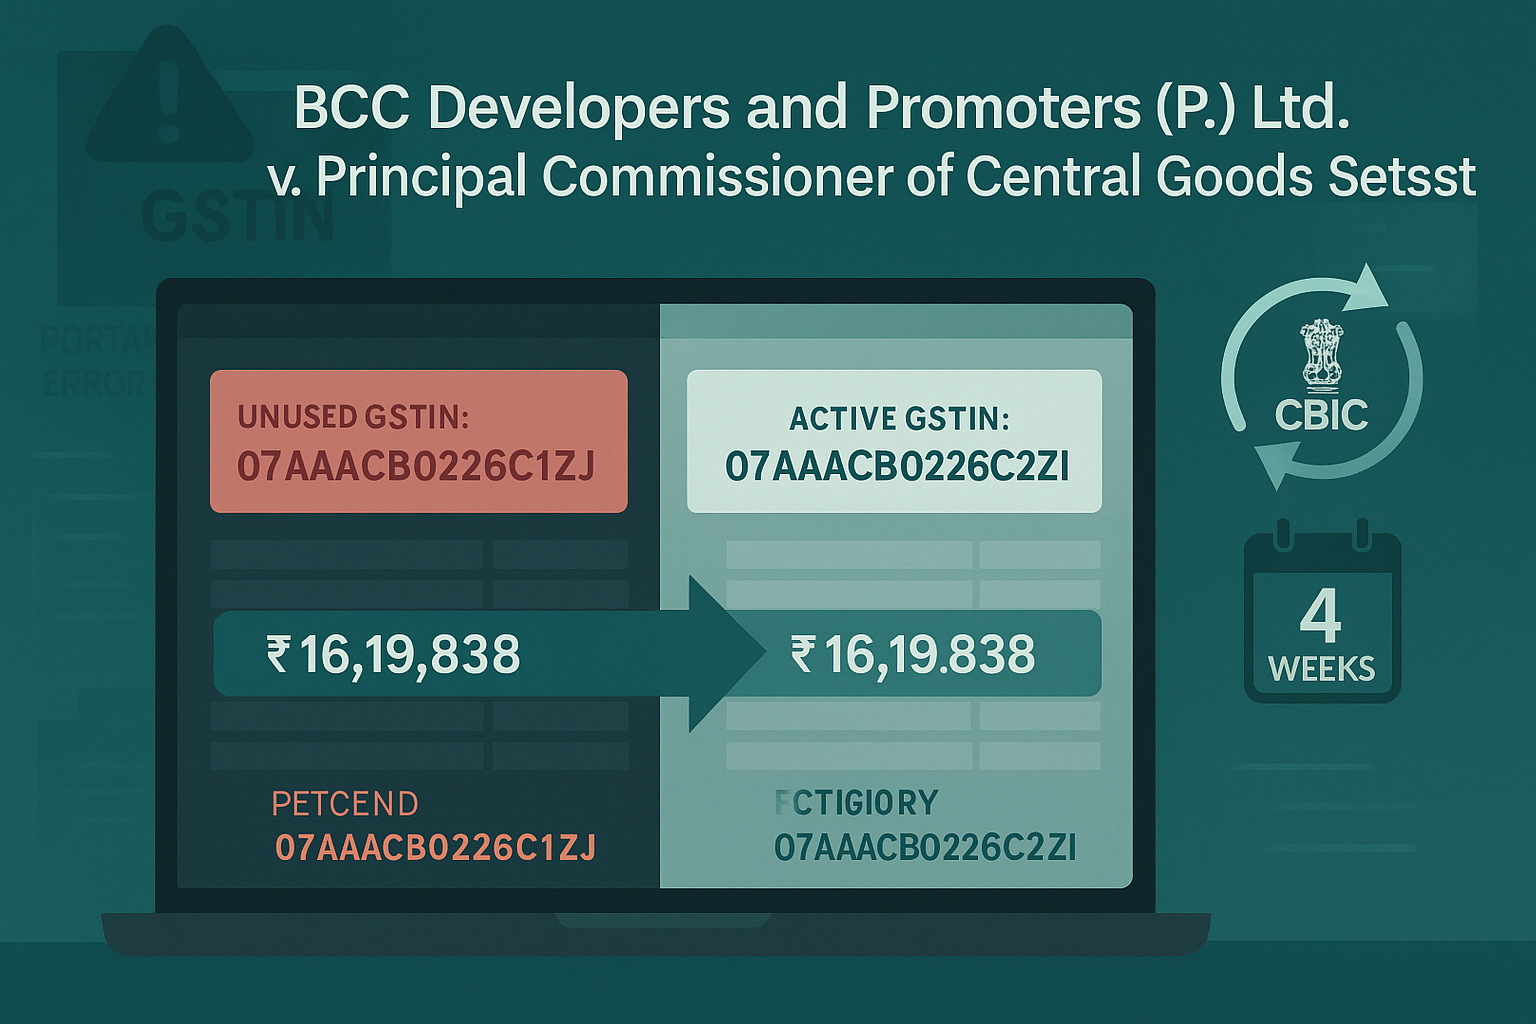
- [¶1] The petitioner sought a refund of ₹16,19,838 deposited against a GSTIN (07AAACB0226C1ZJ) termed as a “non-migrated” number.
- [¶2–3] The petitioner was registered under both VAT and Service Tax in the pre-GST regime. On GST rollout, it consciously migrated only its VAT registration, resulting in a single valid GSTIN: 07AAACB0226C2ZI.
- [¶4–5] The petitioner was unaware that the service tax registration had also been automatically migrated by the system to another GSTIN (non-migrated), which it never used.
- [¶6] Discovery of the non-migrated GSTIN happened when a client’s input tax credit was not reflecting under the active GSTIN.
- [¶7] On search, ₹16,19,838 was found lying in the credit ledger of the unused (non-migrated) GSTIN. The petitioner sought refund or transfer of this amount to its active GSTIN.
Question(s) in Consideration [¶1, ¶7–8]:
- Whether the amount lying in the credit ledger of a GSTIN, created without the taxpayer’s active use or consent (non-migrated), can be refunded or transferred to the valid GSTIN actively used by the taxpayer?
Observation of the Court [¶8–11]:
- [¶8] The respondent confirmed that no provision exists for such intra-GSTIN credit transfers on the portal but acknowledged that the service tax registration had been auto-migrated erroneously.
- [¶9] The Court considered the factual peculiarities—i.e., lack of awareness, no use of the non-migrated GSTIN, and unintentional credit accumulation.
- [¶10–11] It held that the credit of ₹16,19,838 should be transferred to the migrated GSTIN, and further directed CBIC to examine the issue of automatic migration of such GSTINs and resolve such portal-related errors in four weeks.
Judgement of the Court [¶9–14]:
- [¶9] Ordered transfer of the amount from the non-migrated GSTIN to the valid migrated GSTIN.
- [¶11] Directed CBIC to investigate the issue of automatic creation of inactive GSTINs and take corrective action.
- [¶12–14] Scheduled reporting on compliance and instructed that the order be communicated to CBIC.
Between Fine Lines:
- The Court provided relief for GST credited to an inactive GSTIN due to portal error, emphasizing that administrative issues should not penalize taxpayers.
- It validated transfer of such credit to the operative GSTIN in the absence of express portal mechanism.
- The judgement pushes for systemic rectification of technical glitches on the GST portal.
- This ruling opens scope for similarly placed taxpayers to seek relief.
- The Court ensured administrative accountability by directing CBIC to act within a specific timeline.
Summary of Referred Cases:
| Name of Case | Citation | Summary | Verdict |
| None cited | – | No external judgments were referred in this case. | – |
Takeaway:
“Rectifying the Ghost of Auto-Migrated GSTINs: Credit Must Follow Conscious Use”subject



