
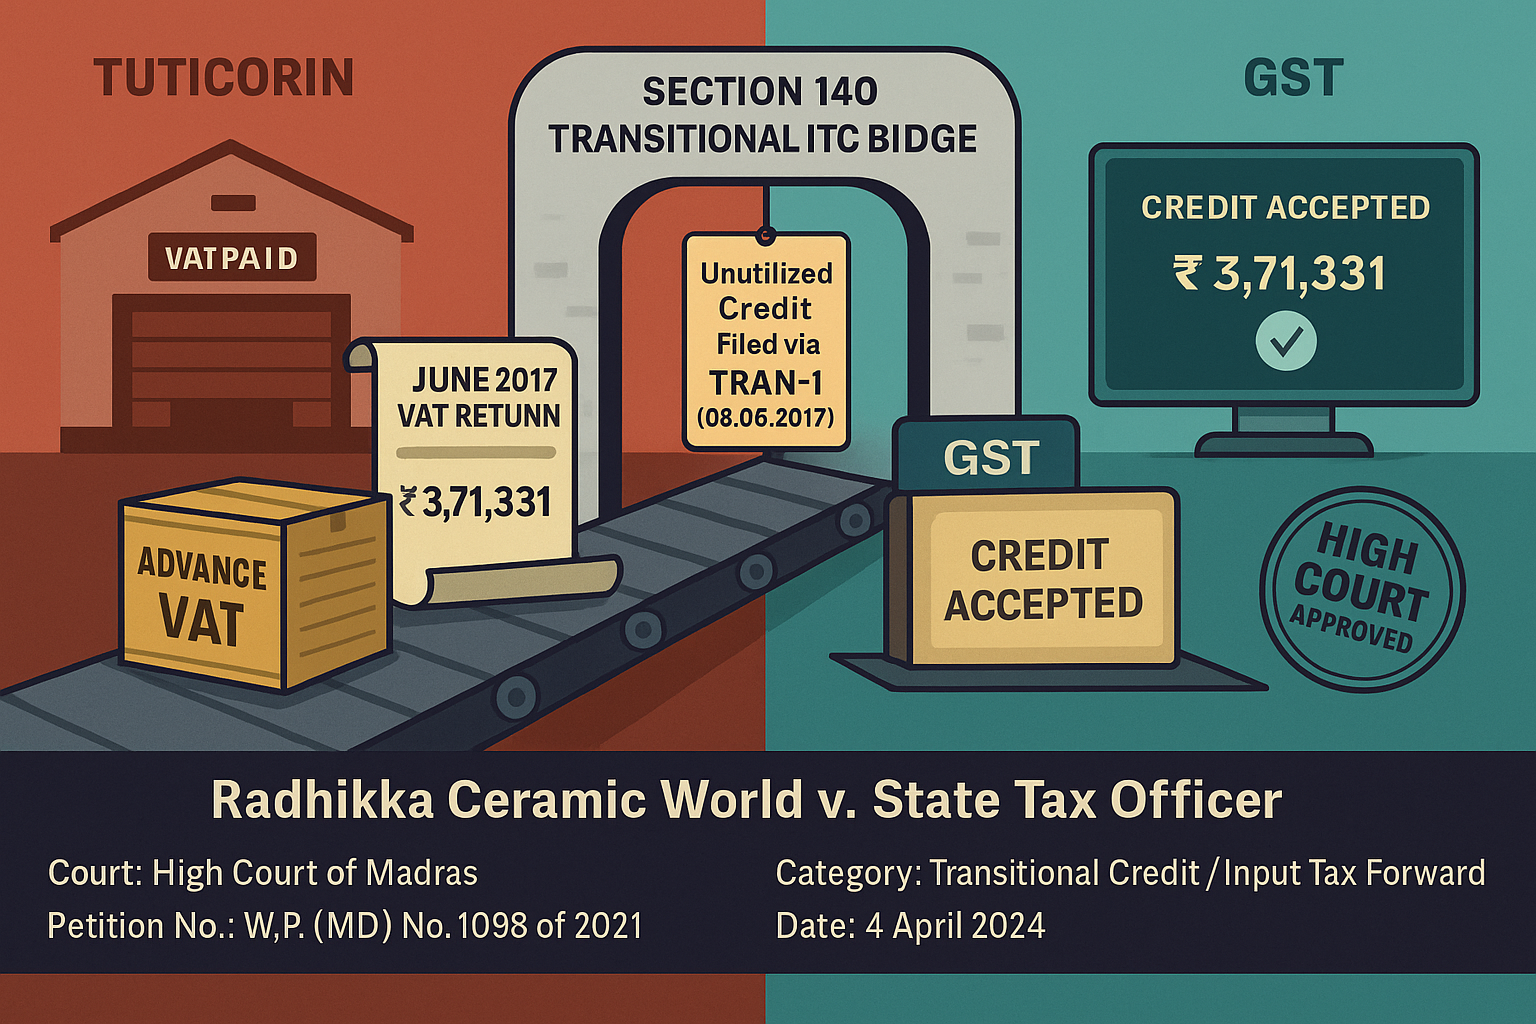
Case Title: Radhikka Ceramic World v. State Tax Officer
Court: High Court of Madras
Petition No.: W.P. (MD) No. 1098 of 2021, W.M.P. (MD) No. 953 of 2021
Category of Dispute: Transitional Credit – Input Tax Credit
Date of Judgment: April 4, 2024
Relevant Sections: Section 140 of the TNGST Act, 2017; Rule 117 of CGST Rules
Takeaway: Advance Tax or ITC? Resolving Transitional Credit Denial
Facts of the Case
[Para 2-4] The petitioner, Radhikka Ceramic World, engaged in inter-state import of ceramic tiles, paid advance VAT of 20% at Tuticorin Port owing to perceived tax evasion in the industry. The said amount remained unutilized in the VAT return for June 2017. The petitioner attempted to transition this amount under Section 140 of the TNGST Act, 2017 through the TRAN-1 form filed on 08.08.2017. The department rejected the claim via order dated 23.12.2019.
Questions in Consideration
[Para 2, 6-7]
- Whether advance VAT paid but unutilized in VAT returns prior to 30.06.2017 qualifies for transition as Input Tax Credit under Section 140 of the TNGST Act?
- Whether the denial of such credit violates the statutory rights of the petitioner?
Observations of the Court
[Para 8-10] The court verified VAT Form-I and confirmed the unutilized balance of ₹3,71,331/- as of June 2017. It noted that Section 140(1) explicitly allows transition of “any amount of VAT and entry tax” remaining unutilized in returns filed before the appointed date.
[Para 11-13] The court relied on precedents:
- Avatar Petro Chemicals (P.) Ltd. v. GST Council: Held that legitimate ITC accrued under the earlier law must be allowed to be carried forward.
- Magma Fincorp Ltd. v. State of Telangana: Advocated purposive interpretation of Section 140 to permit such credit transition.
[Para 14] The Court also held that merely because there is an alternate appellate remedy under Section 107, constitutional rights cannot be rendered illusory due to procedural rigidity.
Judgment of the Court
[Para 14-16] The court allowed the writ petition and quashed the impugned order dated 23.12.2019. The respondent was directed to:
- Permit rectification of TRAN-1, or
- Accept manual TRAN-1, or
- Make suitable credit entries in the petitioner’s Electronic Cash Ledger after verification.
This action must be completed within 90 days of receiving the order.
Between Fine Lines
- Transitional provisions under GST must be interpreted purposively to protect accrued rights.
- Legitimate unutilized tax under VAT can be transitioned under GST via Section 140.
- Advance tax, if recorded and unutilized in returns, qualifies as transitional credit.
- Technical limitations in GSTN or alternative remedies do not bar constitutional relief.
- High Court upheld taxpayer’s right to transition tax credits under legitimate claim.
Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
| Avatar Petro Chemicals (P.) Ltd. v. GST Council | [2022] 136 taxmann.com 297 / (2022) 64 G.S.T.L. 291 | Credit earned under old laws cannot be denied transition due to GST portal limitations. | Transition allowed despite technical error. |
| Magma Fincorp Ltd. v. State of Telangana | [2019] 110 taxmann.com 136 / (2019) 26 G.S.T.L. 7 | Credit available as of 30.06.2017 should not be denied due to procedural issues; purposive interpretation is essential. | Case remanded for reconsideration. |
| Commissioner of GST v. Bharat Electronics Ltd. | W.A. No. 2203 of 2021 (Madras HC, 18.11.2021) | Substantial compliance with transitional provisions suffices to claim credit. | Revised TRAN-1 permitted to be filed. |



