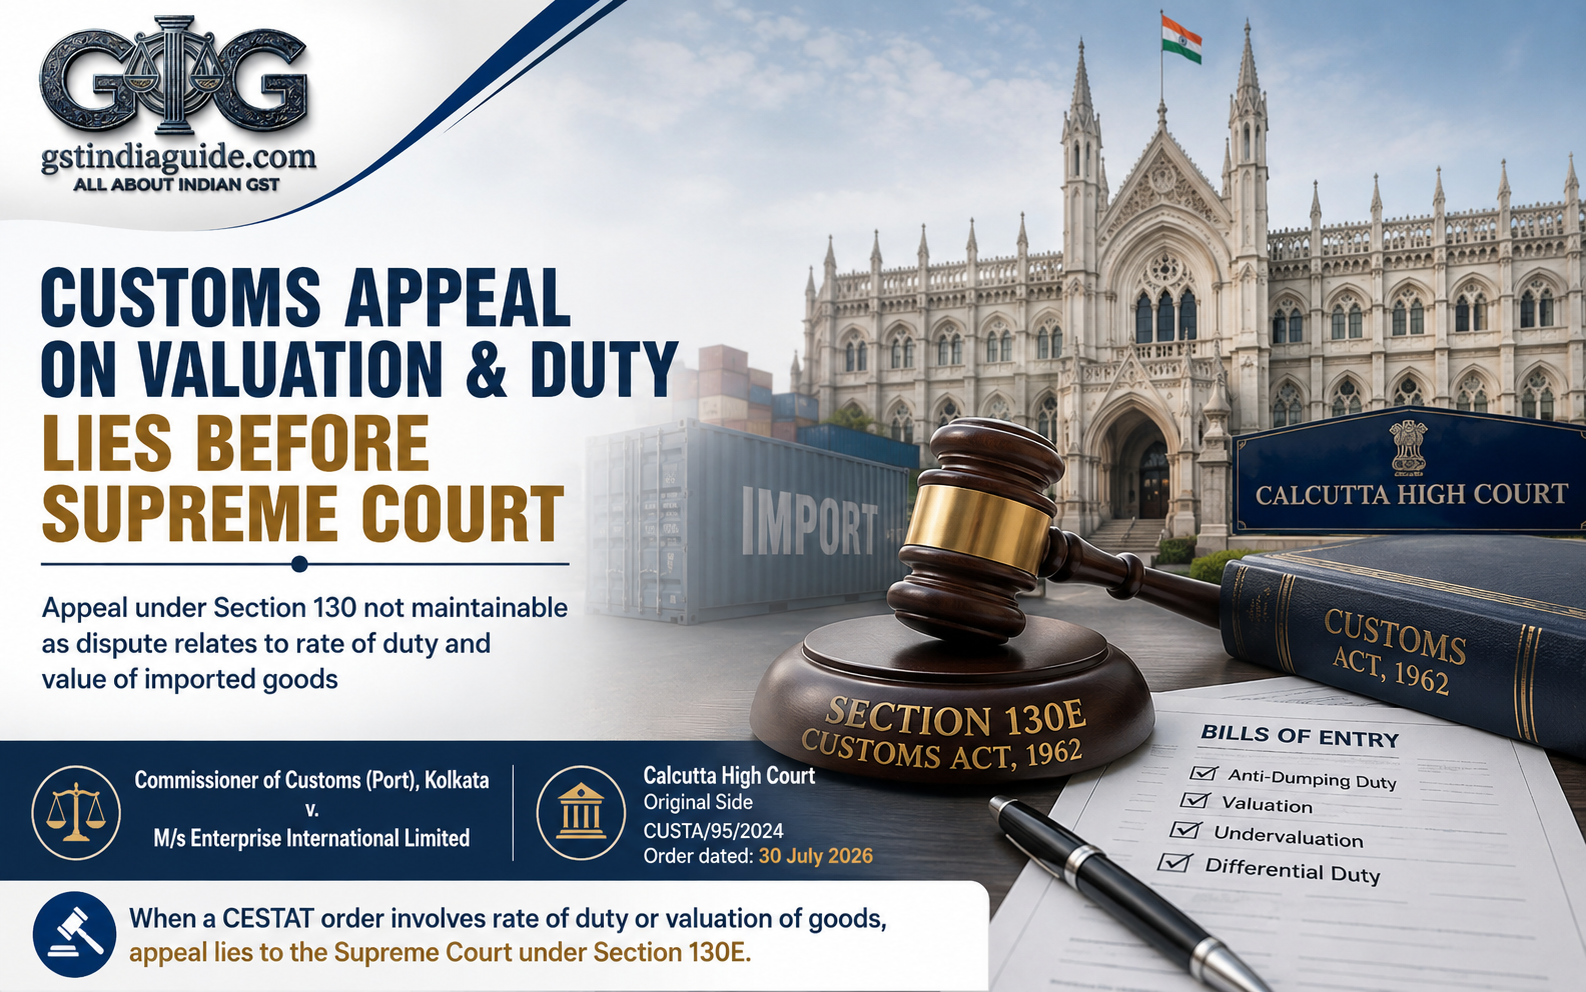
The Calcutta High Court, in Commissioner of Customs (Port), Kolkata v. M/s Enterprise International Limited, examined the maintainability of a departmental appeal filed under Section 130 of the Customs Act, 1962 against an order of the Customs, Excise and Service Tax Appellate Tribunal.
The departmental appeal raised several proposed substantial questions of law concerning liability to anti-dumping duty, rejection and redetermination of the declared value of imported goods, differential customs duty arising from alleged undervaluation, limitation, penalties and the validity of the adjudication order.
At the outset, the Court condoned a delay of 26 days in filing the appeal after accepting the explanation provided by the Customs Department. However, the principal issue before the Court was whether the appeal itself was maintainable before the High Court under Section 130 of the Customs Act.
Dispute Relating to Anti-Dumping Duty and Valuation
The Department questioned the Tribunal’s findings concerning anti-dumping duty in respect of seven Bills of Entry. It also challenged the Tribunal’s decision regarding the rejection of declared values in 26 Bills of Entry and the proposed redetermination of value based on the prices of similar goods.
Other issues included the Tribunal’s conclusion that the adjudication order was unsustainable for violation of the time limits prescribed under Section 28(9) of the Customs Act, the deletion of penalties imposed on the respondents and the rejection of differential duty demands on evidentiary and limitation grounds.
The questions raised by the Department were therefore directly connected with the rate of customs duty, anti-dumping duty and the valuation of imported goods for assessment.
Scope of Section 130 of the Customs Act
Section 130 permits an appeal to the High Court against an order of the Appellate Tribunal where the case involves a substantial question of law. However, the provision specifically excludes Tribunal orders relating, among other things, to the determination of questions connected with the rate of customs duty or the value of goods for assessment.
The High Court observed that the questions proposed by the Department concerned anti-dumping duty, undervaluation and redetermination of the assessable value of imported goods. These matters fell within the statutory exclusion contained in Section 130.
Appeal Required to Be Filed Before Supreme Court
The Court also considered Section 130E of the Customs Act, which provides for an appeal to the Supreme Court against Tribunal orders involving the determination of questions relating to the rate of duty or the value of goods for assessment.
Upon reading Sections 130 and 130E together, the High Court concluded that the Department’s challenge ought to have been preferred before the Supreme Court under Section 130E. The High Court therefore lacked appellate jurisdiction to examine the dispute under Section 130.
Accordingly, the departmental appeal and the connected application were dismissed. The dismissal was based on the statutory appellate forum applicable to disputes concerning customs valuation and rate of duty, rather than an adjudication on the merits of the underlying anti-dumping duty and undervaluation issues.
Key Legal Principle
An appeal against a CESTAT order involving the determination of anti-dumping duty, customs valuation, undervaluation or differential duty connected with the assessable value of imported goods is not maintainable before the High Court under Section 130 of the Customs Act. Such an appeal must be filed before the Supreme Court under Section 130E.
Why This Judgment Matters
The judgment reinforces the statutory distinction between customs appeals maintainable before a High Court and those required to be filed before the Supreme Court. Customs authorities, importers, advocates and tax professionals must carefully identify whether the dispute concerns a general substantial question of law or directly relates to the rate of duty or valuation of goods before selecting the appellate forum.
The decision is particularly relevant in disputes involving anti-dumping duty, rejection of transaction value, valuation based on comparable imports, differential customs duty and allegations of undervaluation.