
Case Title: M/s. HITECH CNC Engineering v. Deputy Commissioner (Commercial Tax)
Court: High Court of Judicature at Madras
Petition No.: W.P. No. 16902 of 2025
Relevant Section: Sections 107 and 121 of CGST Act, 2017
Category of Dispute: Appeal Filing Delay – Summary Assessment
Date of Judgment: 03 June 2025
Relevant CGST Sections: Section 107 (Appeals to Appellate Authority), Section 121 (Non-appealable decisions)
📝 Facts of the Case [¶3, ¶6]
-
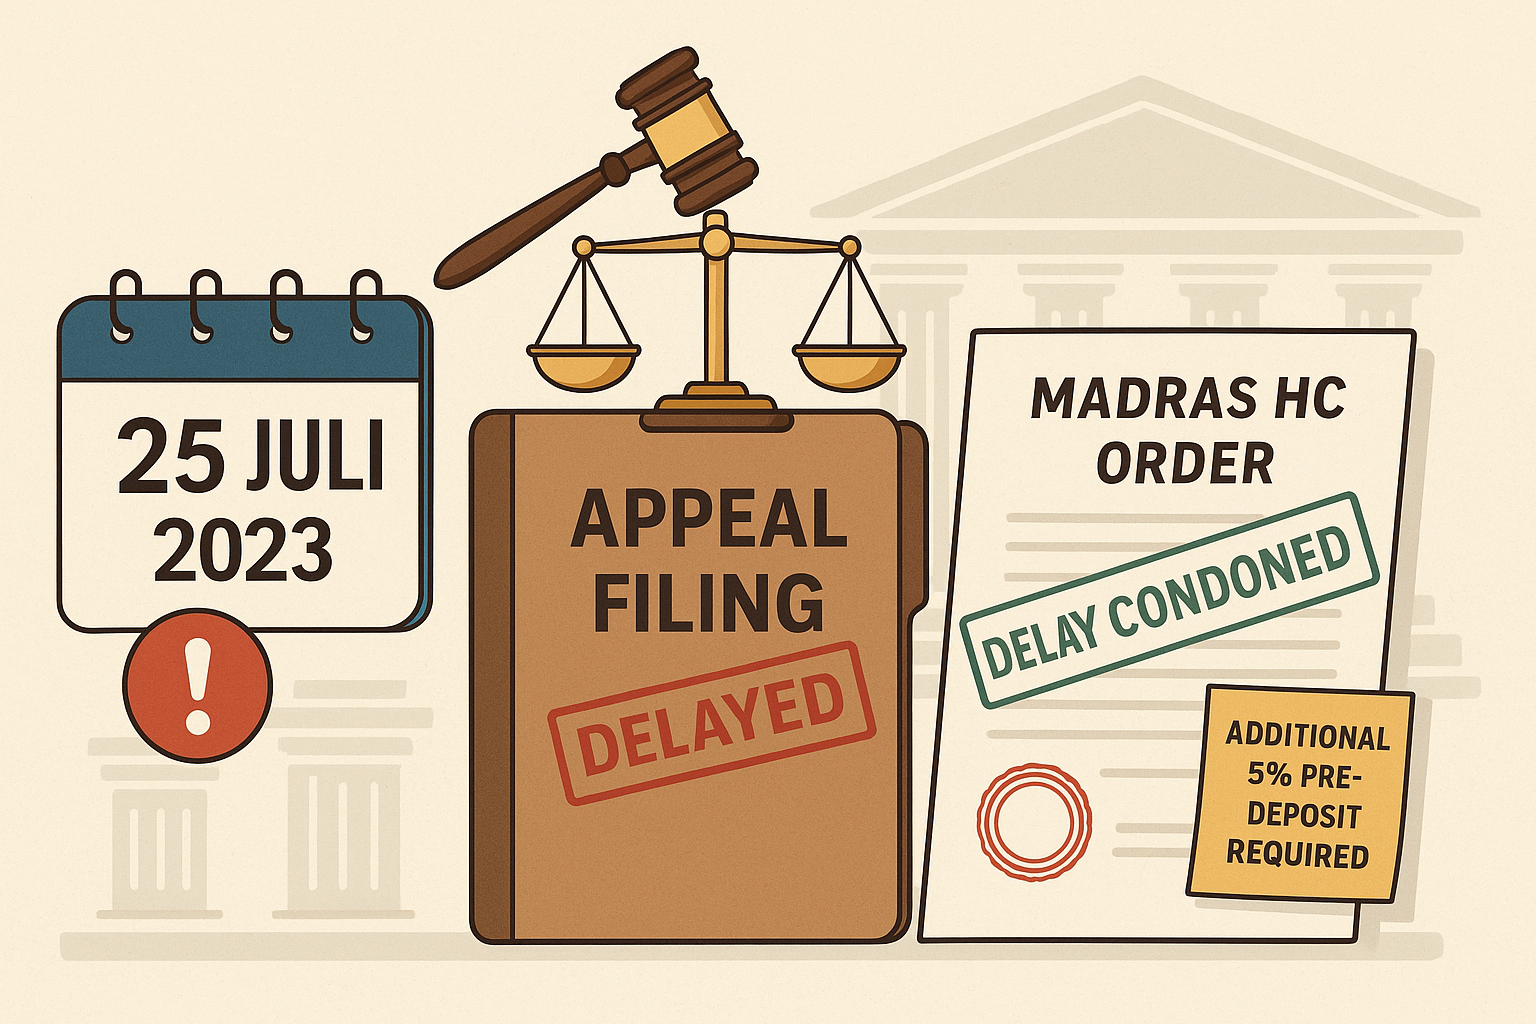
The petitioner, M/s. HITECH CNC Engineering, was unaware of the ex parte summary order dated 25.07.2023 passed by the Commercial Tax Officer.
-
As a result, the appeal against the said summary order was filed belatedly on 04.09.2024 with a delay of 285 days.
-
The appeal was dismissed by the first respondent (Appellate Authority) on 04.11.2024 on the ground that the delay exceeded the condonable limit under GST law.
❓Question(s) in Consideration [¶3, ¶6, ¶7]
-
Whether the 285-day delay in filing the appeal against the ex parte summary order can be condoned on equitable grounds?
-
Whether the appellate authority acted in violation of natural justice by dismissing the appeal without examining the reasons for delay?
👩⚖️ Observations of the Court [¶7, ¶8]
-
The Court observed that the delay was due to the petitioner’s unawareness of the ex parte summary order and found the explanation plausible.
-
It emphasized that the right to appeal should not be defeated on technical grounds where the delay was genuine.
-
To balance equity and statutory limitation, the Court allowed the delay subject to an additional 5% pre-deposit of the disputed tax amount (over and above the statutory 10% already deposited).
⚖️ Judgment of the Court [¶8, ¶9]
-
The impugned appellate dismissal order dated 04.11.2024 was quashed.
-
The delay of 285 days in filing the appeal was condoned, conditional on the petitioner paying an additional 5% of the disputed tax within four weeks.
-
The Appellate Authority was directed to hear the appeal on merits and pass orders in accordance with law after granting a fair opportunity to the petitioner.
📌 Between Fine Lines
This judgment shows that even delays beyond the statutory period may be condoned if the petitioner can show genuine unawareness or procedural lapses. The Court balanced legal rigour with fairness by imposing an additional pre-deposit. Businesses should monitor GST orders closely, but this ruling offers relief for those blindsided by ex parte actions.
📚 Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
|---|---|---|---|
| No specific cases were cited in the judgment | — | — | — |



