Case Reference:
-
Case Title: Deepak Sharma v. Commissioner Department of Trade and Taxes, Govt. of NCT Delhi
-
Court: High Court of Delhi at New Delhi
-
Petition No.: W.P.(C) 4922/2025
-
Date of Judgment: 17.04.2025
-
Relevant Section: Article 226 of the Constitution of India, Section 29 CGST Act (Cancellation of registration), Rule 22 CGST Rules
-
Category of Dispute: Cancellation of GST Registration
Facts of the Case (Paras 3–4)
-
The petitioner challenged a Show Cause Notice (SCN) dated 19.03.2024 issued by the Department of Trade and Taxes, NCT of Delhi for cancellation of GST registration.
-
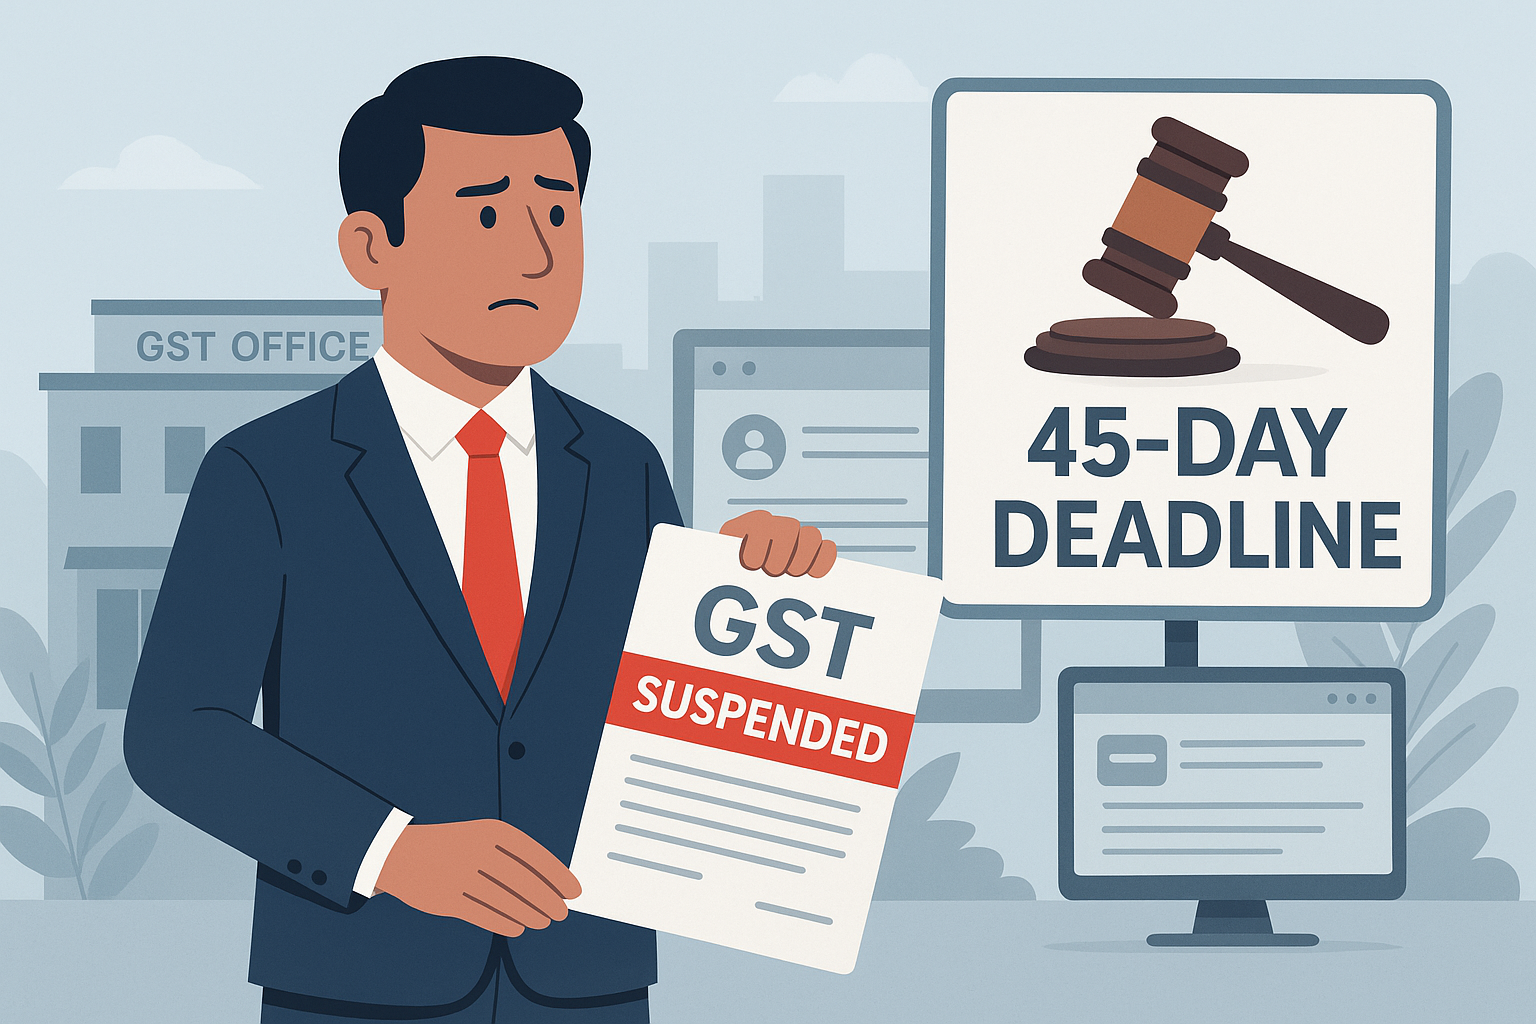
Alongside the SCN, the petitioner’s registration was suspended from the same date, effectively halting his business operations.
-
The petitioner claimed to have filed a reply, but the proceedings were not brought to a conclusion, leaving the registration under indefinite suspension.
Question(s) in Consideration (Paras 3–5)
-
Whether prolonged suspension of GST registration without concluding SCN proceedings is legally sustainable.
-
Whether the department must ensure time-bound disposal of cancellation proceedings with due hearing to the assessee.
Observations of the Court (Paras 5–6)
-
The Court recognized that cancellation of GST registration brings business to a standstill, impacting livelihood and trade.
-
Proceedings under the SCN must be concluded within a definite timeframe, as indefinite suspension is arbitrary and prejudicial.
-
The Court emphasized the need for a personal hearing and directed that notice of such hearing must be properly communicated through the GST portal and via the petitioner’s email and mobile.
Judgment of the Court (Paras 5–7)
-
The Court directed the Respondent–GST Department to conclude the SCN proceedings within 45 days.
-
It ordered that a personal hearing shall be granted, with notice served both electronically and on the GST portal.
-
The writ petition was disposed of with these directions.
Between Fine Lines (Simplified Outcome)
-
GST registration cannot be kept under indefinite suspension pending SCN.
-
Department must conclude proceedings in a time-bound manner (45 days).
-
Personal hearing is mandatory before cancellation.
-
Authorities must ensure proper communication of notices via portal, email, and mobile.
-
The Court provided relief by ensuring business continuity till proper adjudication.
Summary of Referred Cases
(No external cases referred in this judgment)
Disclaimer – “The above summary is for academic purpose only; not formal legal opinion. Seek professional opinion before application. Author or publisher or website shall not be responsible for any usage in any form.”