
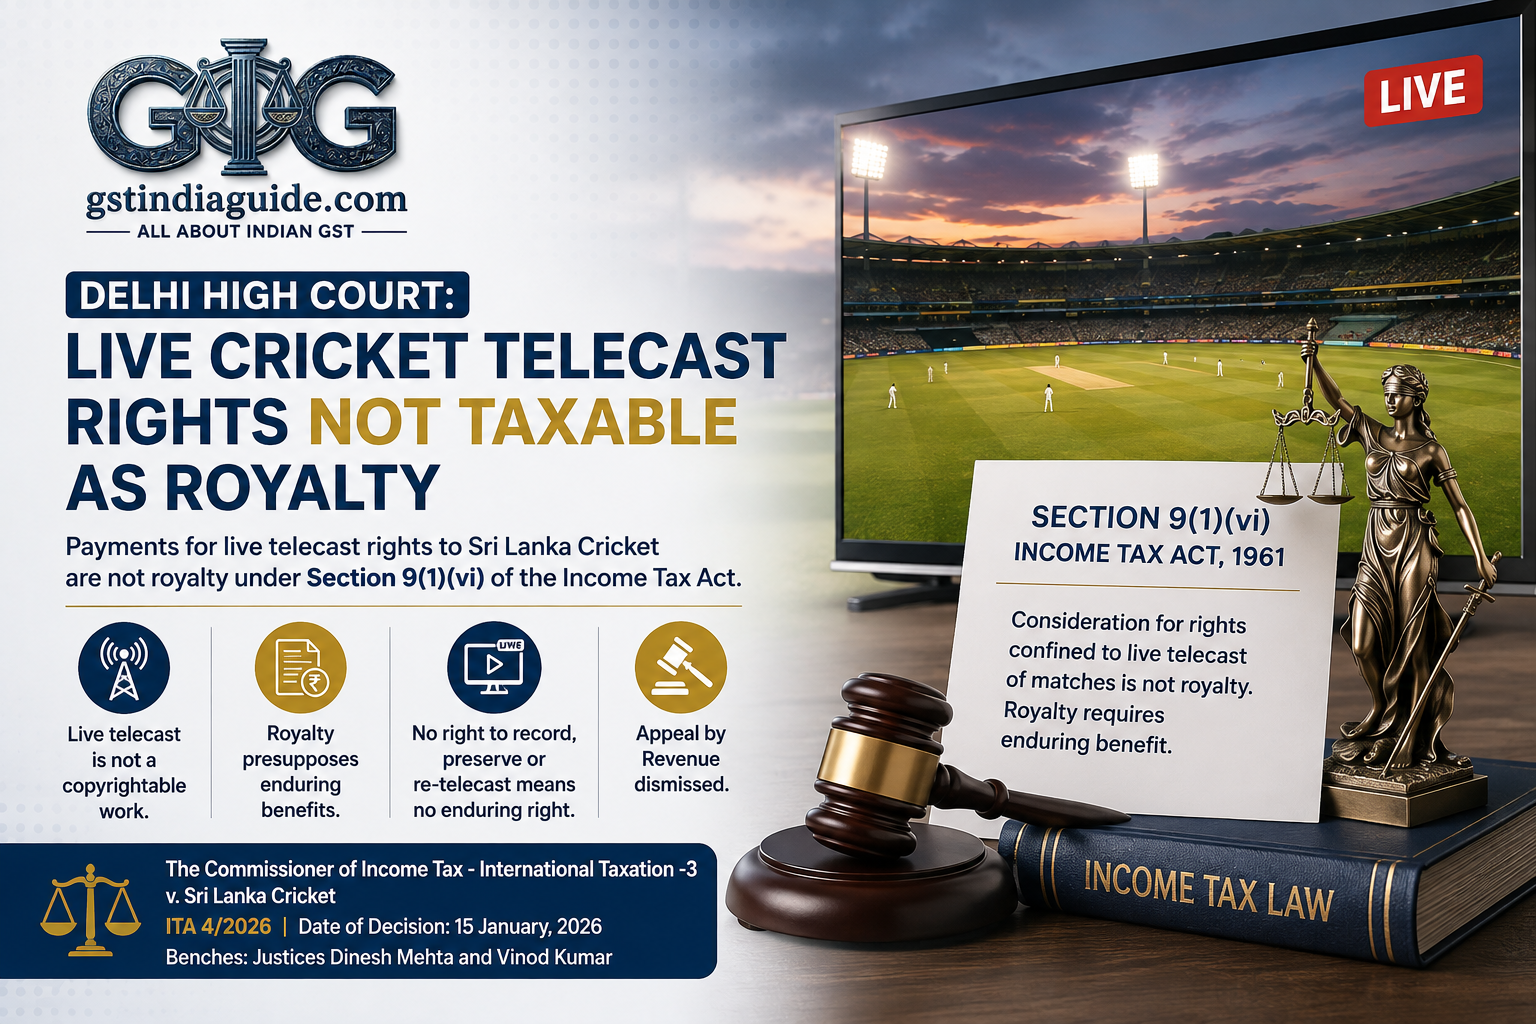
In The Commissioner of Income Tax – International Taxation -3 v. Sri Lanka Cricket, ITA 4/2026, the Delhi High Court examined whether consideration received by Sri Lanka Cricket for granting rights to show cricket matches through live telecast could be classified as royalty income under Section 9(1)(vi) of the Income Tax Act, 1961.
The judgment was delivered on 15 January 2026 by a Division Bench comprising Hon’ble Mr. Justice Dinesh Mehta and Hon’ble Mr. Justice Vinod Kumar.
Background of the Dispute
The Revenue challenged the treatment of payments received by Sri Lanka Cricket for granting rights relating to live transmission of cricket matches.
Before the Delhi High Court, Sri Lanka Cricket submitted that the issue was squarely covered by the Court’s earlier judgment in CIT (International Taxation) v. Fox Network Group Singapore Pte. Ltd., which had followed the decision in CIT v. Delhi Race Club (1940) Ltd.
The respondent further pointed out that an SLP involving an identical issue had been withdrawn by the Department before the Supreme Court on 13 January 2026.
The Revenue was unable to point out any material demonstrating that the exhibition rights granted by Sri Lanka Cricket went beyond the live feed of the cricket matches.
Live Telecast Does Not Amount to Copyright Royalty
The Delhi High Court relied on the legal position explained in Fox Network Group Singapore Pte. Ltd. and Delhi Race Club (1940) Ltd.
The Court noted that a live telecast or broadcast does not constitute a “work” carrying copyright in the manner contemplated by clause (v) of Explanation 2 to Section 9(1)(vi).
The earlier decisions had distinguished copyright from broadcasting reproduction rights and held that a live broadcast, by itself, does not fall within the scope of copyright royalty contemplated by the provision.
Accordingly, income derived from a live feed could not be brought within the definition of royalty merely because technology was used for transmission.
Royalty Presupposes an Enduring Benefit
The Court further observed that the rights granted by Sri Lanka Cricket were confined to the live telecast of the matches held in the relevant series.
The payments were made only for those matches and did not confer rights in relation to subsequent matches.
Importantly, the licensee did not have the right to record or preserve the feed and thereafter derive continuing benefit by re-telecasting or showing the matches in future.
The Court expressly observed that “royalty presupposes enduring benefits.”
Therefore, where the licensee only receives the right to show a live event and does not obtain any continuing right over a recording or content capable of future exploitation, the consideration cannot be treated as royalty.
When Could Such Payment Potentially Be Royalty?
The judgment clarifies that a different tax consequence could arise where the licensee is granted broader rights.
For example, where the licensee is entitled to:
- record or preserve the feed;
- retain the recording after the live event;
- re-telecast the match in future; or
- commercially exploit the recorded content beyond the specified event,
the nature of the payment may require a different examination.
In the present case, however, no such continuing or enduring rights were granted.
Court Follows Fox Network Decision
The Court also referred to its earlier ruling in Fox Network Group Singapore Pte. Ltd., where it had held that fees received for live transmission could not be classified as royalty income under Section 9(1)(vi).
Since the factual position in the Sri Lanka Cricket case did not extend beyond the live feed, the Court found no reason to take a different view.
The Revenue’s appeal therefore did not give rise to any substantial question of law.
Final Decision
The Delhi High Court held that the consideration received by Sri Lanka Cricket for rights limited to the live telecast of cricket matches could not be characterized as royalty.
Accordingly, the appeal filed by the Income Tax Department was dismissed.
Key Takeaway
The judgment reinforces the distinction between a temporary right to access or transmit a live sporting event and the grant of enduring intellectual property or exploitation rights.
Where broadcasting rights are confined to a live feed and the licensee has no right to record, preserve or subsequently re-telecast the content, the payment does not acquire the character of royalty merely because the subject matter is transmitted using sophisticated technology.
Case: The Commissioner of Income Tax – International Taxation -3 v. Sri Lanka Cricket
Citation: ITA 4/2026
Court: Delhi High Court
Bench: Hon’ble Mr. Justice Dinesh Mehta and Hon’ble Mr. Justice Vinod Kumar
Date of Decision: 15 January 2026
Provision: Section 9(1)(vi), Income Tax Act, 1961
Result: Revenue’s Appeal Dismissed.



(vi) of the Income Tax Act.)