
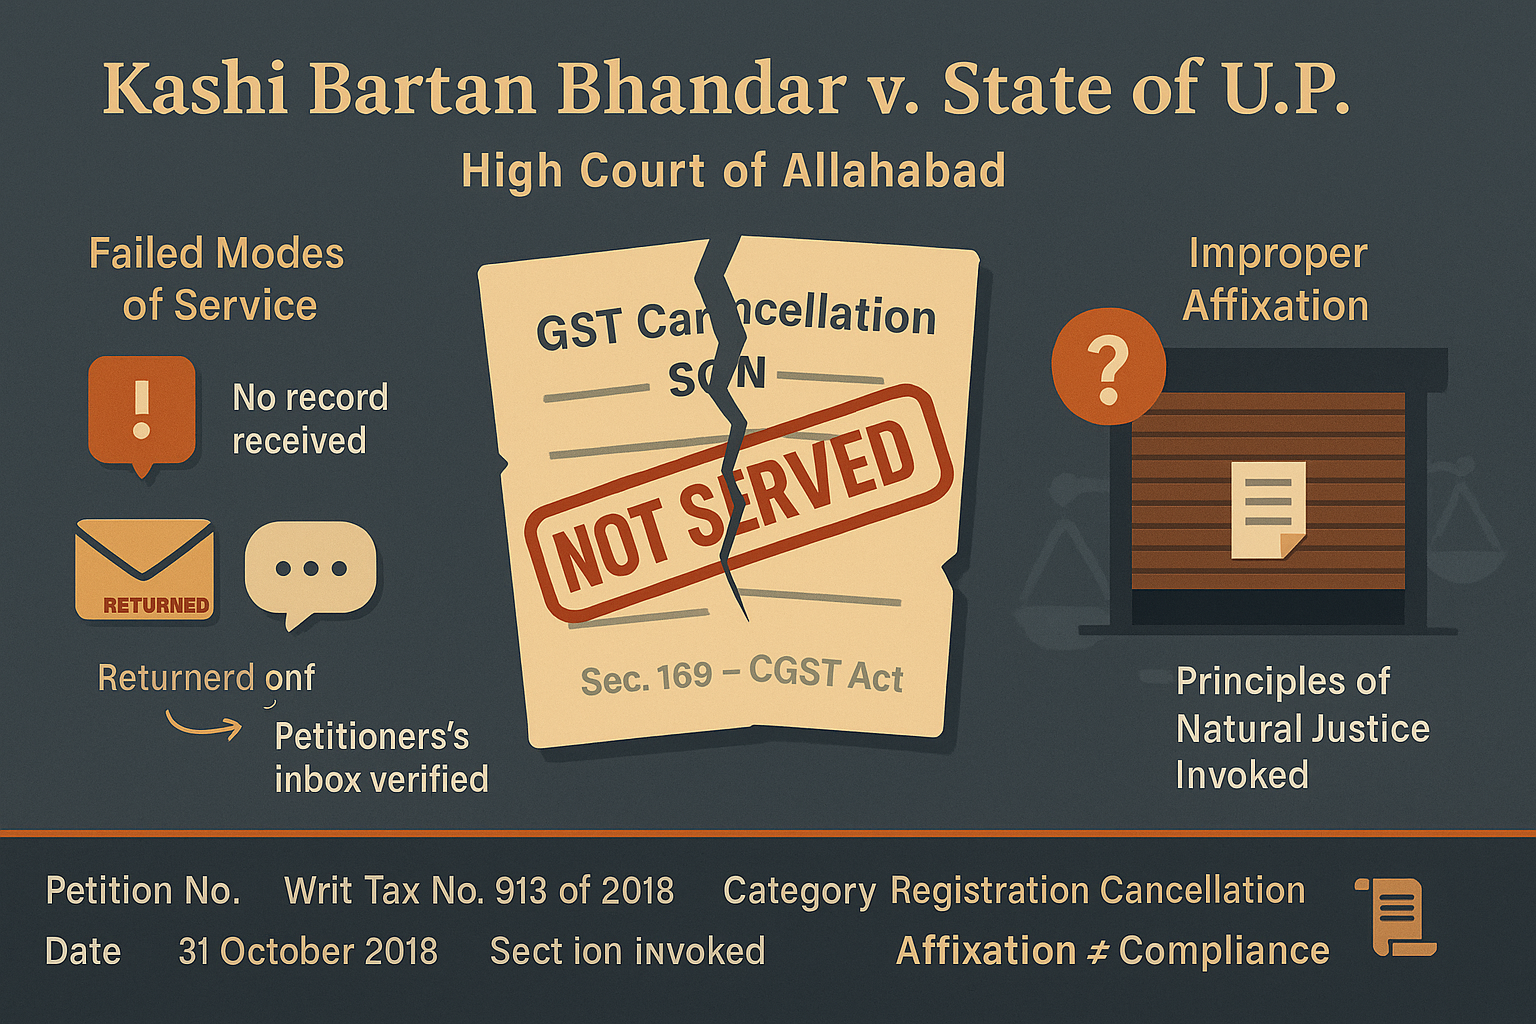
Kashi Bartan Bhandar v. State of U.P.
High Court of Allahabad
Writ Tax No. 913 of 2018
Category of Dispute: Registration Cancellation
Date of Judgement: 31 October 2018
Relevant Section: Section 169 of the CGST Act, 2017
Facts of the Case
- The petitioner, Kashi Bartan Bhandar, challenged the order dated 27.01.2018 passed by the Assistant Commissioner, Commercial Tax, Sector-18, Varanasi, which cancelled its GST registration under the U.P. GST Act
- The primary grievance was that the cancellation order was passed without serving a proper show-cause notice as required under Section 169 of the Act. The petitioner claimed no notice was served either physically, via post, or through electronic means
- The Department argued that the notice was sent via email, messenger, and by affixation at the business premises, which the petitioner denied, claiming no such email or service had occurred
- The department failed to provide any material evidence showing service of notice via permitted modes or to demonstrate the impracticability of those modes before opting for affixation
Questions in Consideration
- Whether the cancellation of GST registration without proper service of a show-cause notice violates principles of natural justice?
- Whether affixation of notice without exhausting other prescribed methods under Section 169 of the CGST Act is legally valid?
Observations of the Court
- The Court noted that Section 169 provides specific modes for service of notice, and affixation is only permissible when other modes are found impracticable. The Assistant Commissioner failed to record any finding on this point
- No evidence was provided regarding who served the notice, when it was served, or the manner of affixation, making the service improper
- The alleged email service was unsubstantiated, and the petitioner demonstrated with inbox records that no such email was received
- The cancellation order was based merely on a prima facie assumption that the business was closed, without any substantial proof
- The Court rejected the plea to relegate the petitioner to appellate remedy, stating that violation of natural justice warrants writ jurisdiction despite alternate remedies.
Judgement of the Court
- The Hon’ble Court held that the cancellation order dated 27.01.2018 was passed in violation of the principles of natural justice due to absence of proper service of notice.
- The order was quashed, and liberty was given to the Assistant Commissioner to proceed afresh in accordance with law
Between Fine Lines
- GST registration cannot be cancelled without following due process.
- Proper service of notice as per Section 169 is mandatory.
- Affixation is a last resort and must be justified.
- Presumptions without evidence cannot support cancellation.
- Writ remedy is available when principles of natural justice are violated.
Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
| No specific cases cited in the judgement | — | — | — |



