
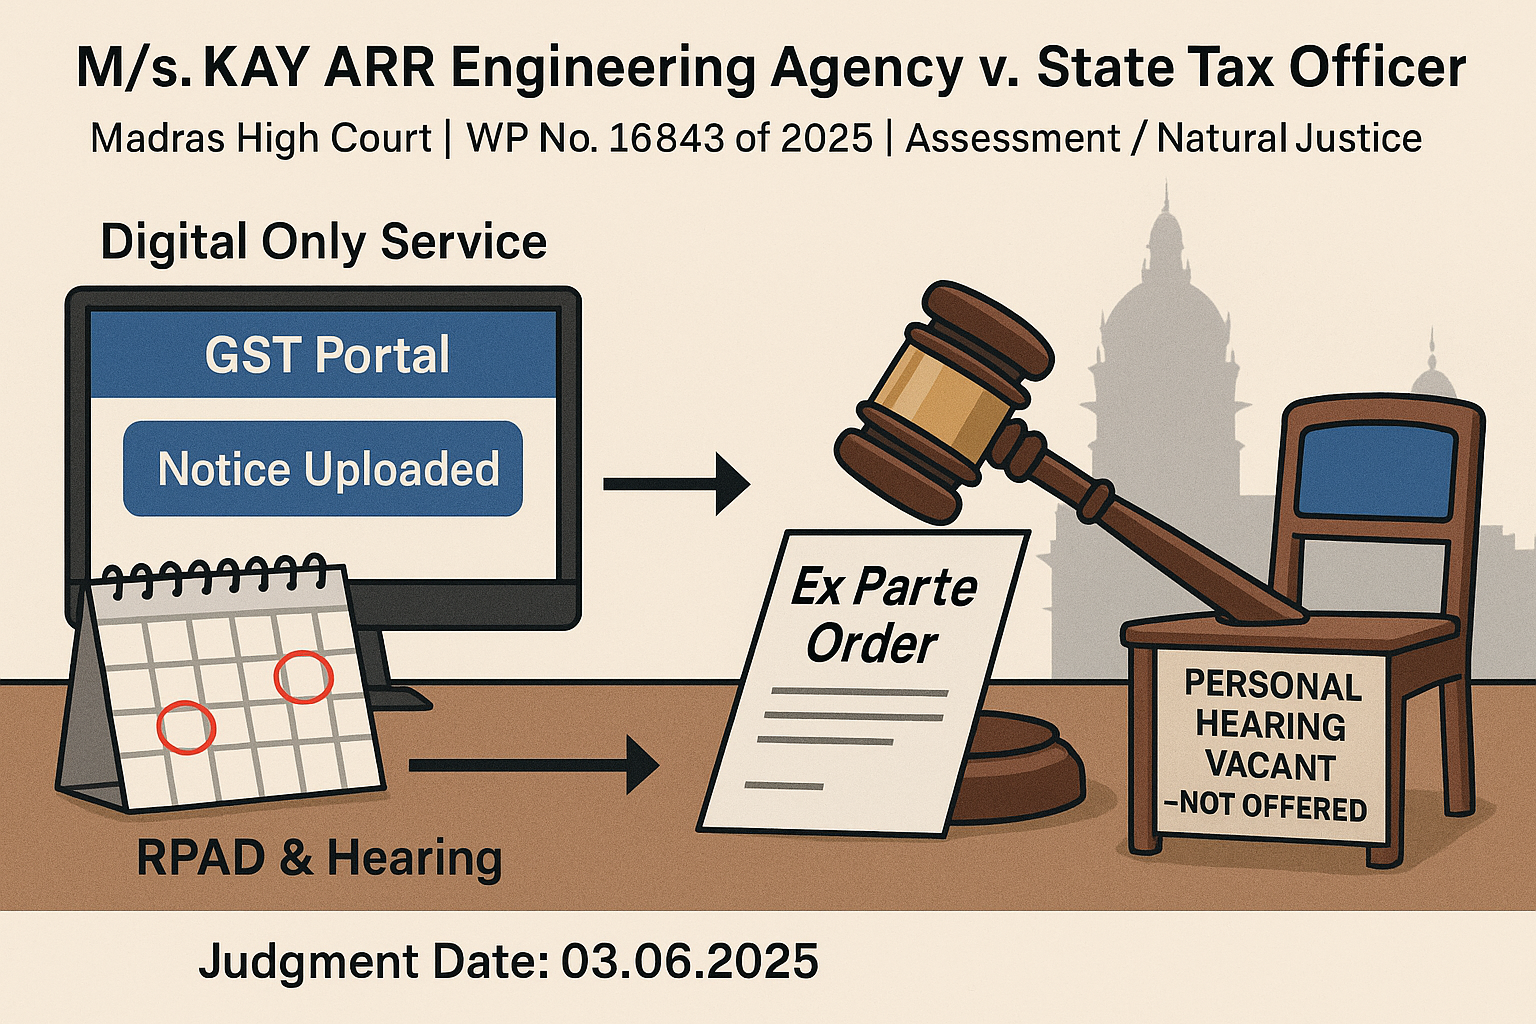
Case Details
Case Title: M/s. KAY ARR Engineering Agency v. State Tax Officer
Court: High Court of Madras
Petition No.: W.P. No. 16843 of 2025
Category: Natural Justice / Assessment Proceedings
Date of Judgment: 03.06.2025
Relevant Sections: Section 73 and Section 169 of CGST/TNGST Act, 2017
Dispute Category: Assessment / Opportunity of Hearing / Mode of Notice Service
🧾 Facts of the Case [¶1–4, 7–9]
-
The petitioner challenged the assessment order dated 06.02.2025 under Section 73 for FY 2020-21.
-
The show cause notice and related communications were uploaded only under the “View Additional Notices and Orders” tab on the GST portal, without other modes of service.
-
The petitioner was unaware of these notices and failed to respond or appear.
-
No personal hearing was granted before passing the order.
-
The petitioner expressed willingness to pay 10% of the disputed tax for reconsideration.
❓Question(s) in Consideration [¶3, 7–9]
-
Whether uploading notices solely on the GST portal suffices as valid service under Section 169?
-
Whether the absence of a personal hearing vitiates the assessment order?
👨⚖️ Observations of the Court [¶7–9]
-
While portal-based notice service is technically valid under Section 169, exclusive reliance on it—despite no response from the taxpayer—defeats the purpose of effective communication.
-
The respondent ought to have explored other prescribed service modes (e.g., RPAD) upon non-response.
-
Passing an ex parte order without genuine attempt to communicate or personal hearing amounts to denial of natural justice and leads to avoidable litigation.
-
The system should not treat digital service as a mere formality; meaningful opportunity must be ensured.
🧾 Judgement of the Court [¶10]
-
The assessment order dated 06.02.2025 was set aside.
-
The matter was remanded to the respondent subject to:
-
Petitioner paying 10% of disputed tax within 4 weeks.
-
Petitioner to file objections with supporting documents within 3 weeks from such payment.
-
Respondent to provide a 14-day clear notice and personal hearing before passing fresh order on merits.
-
📌 Between Fine Lines
-
Uploading notices on the portal alone is not enough—tax officers must ensure real communication.
-
Courts discourage mechanical service of notices without applying mind to the efficacy of delivery.
-
The right to personal hearing is fundamental to fair assessment under GST.
-
A taxpayer’s non-response should trigger additional efforts for notice service.
-
The Madras HC promotes substance over form in tax adjudication procedures.
📚 Summary of Referred Cases
| Name | Citation | Summary | Verdict |
|---|---|---|---|
| None specifically referred in this judgment | – | – | – |



