
AJE India (P.) Ltd. v. Union of India
Court: Bombay High Court
Petition Number: Writ Petition (ST.) No. 97165 of 2020
Category: Provisional Attachment under Section 83
Date of Judgement: 22 December 2020
Relevant Sections: Section 83 read with Section 67 of CGST Act, 2017 and Maharashtra GST Act, 2017
Takeaway: “Discretionary Power of Attachment Cannot Be Arbitrary”
Facts of the Case [Paras 4–12]
- Business and Classification: The petitioner, AJE India Pvt. Ltd., manufactures and supplies carbonated fruit drinks and had classified its goods under HSN 2202 99 20 at 12% GST, based on earlier SC and CESTAT decisions (Para 4).
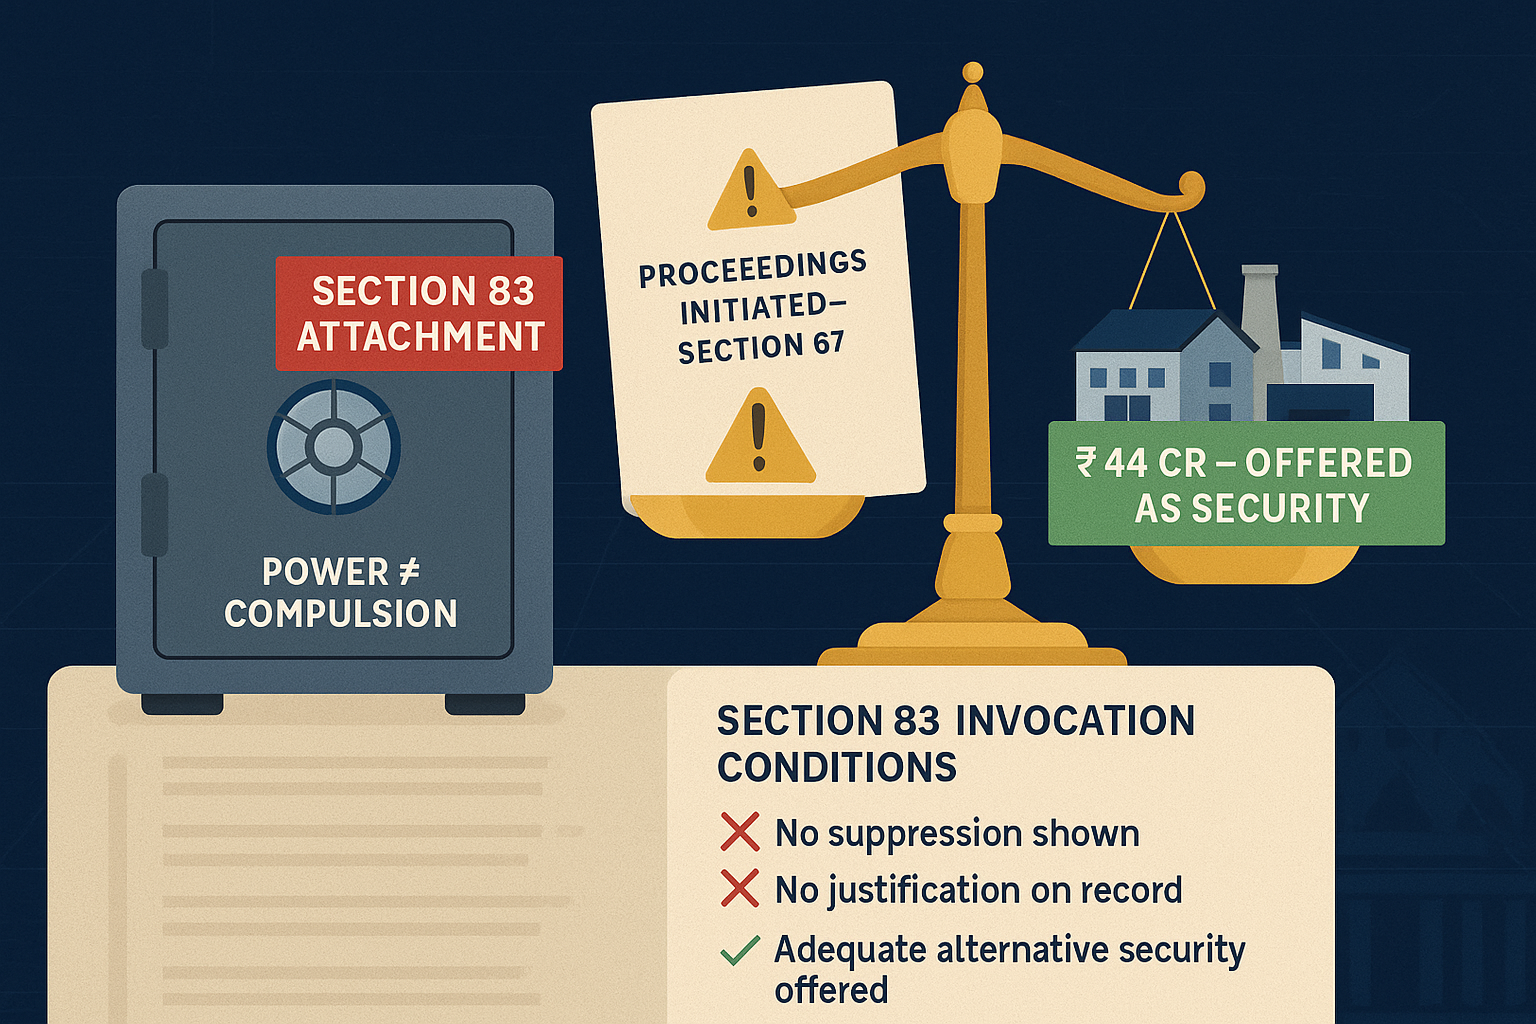
- Proceedings Initiated: The department initiated proceedings under Section 67 alleging misclassification, which led to a short payment of around ₹33 crores between Dec 2017 and Feb 2020 ([Paras 6, 10, 11]).
- Attachment Order: On 18/19 Nov 2020, the Commissioner issued an order under Section 83 attaching three bank accounts of the petitioner ([Para 7]).
- Offer of Security: The petitioner offered land, building, and machinery valued at ₹44 crores to secure revenue interest ([Para 27]).
- Challenge Filed: The petitioner challenged the attachment before the High Court through a writ petition under Article 226 ([Para 2]).
Questions in Consideration [Paras 14–15]
- Whether mere pendency of proceedings under Section 67 justifies invoking Section 83 for provisional attachment of bank accounts?
- Whether the discretionary power under Section 83 was exercised in a fair and non-arbitrary manner?
Observations of the Court
- Nature of Section 83 [Paras 17–18]: The Court emphasized that Section 83 is discretionary and should be exercised judiciously, only if required to protect revenue.
- Non-automatic Invocation [Para 25]: Mere pendency under Section 67 does not automatically trigger Section 83 unless suppression or evasion is prima facie established.
- Absence of Justification [Para 25]: The original record did not indicate any analysis as to why attachment of bank accounts was necessary over other assets.
- Offer of Adequate Security [Para 27]: Since the petitioner offered substantial immovable assets, immediate bank account attachment was excessive.
- Misuse of Power [Para 26]: Having power under Section 83 does not mean it can be exercised mechanically or without due regard to circumstances.
Judgement of the Court [Paras 28–29]
- The Bombay High Court stayed the impugned order dated 18/19 November 2020 and directed the authorities to withdraw the bank account attachment forthwith.
- The petitioner was required to file an undertaking not to alienate the land, building, or plant and machinery during the pendency of proceedings.
Between Fine Lines
- Section 83 of CGST is a discretionary, not automatic, tool for revenue protection.
- Misclassification alone, without evidence of deliberate suppression, doesn’t justify provisional attachment.
- Offering alternate security must be given due weight before attaching bank accounts.
- Courts guard against arbitrary and excessive use of administrative power.
- Judicial scrutiny ensures proportionality and procedural fairness.
Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
| Parle Agro (P) Ltd. v. CIT | [2017] 81 taxmann.com 194 (SC) | Recognized classification of beverages with >10% juice as fruit drinks | Referred by Petitioner |
| Brindavan Beverages (P.) Ltd. v. CCE | [2020] 113 taxmann.com 178 (CESTAT LB) | Affirmed classification of beverages with 5-10% juice as fruit juice based drinks | Referred by Petitioner |
| M/s Anutham Exim Pvt. Ltd. – Comm. Customs (Appeals) | Not cited separately (Kolkata, 8 June 2020) | Upheld 12% GST classification for imported beverages from Bhutan | Referred by Petitioner |



