
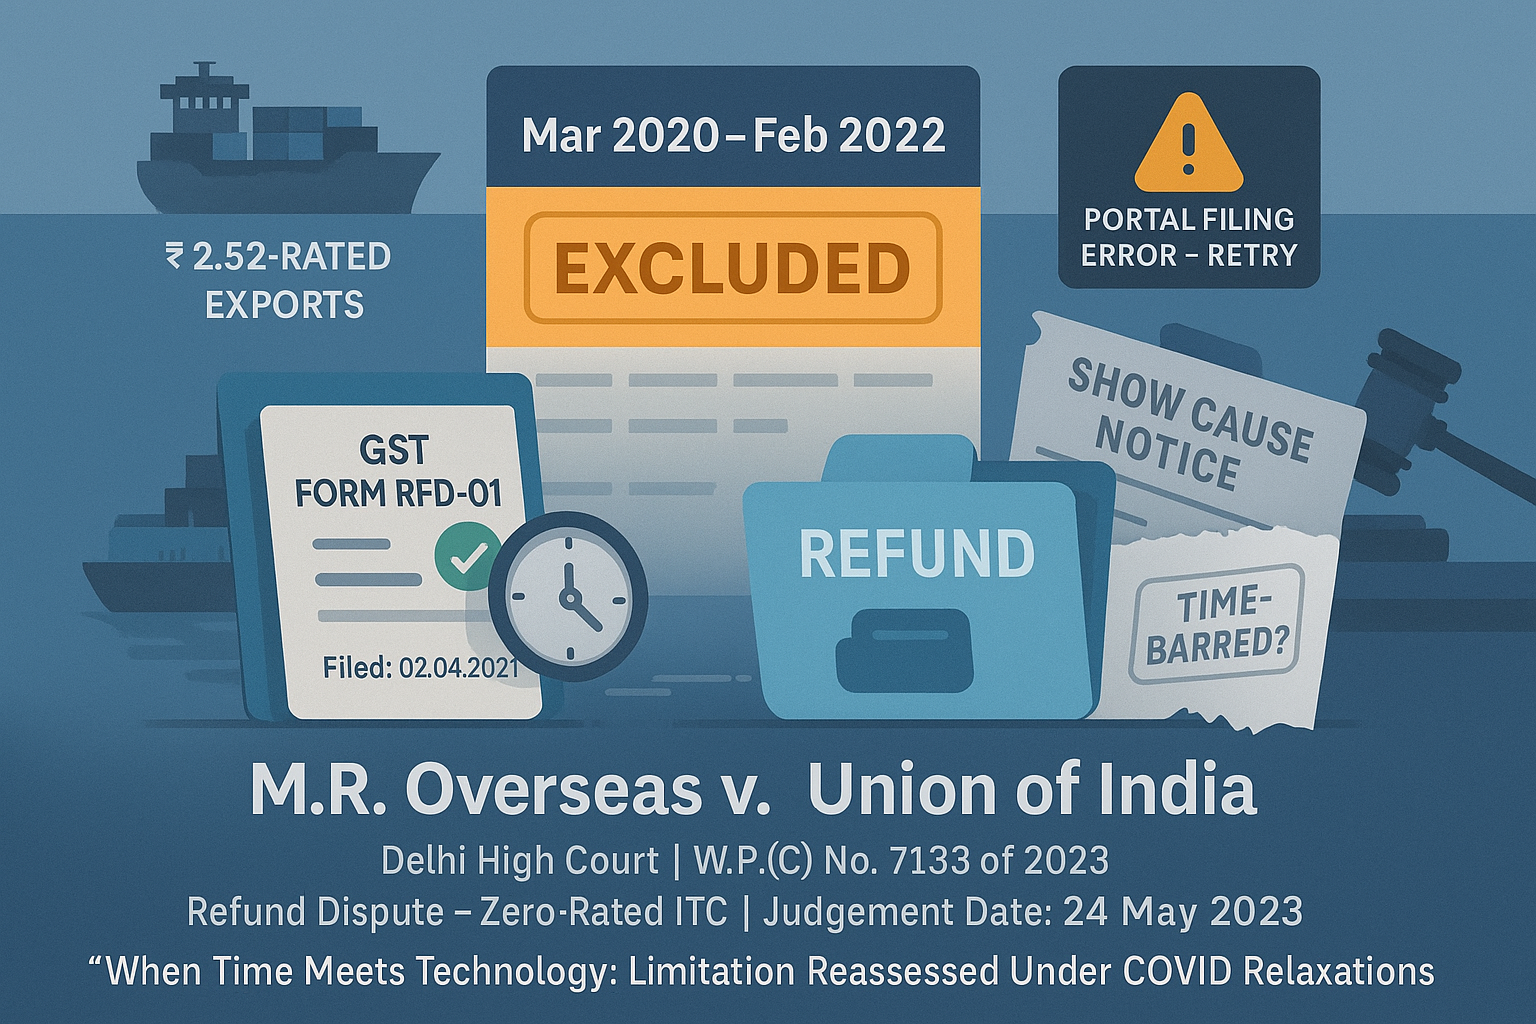
Case Title: M.R. Overseas v. Union of India
Court: High Court of Delhi
Petition No.: W.P.(C) No. 7133 of 2023; CM APPL. No. 27802 of 2023
Date of Judgment: 24 May 2023
Category of Dispute: Refund – Input Tax Credit (ITC) on Zero-Rated Supply
Relevant Sections: Section 54 of the CGST Act, 2017; Notification No. 13/2022-Central Tax dated 05.07.2022
Coram: Vibhu Bakhru and Amit Mahajan, JJ.
Facts of the Case
[Para 1–2]:
The petitioner, M.R. Overseas, supplied goods worth ₹2,52,22,834 to SEZ units during August 2017 to March 2018 without payment of IGST, qualifying as zero-rated supplies under GST.
[Para 2]:
The petitioner tried to file a refund claim for the Input Tax Credit (ITC) multiple times between 14.08.2020 and 02.04.2021 but faced technical issues. Ultimately, it filed the refund application (Form RFD-01) on 02.04.2021.
[Para 3]:
A show cause notice was issued on 13.05.2021 alleging the refund claim was time-barred under Section 54(1) of the CGST Act. The petitioner’s plea for delay condonation due to COVID-19 was not entertained.
[Para 3–4]:
The Adjudicating Authority and subsequently the Appellate Authority rejected the refund claim for ₹13,43,719, citing limitation.
Question(s) in Consideration
[Para 6–7]:
- Whether the refund application filed on 02.04.2021 is time-barred under Section 54 of the CGST Act?
- Whether Notification No. 13/2022-Central Tax, which excludes the period from 01.03.2020 to 28.02.2022 from limitation due to COVID-19, is applicable in this case?
- Whether the authorities failed to consider the petitioner’s plea for condonation of delay?
Observation of Court
[Para 8]:
The Court noted that both the Adjudicating and Appellate Authorities failed to consider the implications of Notification No. 13/2022 and the petitioner’s claim for condonation of delay due to COVID-19.
It observed that if the exclusion period (01.03.2020 to 28.02.2022) is applied, then at least part of the refund (February–March 2018) may fall within the limitation period.
Judgment of the Court
[Para 9]:
The High Court set aside the orders dated 26.05.2021 and 25.02.2022 and remanded the matter back to the Adjudicating Authority to reconsider the refund claim in light of the CBIC Notification No. 13/2022 dated 05.07.2022.
The writ petition was allowed accordingly.
Between Fine Lines
- The High Court allowed benefit of COVID-19-related relaxation in limitation for GST refund applications.
- Refund claims rejected purely on limitation must consider special notifications and pandemic impact.
- Technical glitches and lockdown-era delays may justify condonation.
- Authorities are duty-bound to evaluate such pleas before rejecting on limitation.
- The matter was remanded for fresh consideration, not a direct grant of refund.
Summary of Referred Cases
| Name | Citation | Summary | Verdict |
| None explicitly cited | — | The case turned on statutory interpretation and application of CBIC Notification No. 13/2022; no other judicial precedents were cited or relied upon. | — |
Takeaway:
“When Time Meets Technology: Limitation Reassessed Under COVID Relaxations”



