
Case Summary
Case: Tulip Turnomatic through its partner Neel Kothiya v. Commissioner of Customs
Court: High Court of Gujarat at Ahmedabad
Petition No.: R/Special Civil Application No. 21663 of 2023
Judgment Date: 20/12/2024
Category of Dispute: Refund of IGST on export (Zero-rated supply)
Relevant Sections: Section 16(3)(b) of the IGST Act, Section 54 of the CGST Act, Rule 96 of the CGST Rules, Section 149 of the Customs Act
Facts (Paras 4–11)
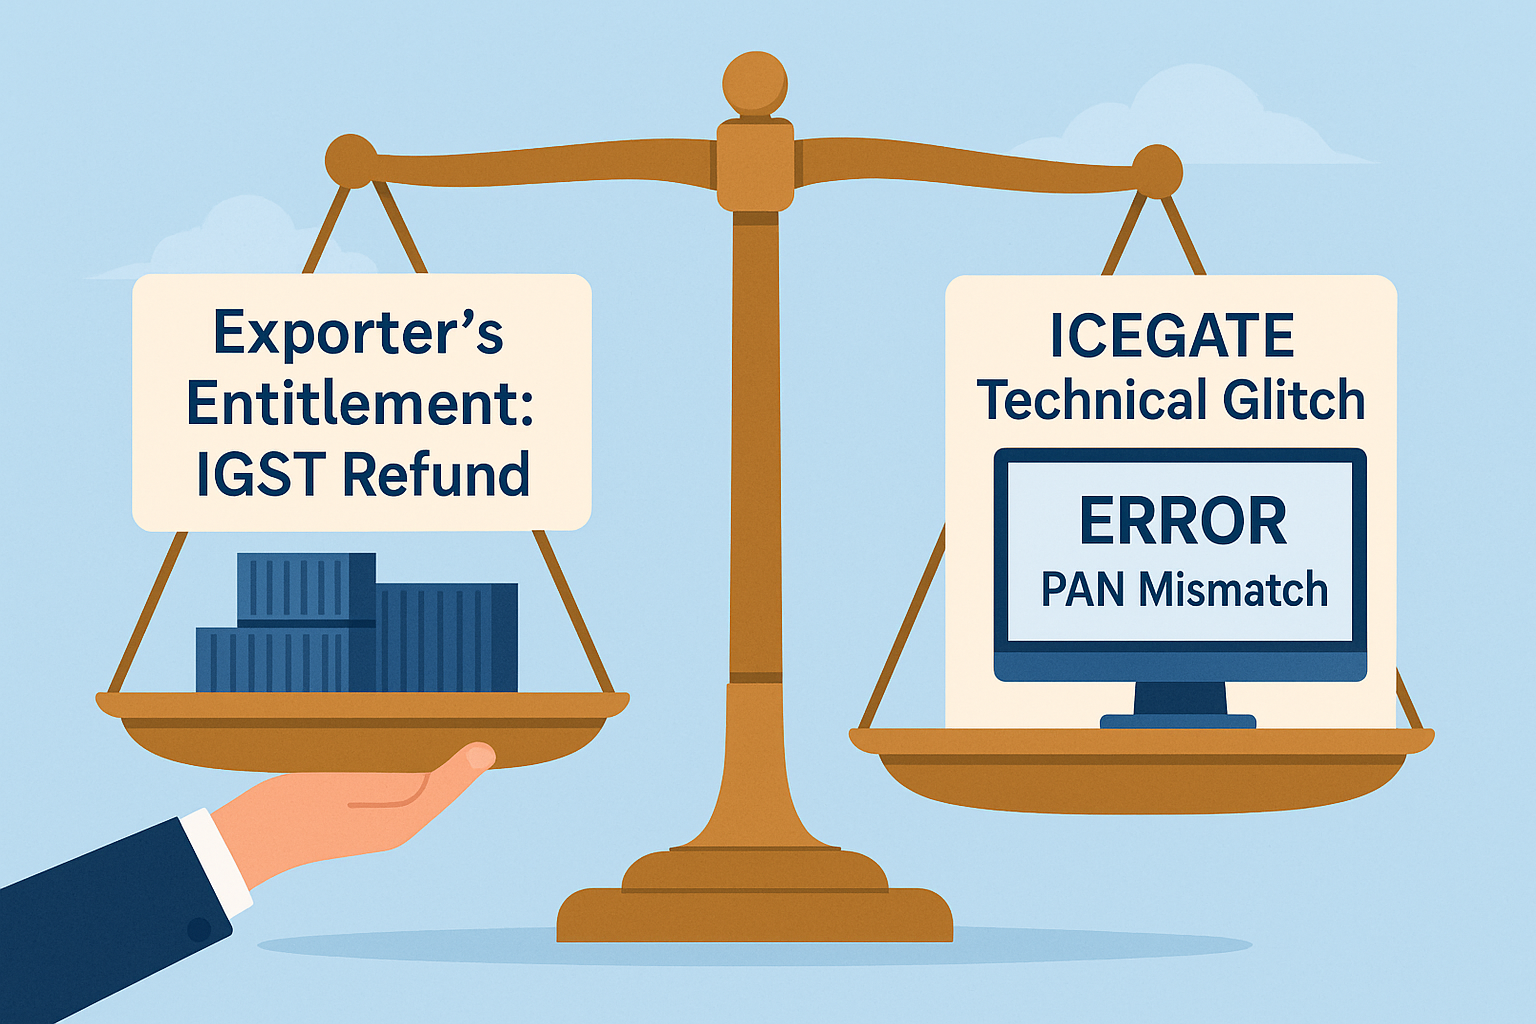
The petitioner, a partnership firm engaged in manufacturing and exporting brass parts, exported goods in February 2023 worth ₹1.15 crores and paid IGST of ₹17.57 lakhs. As per Section 16 of the IGST Act and Rule 96 of the CGST Rules, the shipping bill itself constituted an application for refund. Despite filing valid GSTR-1 and GSTR-3B returns, the refund was denied due to error code “SB003”. The error arose because the Custom House Agent inadvertently mentioned the IEC and GSTIN of the old firm (Tulip Turnomatic) which was later corrected through an amendment under Section 149 of the Customs Act. Even after amendment, ICEGATE continued to show mismatch in PAN between shipping bill GSTIN and GST returns, preventing auto-sanction of refund.
Questions before the Court
-
Whether refund of IGST on zero-rated exports can be denied merely due to PAN mismatch arising from a technical glitch?
-
Whether the Customs and GST authorities were duty-bound to give effect to the amendment order passed under Section 149 of the Customs Act?
Observations (Paras 12–18)
The Court noted that the petitioner had duly complied with GST provisions and rectified the mistake via amendment of the shipping bill approved by Customs. The refund mechanism under Rule 96 was intended to be automatic, but due to system mismatch, it became impossible to process. The Court observed that the petitioner became a “victim of computer software” since ICEGATE lacked a mechanism to reflect the amendment despite a lawful order under Section 149. Denial of refund on this ground was unjust, as statutory entitlements cannot be defeated by technological limitations.
Judgment (Paras 19–20)
The High Court directed the Customs and GST authorities to make suitable amendments in their systems to give effect to the order dated 21.04.2023 (amendment of shipping bill) and sanction the refund of IGST within eight weeks. The petition was allowed to this extent, and Rule made absolute.
Table of Cases Referred
| Case | Verdict / Relevance |
|---|---|
| Circular No. 15/2018-Customs (CBIC) | Relied upon by petitioner to show that refund should be granted even if errors occur, once corrections are approved under Customs law. |
(No judicial precedents cited beyond statutory circular reliance.)
Between Fine Lines
This ruling underscores that exporters cannot be denied legitimate IGST refunds merely because of ICEGATE software limitations. If an amendment is validly approved under Customs law, authorities must ensure backend systems are updated to reflect such changes. For trade, the key takeaway is that courts will protect refund entitlements where procedural or technical hurdles obstruct automatic processing.
Disclaimer – “The above summary is for academic purpose only; not formal legal opinion. Seek professional opinion before application. Author or publisher or website shall not be responsible for any usage in any form.”



