
Case Title: M/s Jitu Enterprises and Sounds Service v. Union of India
Court: Gauhati High Court
Petition No.: WP(C)/1258/2025
Category: Interest Demand – Installment Payment under Section 80
Date of Judgment: 06.05.2025
Relevant Sections: Section 50(1), Section 74(5), Section 80 of CGST Act; Rule 158 of CGST Rules
Issue: Rejection of request for 48 installments to pay interest and ITC-related dues
Facts of the Case
[Para 3–10]
The petitioner, M/s Jitu Enterprises and Sounds Service, a registered GST firm engaged in housekeeping services, received notices from the CGST Department regarding delayed filing of GSTR-3B returns and ineligible ITC due to belated filing.
-
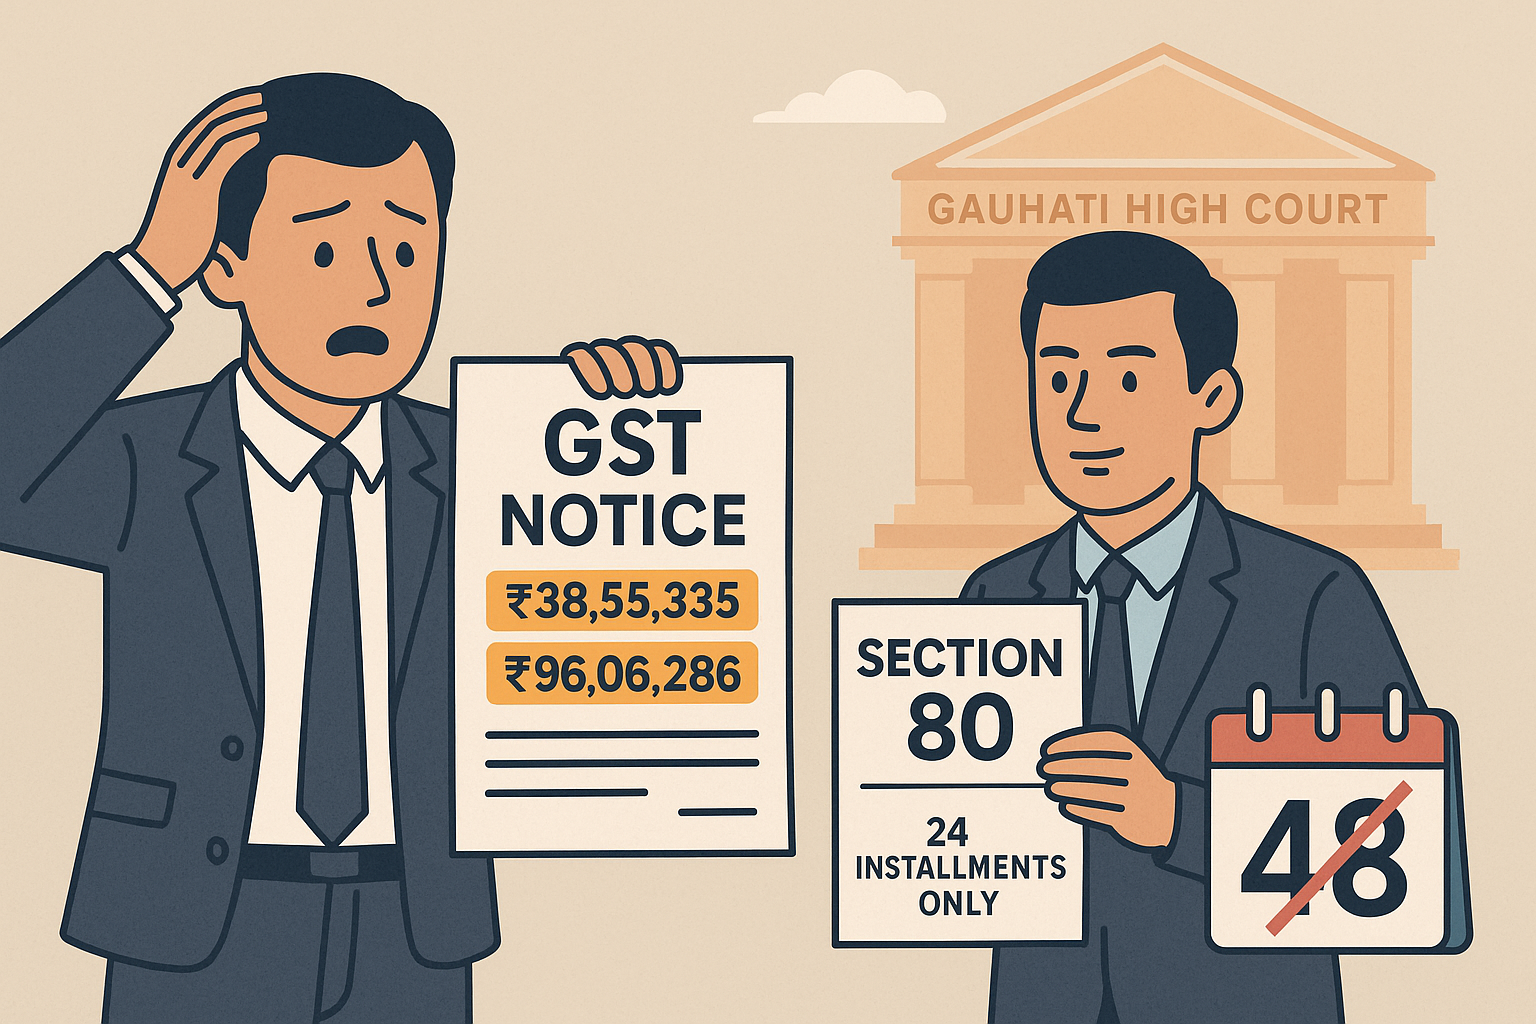
A notice dated 26.10.2023 was issued under Form ASMT-10 alleging late filing of returns for FY 2018–19, attracting interest of ₹38,55,335 and late fees of ₹1,13,850 under Sections 50 and 47 respectively.
-
A subsequent notice in Form DRC-01A dated 29.11.2023 alleged ineligible ITC of ₹8,79,904 and interest liability of ₹1,24,06,286.
-
The petitioner requested payment of ₹96,06,286 in 48 installments. However, the request was rejected stating it was against Section 80 of the CGST Act.
Questions in Consideration
[Paras 11–13]
-
Whether the Commissioner was right in rejecting the request to allow payment of interest in 48 equal monthly installments?
-
Whether the petitioner is entitled to any relief from the Court in terms of installment facility under Section 80 of the CGST Act despite rejection?
Observation of the Court
[Paras 11–15]
-
Section 80 of the CGST Act only permits installment payments up to 24 months for dues other than self-assessed liabilities.
-
The petitioner’s dues pertained to self-assessed liabilities, hence not eligible for installment facility under Section 80 as per law.
-
Rule 158 of CGST Rules outlines procedures and limitations for granting installment facilities, which must be strictly followed.
-
The Court observed that no mandamus can be issued to override the statutory limit of 24 installments under Section 80.
Judgment of the Court
[Para 16–17]
The writ petition was disposed of with the liberty to the petitioner to file a fresh application within 3 weeks seeking payment in 24 equal monthly installments. The Commissioner was directed to consider such application under Section 80 read with Rule 158 of CGST Rules and issue an order preferably within one month.
Between Fine Lines (Simple Summary)
-
Taxpayers can only seek installment facility up to 24 months for non-self-assessed dues.
-
Self-assessed interest liabilities in returns are not eligible for installments under Section 80.
-
Court refused to allow installments beyond 24 months.
-
Liberty granted to petitioner to reapply within statutory limit.
-
Authorities to decide the fresh application expeditiously.
Summary of Referred Cases
| Name | Citation | Summary | Verdict |
|---|---|---|---|
| No external precedents | — | Only statutory provisions discussed (Section 80, Rule 158) | Reiterated strict adherence to Section 80 limits |
Disclaimer – “The above summary is for academic purpose only; not formal legal opinion. Seek professional opinion before application. Author or publisher or website shall not be responsible for any usage in any form.”



