
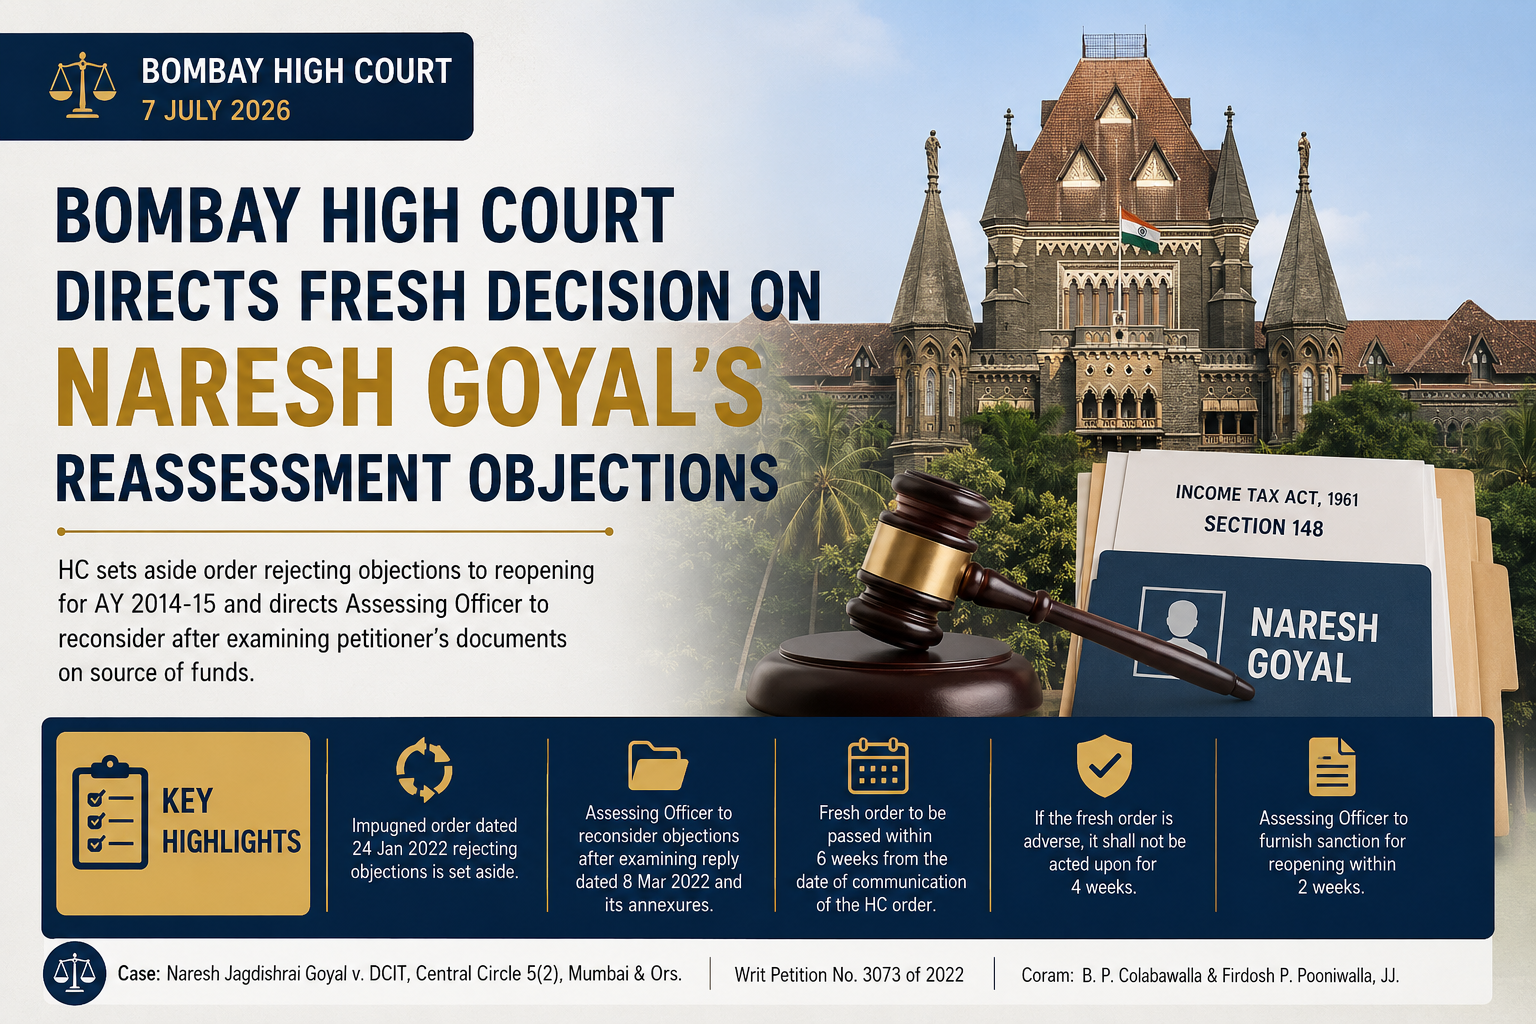
The Bombay High Court, in Naresh Jagdishrai Goyal v. Deputy Commissioner of Income-tax, Central Circle 5(2), Mumbai and Others, has set aside an order rejecting the petitioner’s objections to reopening of assessment for Assessment Year 2014-15. The Court directed the Assessing Officer to reconsider the objections after examining the petitioner’s subsequent response and supporting documents explaining the source of funds used for purchasing shares of Jet Airways (India) Limited.
The judgment was delivered on 7 July 2026 by a Division Bench comprising Justice B. P. Colabawalla and Justice Firdosh P. Pooniwalla in Writ Petition No. 3073 of 2022.
Background of the Dispute
The petitioner challenged a notice dated 31 March 2021 issued under Section 148 of the Income-tax Act, 1961, as well as the order dated 24 January 2022 by which his objections to reopening were rejected.
The reassessment proceedings arose from information received by the Assessing Officer from the Deputy Commissioner of Income-tax (International Taxation), Mumbai, concerning transactions undertaken by Tail Winds Limited, a foreign company incorporated in the Isle of Man.
According to the recorded reasons, Tail Winds Limited had sold shares of Jet Airways (India) Limited for approximately ₹3,563.49 crore during the relevant financial year. The information available with the tax department indicated that Tail Winds Limited was held by the petitioner and that he was also one of its directors.
The Assessing Officer recorded that the petitioner had purchased shares of Jet Airways from Tail Winds Limited and that the nature and source of the funds used for the purchase were not reflected in his return of income. On this basis, the Assessing Officer formed the belief that income chargeable to tax had escaped assessment.
Petitioner’s Explanation Regarding Source of Funds
In his objections dated 11 January 2022, the petitioner disputed the factual basis of the reopening and contended that the belief regarding escapement of income was based on borrowed satisfaction.
The petitioner stated that he had acquired 5,79,23,670 shares of Jet Airways from Tail Winds Limited and not 6,90,57,210 shares, as referred to in the reasons recorded for reopening.
He explained that the acquisition was funded in different tranches. The first tranche was funded through a short-term loan obtained from HSBC Geneva. After Tail Winds Limited received the sale consideration, it declared a dividend, which was used by the petitioner to repay the loan.
A similar arrangement was followed for the second tranche. The third tranche was stated to have been funded from the petitioner’s own resources. The petitioner claimed that the aggregate dividend received from Tail Winds Limited exceeded the consideration paid for the shares because Tail Winds Limited had also sold certain shares to members of the public.
The Assessing Officer rejected the objections, observing that the petitioner’s claims required verification during the reassessment proceedings and that no supporting proof had been submitted along with the objections.
Supporting Documents Filed During Reassessment Proceedings
Before the order disposing of the objections was passed, the Assessing Officer had already issued a notice under Section 143(2) of the Income-tax Act. A notice under Section 142(1) was also subsequently issued.
In response to these notices, the petitioner submitted a detailed reply dated 8 March 2022 along with documents which, according to him, established that the purchase of the Jet Airways shares was funded through loans obtained from HSBC Geneva and from his own funds.
The petitioner argued that the supporting material demonstrated the source of funds and was directly relevant to the question whether the Assessing Officer could validly form a belief that income had escaped assessment.
Bombay High Court’s Findings
The High Court observed that the principal challenge raised by the petitioner was that the Assessing Officer could not have had a valid reason to believe that income had escaped assessment.
The Court noted that, at the stage when the original order rejecting the objections was passed, the Assessing Officer could not prima facie be faulted for stating that the petitioner’s assertions required verification, as documentary evidence had not been placed before him along with the objections.
However, the Court also took note of the petitioner’s detailed response dated 8 March 2022 and the documents annexed to it. These materials were stated to contain evidence regarding the source of funds used for acquiring the shares.
Considering the peculiar factual circumstances, the Court held that the interests of justice would be served by directing the Assessing Officer to reconsider the petitioner’s objections after taking the subsequent response and its annexures into account.
Impugned Order Set Aside
The Bombay High Court quashed the order dated 24 January 2022 by which the petitioner’s objections to reopening had been rejected.
The Assessing Officer was directed to pass a fresh order disposing of the objections after considering the petitioner’s letter dated 8 March 2022 and the documents annexed to it.
The fresh order is required to be passed within six weeks from the date on which the High Court’s order is communicated to the Assessing Officer.
Four-Week Protection Against Adverse Order
The Court further directed that, in case the fresh order disposing of the objections is adverse to the petitioner, it shall not be acted upon for a period of four weeks.
This protection enables the petitioner to approach the High Court again in its writ jurisdiction if he remains aggrieved by the fresh decision.
Reassessment Sanction to Be Furnished
The High Court also directed the Assessing Officer to furnish the sanction obtained for reopening the assessment to the petitioner within two weeks from the date of communication of the order.
The Court clarified that it had not expressed any opinion on the merits of the petitioner’s objections. All contentions of both parties were expressly kept open for consideration by the Assessing Officer while passing the fresh order.
Key Legal Principle
The judgment reinforces that an order disposing of objections to reassessment must consider all material documents that have a direct bearing on the recorded belief of escapement of income, particularly where such documents are already available with the Assessing Officer before the reassessment proceedings progress further.
Although the Court did not decide the validity of the reopening on merits, it ensured that the petitioner’s documentary explanation regarding the source of funds would be examined before a fresh decision on the objections is taken.
Conclusion
The Bombay High Court allowed the writ petition to the limited extent of setting aside the order rejecting the petitioner’s objections. The Assessing Officer must now reconsider the objections after examining the petitioner’s response dated 8 March 2022 and the supporting documents concerning the funding of the Jet Airways share acquisition.
The ruling does not invalidate the reassessment notice itself and does not determine whether any income had escaped assessment. The validity of the petitioner’s objections and the source-of-funds explanation remain open for fresh consideration by the Assessing Officer.



