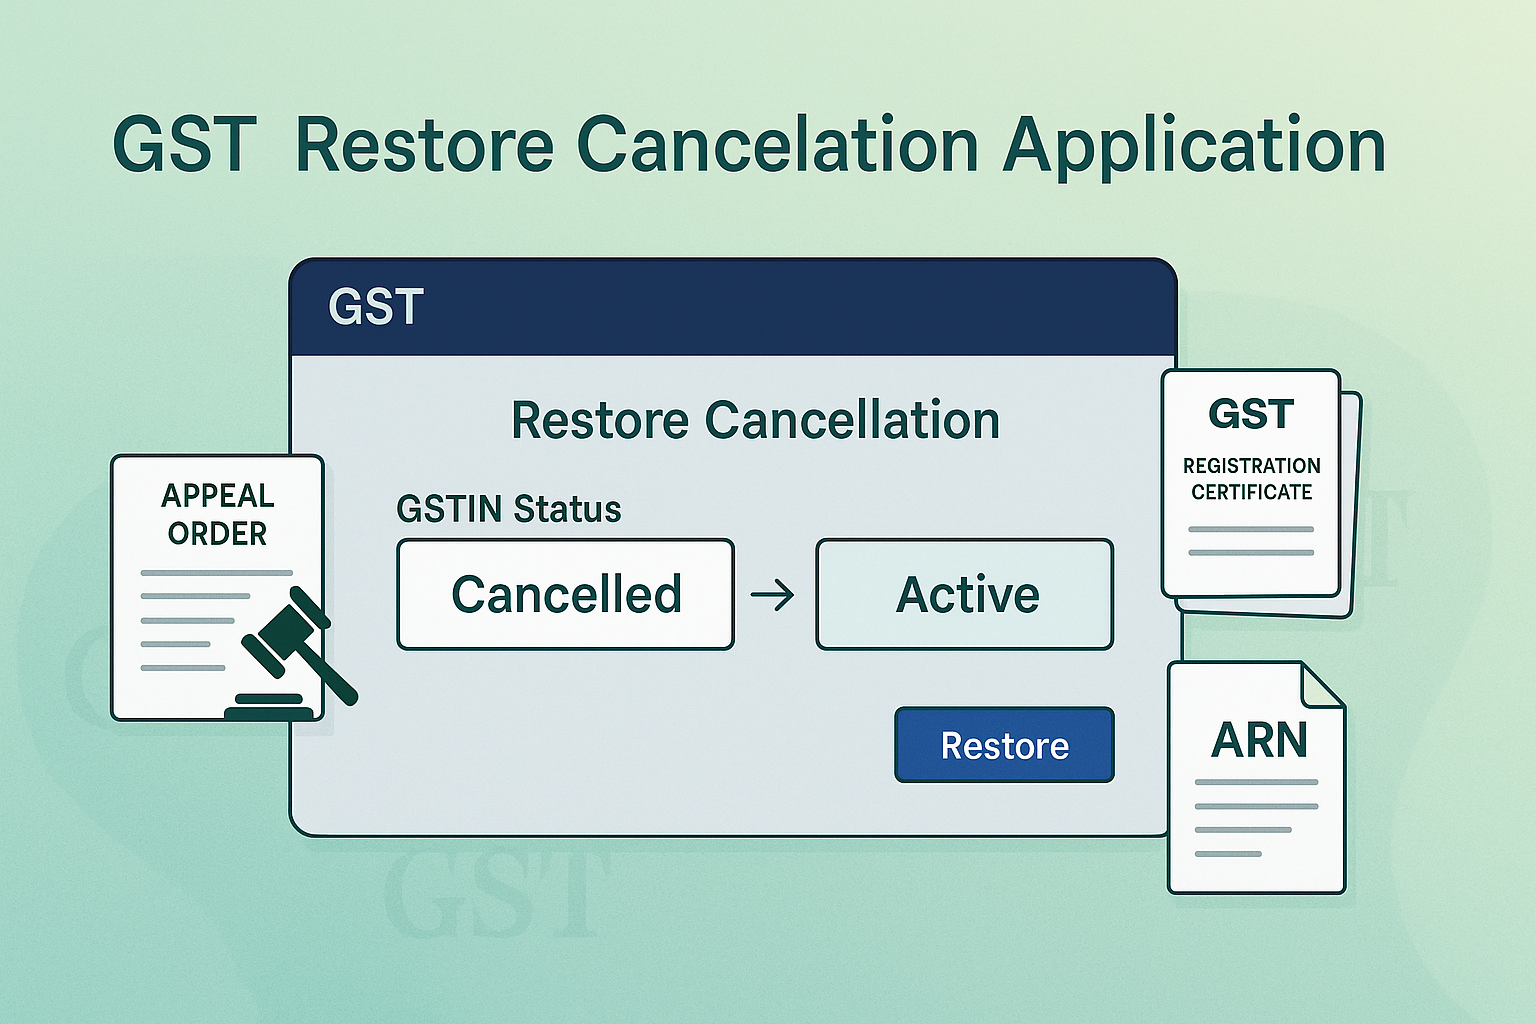
Restore Cancellation Application
Edition: September 2025
Disclaimer: This manual is for compliance facilitation. It does not substitute statutory provisions, notifications, or circulars. Taxpayers must verify with the CGST/SGST Acts, Rules, and GSTN updates.
✍️ Preface
If a taxpayer’s GST registration is cancelled by the Tax Officer, it may be restored when the taxpayer files an appeal and the Appellate Authority passes an order in their favor. Restoration reactivates the GSTIN and allows the taxpayer to resume compliance.
This manual consolidates the law, restoration process, timelines, FAQs with statutory basis, and a compliance checklist.
📑 Table of Contents
-
Law Governing Restoration of Cancellation
-
When Can Restoration Be Granted?
-
Step-by-Step Process
-
Effective Date of Restoration
-
Effect After Restoration
-
FAQs (with Basis)
-
Compliance Checklist (Fillable Format)
⚖️ 1. Law Governing Restoration of Cancellation
-
Section 30 & 107, CGST Act, 2017 – Revocation of cancellation and appeals.
-
Rule 23, CGST Rules, 2017 – Revocation and restoration procedures.
-
GSTN FAQs & User Guides – Define process for restoration after appellate approval.
📌 2. When Can Restoration Be Granted?
-
When GSTIN was cancelled by officer.
-
Taxpayer filed an appeal within statutory period.
-
Appellate Authority issued an order in favor of taxpayer.
-
Even possible if Final Return (GSTR-10) had already been filed, provided higher authority orders restoration.
🛠️ 3. Step-by-Step Process
-
Appeal Filing: Taxpayer files appeal against cancellation order.
-
Appellate Order: If order favors taxpayer, it is communicated to Proper Officer.
-
Officer Action:
-
Officer restores GSTIN on GST Portal.
-
Order of restoration uploaded.
-
-
Communication:
-
Taxpayer receives SMS & Email.
-
Registration Certificate available for view/download on dashboard.
-
📌 4. Effective Date of Restoration
-
Effective date = date mentioned in cancellation order by Tax Officer.
📌 5. Effect After Restoration
-
GSTIN status changes from “Cancelled” to “Active”.
-
Registration Certificate becomes available.
-
Taxpayer resumes normal compliance (returns, ITC, invoices, etc.).
❓ 6. FAQs (with Basis)
Q1. Can Tax Officer restore GSTIN?
Yes, if appeal decided in taxpayer’s favor. (FAQ 1)
Q2. Is there a time limit for officer to restore?
No statutory time limit. (FAQ 2)
Q3. What is effective date of restoration?
Date in original cancellation order. (FAQ 3)
Q4. What happens after restoration?
GSTIN reactivated, RC available, ARN issued, communicated via SMS/email. (FAQ 4)
Q5. Can restoration happen if Final Return filed?
Yes, if appellate/higher authority orders. (FAQ 5)
✅ 7. Compliance Checklist (Fillable Format)
| Step | Particulars | Status (✔) |
|---|---|---|
| 1 | File appeal against cancellation order | ⬜ |
| 2 | Receive favorable appellate order | ⬜ |
| 3 | Officer restores GSTIN on portal | ⬜ |
| 4 | Save restoration order (download) | ⬜ |
| 5 | Confirm GSTIN status = Active | ⬜ |
| 6 | Resume filing of returns & compliance | ⬜ |