
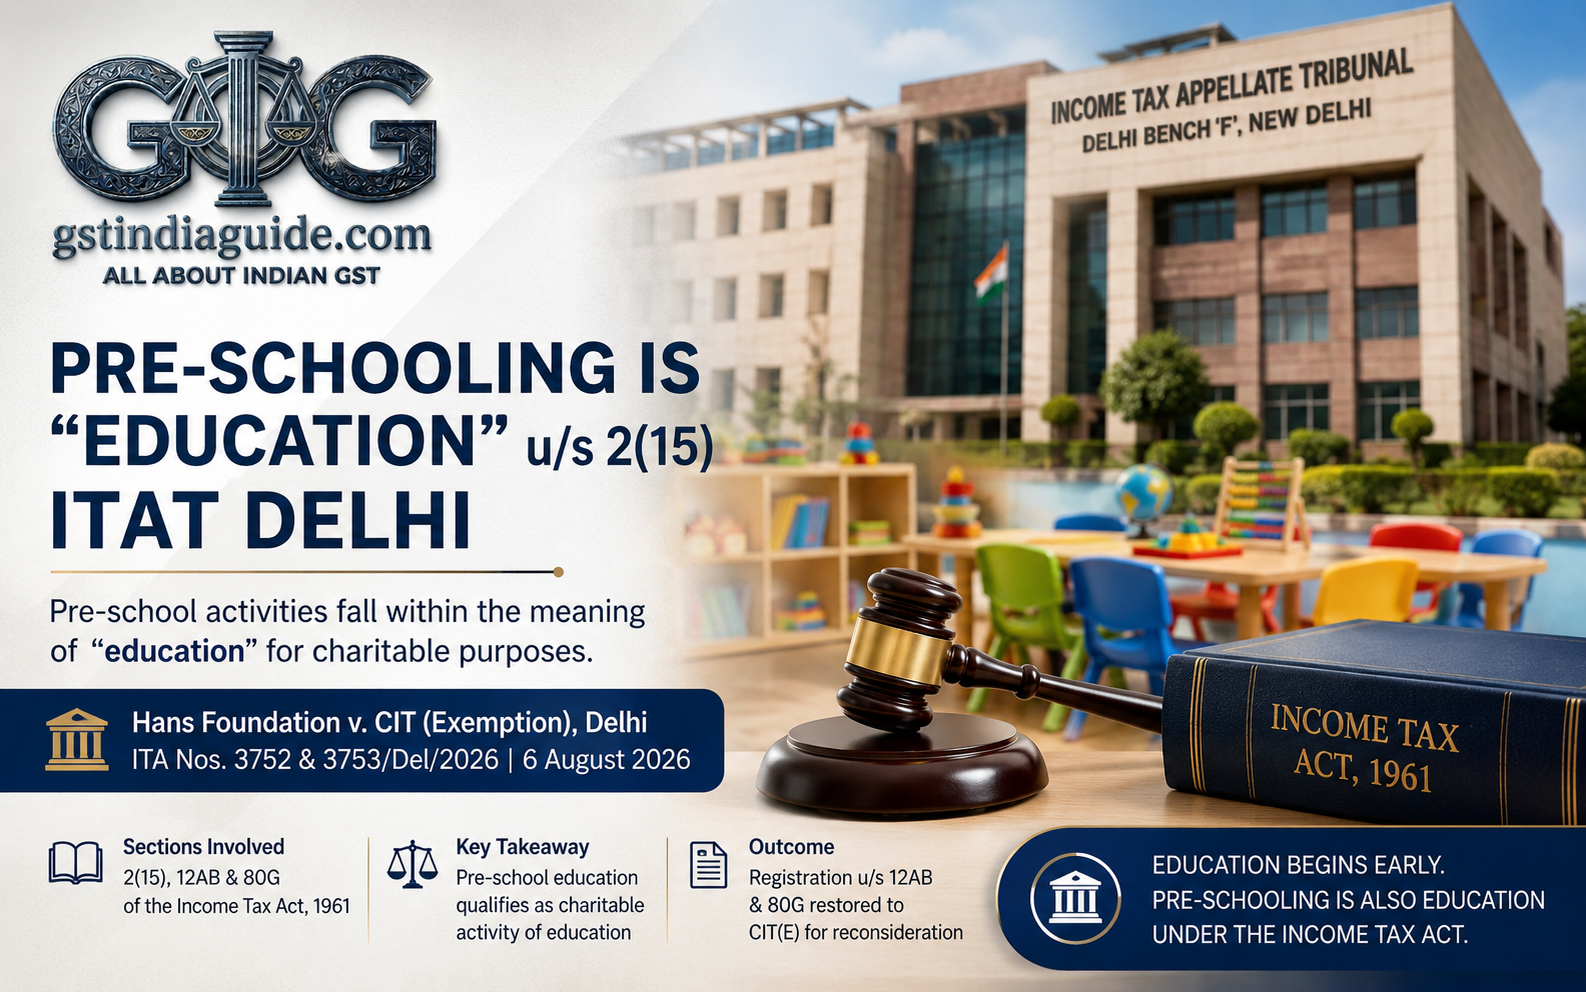
The Delhi Bench of the Income Tax Appellate Tribunal has held that pre-schooling falls within the meaning of “education” contemplated under Section 2(15) of the Income Tax Act, 1961. The Tribunal observed that running a play school or imparting primary-level education does not require affiliation with a competent authority merely for the activity to qualify as education for the purpose of charitable registration.
Hans Foundation had filed an application in Form 10AB seeking registration under Section 12A(1)(ac)(ii). The Commissioner of Income Tax (Exemption) rejected the application, principally observing that the assessee was running a community school which was not affiliated with a competent authority and that its activities did not satisfy the concept of systematic education contemplated under Section 2(15). The CIT(E) consequently also rejected the application under Section 80G.
Non-Affiliation Cannot by Itself Exclude Pre-Schooling from “Education”
Before the Tribunal, the assessee contended that it was running a preparatory school for children below the age of formal schooling and, therefore, absence of affiliation could not constitute a valid basis for denying registration. It was also argued that, at the registration stage, the CIT(E) was required to examine the charitable objects and genuineness of the activities.
The Tribunal found that the assessee was engaged in educational activities through a play school. It specifically observed that a play school or primary education does not require affiliation from a competent authority. The Bench relied upon the reasoning adopted by the Mumbai Bench of the Tribunal in Green Acres Educational Trusts v. Dy. CIT and also referred to the decision concerning Life Shines Educational & Charitable Trust.
The Tribunal endorsed the broader understanding that education is not confined only to conventional formal schooling. Pre-school education represents an early stage of the educational process and cannot be isolated from the wider meaning of education merely because it precedes formal school education.
Pre-Schooling Falls Within Section 2(15)
Following the earlier Tribunal decisions, the Delhi ITAT concluded that pre-schooling also falls within the meaning of imparting education. It therefore remitted the issue relating to registration under Section 12AB to the CIT(E) for reconsideration of the material facts on record, while observing that the assessee should be granted registration under the category of charitable activity of imparting education.
As the Section 80G application had been rejected on substantially the same basis, that issue was also restored to the CIT(E). The Tribunal directed the authority to consider the assessee’s submissions and grant registration under Section 80G after due verification in accordance with law. Both appeals of the assessee were allowed.
Key Legal Takeaway
The decision clarifies that the expression “education” under Section 2(15) should not be restricted only to institutions providing formally affiliated schooling. Pre-school or play-school activities can constitute education for charitable purposes. Consequently, absence of affiliation, by itself, cannot justify rejection of an application for registration under Section 12AB where the institution is genuinely engaged in imparting pre-school education.
The ruling is particularly relevant for charitable trusts and institutions operating pre-schools, preparatory schools and similar educational facilities while seeking registration under Sections 12AB and 80G.



. Rejection of Hans Foundation’s Section 12AB and 80G applications reconsidered.)