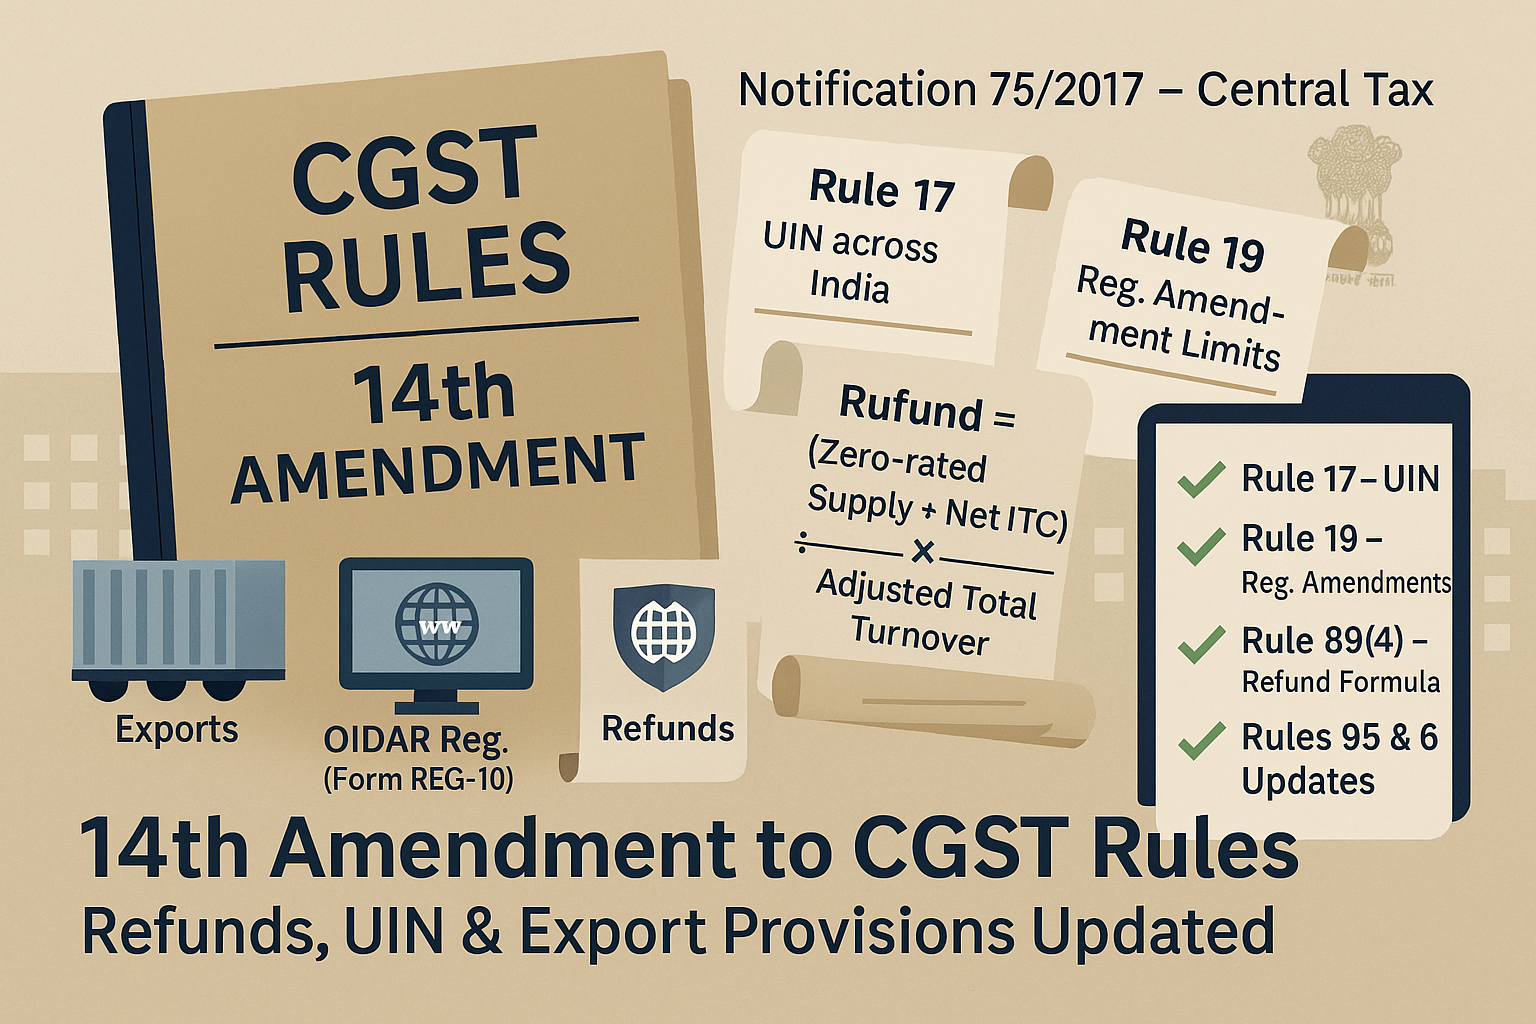
Notification No.: 75/2017 – Central Tax
Date of Notification: 29th December 2017
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 25(9)(a): Unique Identity Number (UIN)
- Section 16 of IGST Act (read with Rule 89): Refund on zero-rated supplies
- Section 55: Refund to specified agencies
- Section 164: Power to make rules
- CGST Rules, 2017 (Fourteenth Amendment): Rules 17, 19, 89, 95, 96, 14(1), 82, 95(1), Rule 142
- Supersedes/Amends: Notification No. 3/2017, 27/2017, and others referenced
- Integrated GST Act: Section 16 (Zero-rated supplies), Section 14 (OIDAR services)
Summary of Notification
- Territorial Scope of UIN (Rule 17):
Inserted sub-rule 17(1A) clarifies that the Unique Identity Number (UIN) granted to a person under Section 25(9)(a) will be valid throughout the territory of India, not restricted to any specific state or location. - Amendment to Registration Application (Rule 19):
Inserted Rule 19(1A) provides that any amendment in GST registration (via FORM GST REG-14) shall not take effect retrospectively unless specifically permitted by the Commissioner through an order stating reasons and conditions. - Refund Formula Updated (Rule 89(4)):
Revised the formula for refund of input tax credit on zero-rated supplies without payment of tax, introducing clarity in treatment of deemed exports and excluding supplies claimed under sub-rules (4A)/(4B). Also introduced:
- Rule 89(4A) & 89(4B): Specific refund provisions when the supplier has availed benefit of Notification 48/2017, 40/2017-CTR, or 41/2017-IGST.
- Quarterly Refund for Specified Agencies (Rule 95):
Updated Rule 95(1) to require eligible entities (e.g., embassies, UN agencies) to file refund claims quarterly via FORM GST RFD-10 and GSTR-11, electronically or otherwise. - Refund Restriction on Exporters (Rule 96):
Inserted Rule 96(9), disqualifying persons who have received supplies under Notification 48/2017, 40/2017-CTR, or 41/2017-IGST from claiming refund of IGST paid on exports. - Revised Registration Form for OIDAR Suppliers (REG-10):
Replaced FORM GST REG-10 for registration of OIDAR suppliers outside India supplying to unregistered persons in India, with enhanced identity and business proof requirements. - Revision to UIN Registration (REG-13) and Statement Filing (GSTR-11):
Updated FORM GST REG-13 and replaced FORM GSTR-11 to align with centralized UIN registration and ensure consistency in refund processing. - Revised Refund Application Form (GST RFD-10):
Replaced FORM GST RFD-10 for embassies and specified agencies, aligning with GSTR-11 and requiring bank and identification details for refund claim processing. - Omission in DRC-07:
Omitted Table at Serial No. 5 of FORM GST DRC-07, likely to simplify adjudication summary for demand orders.