Notification No.: 1/2019 – Central Tax
Date of Notification: 15th January 2019
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 147 – Deemed exports
- Amends: Notification No. 48/2017 – Central Tax dated 18th October 2017
- Integrated GST Act: Not applicable
Summary of Notification
- Additional Compliance Conditions for Deemed Exports with ITC Availment:
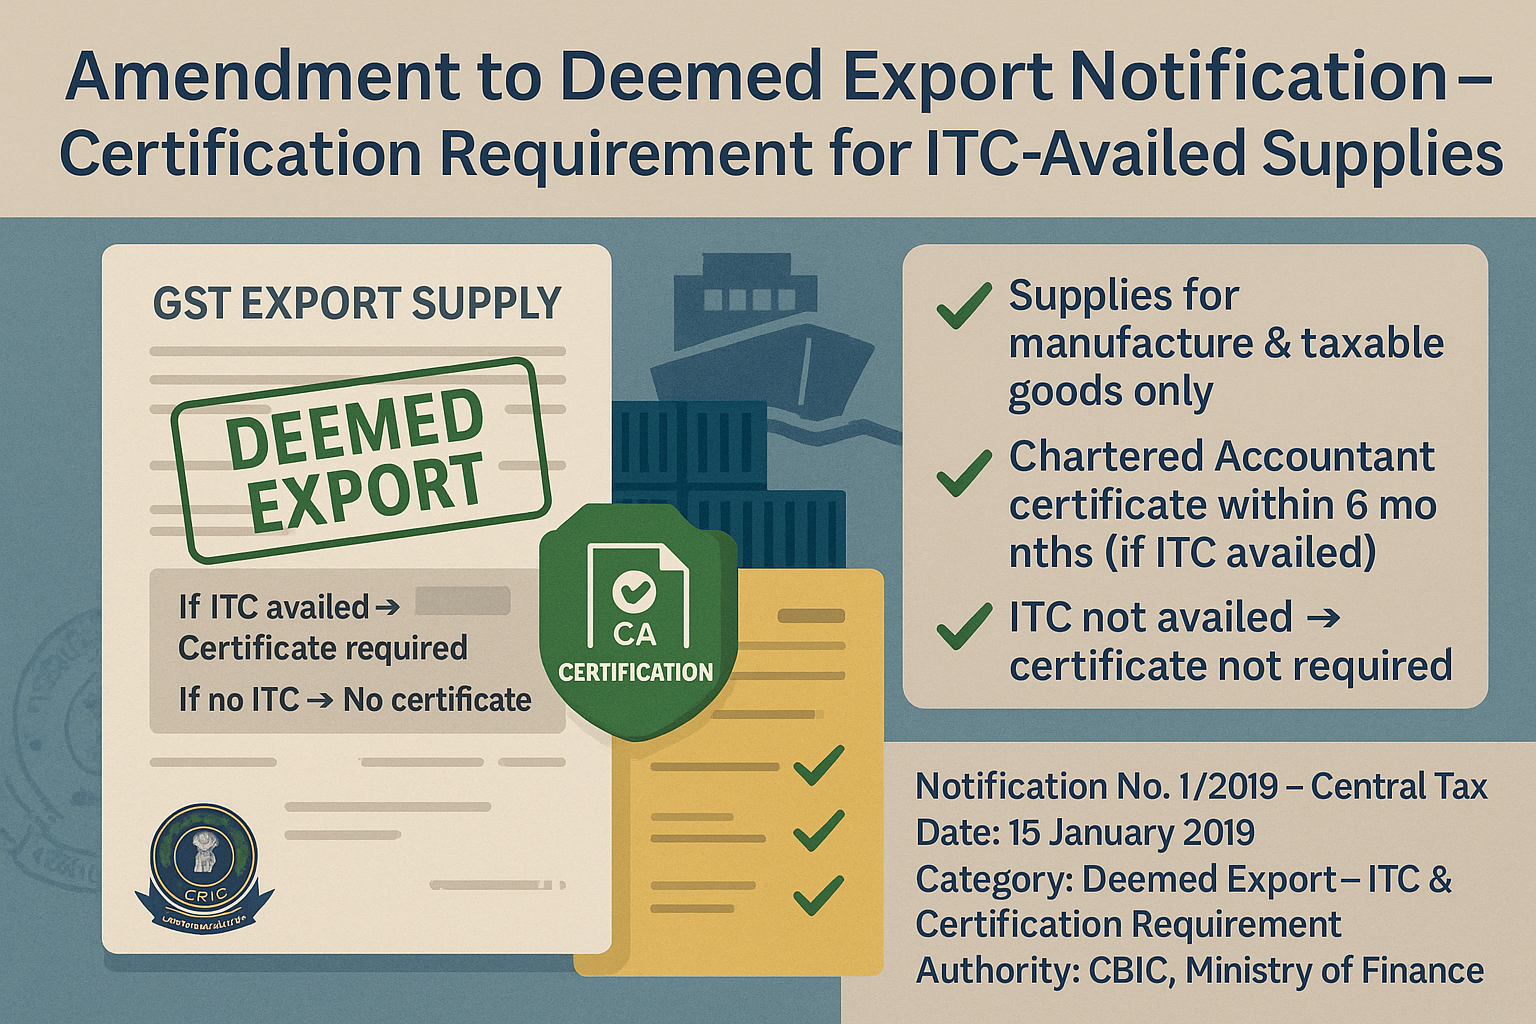
This notification introduces a proviso under S. No. 1 in the Table of Notification 48/2017-Central Tax. It mandates that in cases where exports have already been made by availing input tax credit (ITC) on inputs used in manufacture, the goods supplied under deemed export route must be used in manufacture and supply of taxable goods (excluding nil-rated or exempted goods).
Additionally, a Chartered Accountant’s certificate must be submitted to the jurisdictional GST Commissioner within 6 months from the date of such supply.
- Waiver of CA Certificate Requirement in Certain Cases:
The second proviso clarifies that if no ITC has been availed on inputs used for manufacturing export goods, then the requirement of CA certification is waived, easing compliance for such exporters. - Deletion of “Pre-Import Basis” Restriction:
The phrase “on pre-import basis” in the Explanation to S. No. 1 is omitted. This change removes the restriction that deemed export supplies must be used for goods imported prior to export, thereby relaxing sourcing conditions for exporters using the deemed export benefit.