
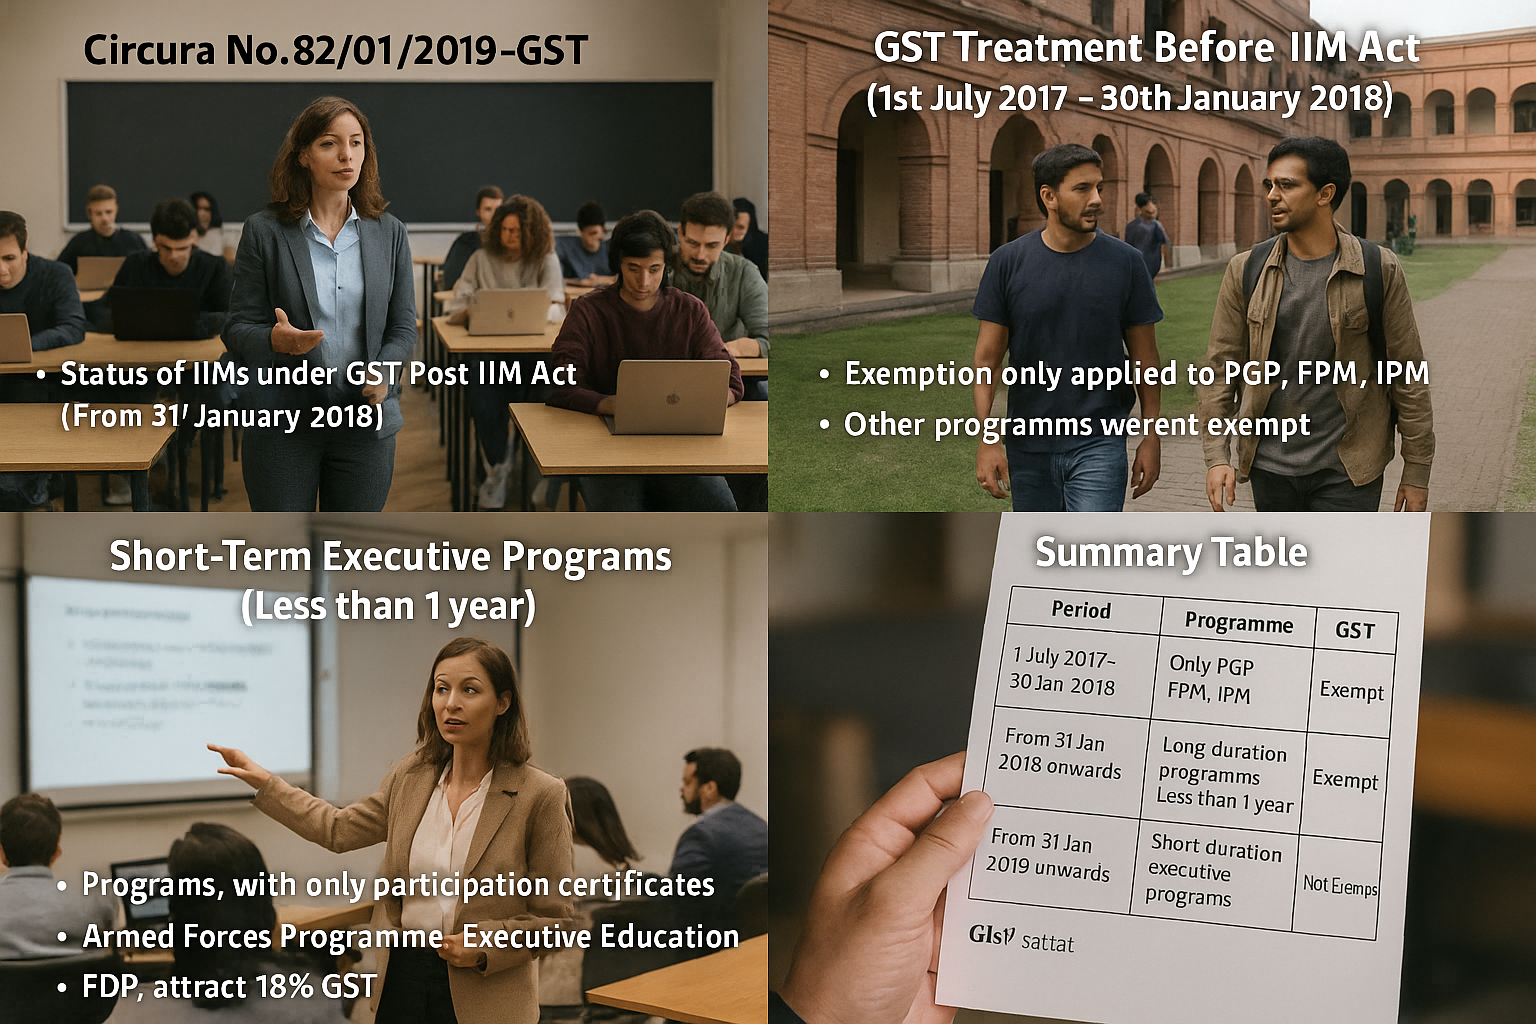
Circular No.: 82/01/2019-GST
Date of Circular: 1st January 2019
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 168(1): Power to issue instructions
- Notifications:
- Notification No. 12/2017-Central Tax (Rate) dated 28.06.2017
- Notification No. 28/2018-Central Tax (Rate) dated 31.12.2018
Summary of Circular:
This circular provides clarity on the applicability of GST on various academic programmes offered by Indian Institutes of Managements (IIMs), considering the IIM Act, 2017 which came into force on 31st January 2018.
- Status of IIMs under GST Post IIM Act (From 31st January 2018):
- All IIMs listed in the IIM Act are “educational institutions” under Notification No. 12/2017-CT(R) as they provide recognized degrees/diplomas.
- All long-duration programs (1 year or more) conferring degree/diploma (e.g., PGP, FPM, PGPX, ePGP) are exempt from GST under Sl. No. 66.
- GST Treatment Before IIM Act (1st July 2017 – 30th January 2018):
- IIMs were not considered educational institutions before 31.01.2018.
- Exemption applied only to:
- (i) 2-year full-time PGP (via CAT),
- (ii) Fellow Programme in Management (FPM),
- (iii) 5-year Integrated Programme in Management
– under Sl. No. 67 of Notification No. 12/2017-CT(R).
- Overlap Period (31st Jan 2018 to 31st Dec 2018):
- IIMs were eligible for both Sl. No. 66 and 67 exemptions.
- As per settled legal principles, IIMs can choose the more beneficial exemption.
- Sl. No. 67 was deleted w.e.f. 1st January 2019 by Notification No. 28/2018-CT(R).
- Short-Term Executive Programs (Less than 1 year):
- Programs awarding participation certificates (not recognized qualifications) are not exempt from GST.
- Such programs (e.g., Armed Forces Programme, Executive Education, FDP) attract 18% GST.
- Summary Table:
| Period | Programme Type | GST Status |
| 1 July 2017 – 30 Jan 2018 | Only PGP, FPM, IPM (as per Sl. No. 67) | Exempt |
| Other programs incl. executive short-term | Not Exempt | |
| From 31 Jan 2018 onwards | Long-duration programs under IIM Act | Exempt under Sl. No. 66 |
| Short-duration executive programs | Not Exempt |
- Applicability to SGST, IGST, UTGST:
- These clarifications apply mutatis mutandis to similar exemption entries in SGST, IGST, and UTGST rate notifications.
Source: Circular No.: 82/01/2019-GST



.)