Notification No.: 12/2024 – Central Tax
Date of Notification: 10th July 2024
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 25(6C) & (6D) – Aadhaar authentication for registration
- Section 39 – Furnishing of returns
- Section 54 – Refund of tax
- Section 55 – Refunds to certain persons (like Canteen Stores Department)
- Section 112 & 113 – Appeals to Appellate Tribunal
- Section 164 – Power of Government to make rules
- CGST Rules, 2017 (Amended):
- Rule 8(4A) – Aadhaar authentication, biometric/photo verification
- Rule 21 & 21A – Conditions for registration cancellation/suspension
- Rule 28(2) – Valuation of corporate guarantee (clarifications added)
- Rule 36, 37A, 39, 40, 48, 59, 60, 62, 78, 88B, 88C, 89, 95B (new), 96, 96A, 110–113A, 138, 142, 142B, 163 – Amended/inserted
- New forms introduced/amended: GSTR-1A, GSTR-2B (substituted), GSTR-9, GSTR-9C, GSTR-4, GSTR-5, GSTR-6A, GSTR-7, GSTR-8, RFD-10A, APL-05/07W, DRC-01A (revised), DRC-03A, DRC-04
Summary of Notification:
- Registration & Aadhaar Authentication:
- Applicants not opting for Aadhaar authentication must undergo photographing + document verification at facilitation centres before REG-01 is deemed complete.
- Rule 21 & 21A amended to expand grounds for cancellation/suspension based on discrepancies in GSTR-1 or new GSTR-1A.
- Corporate Guarantee Valuation (Rule 28):
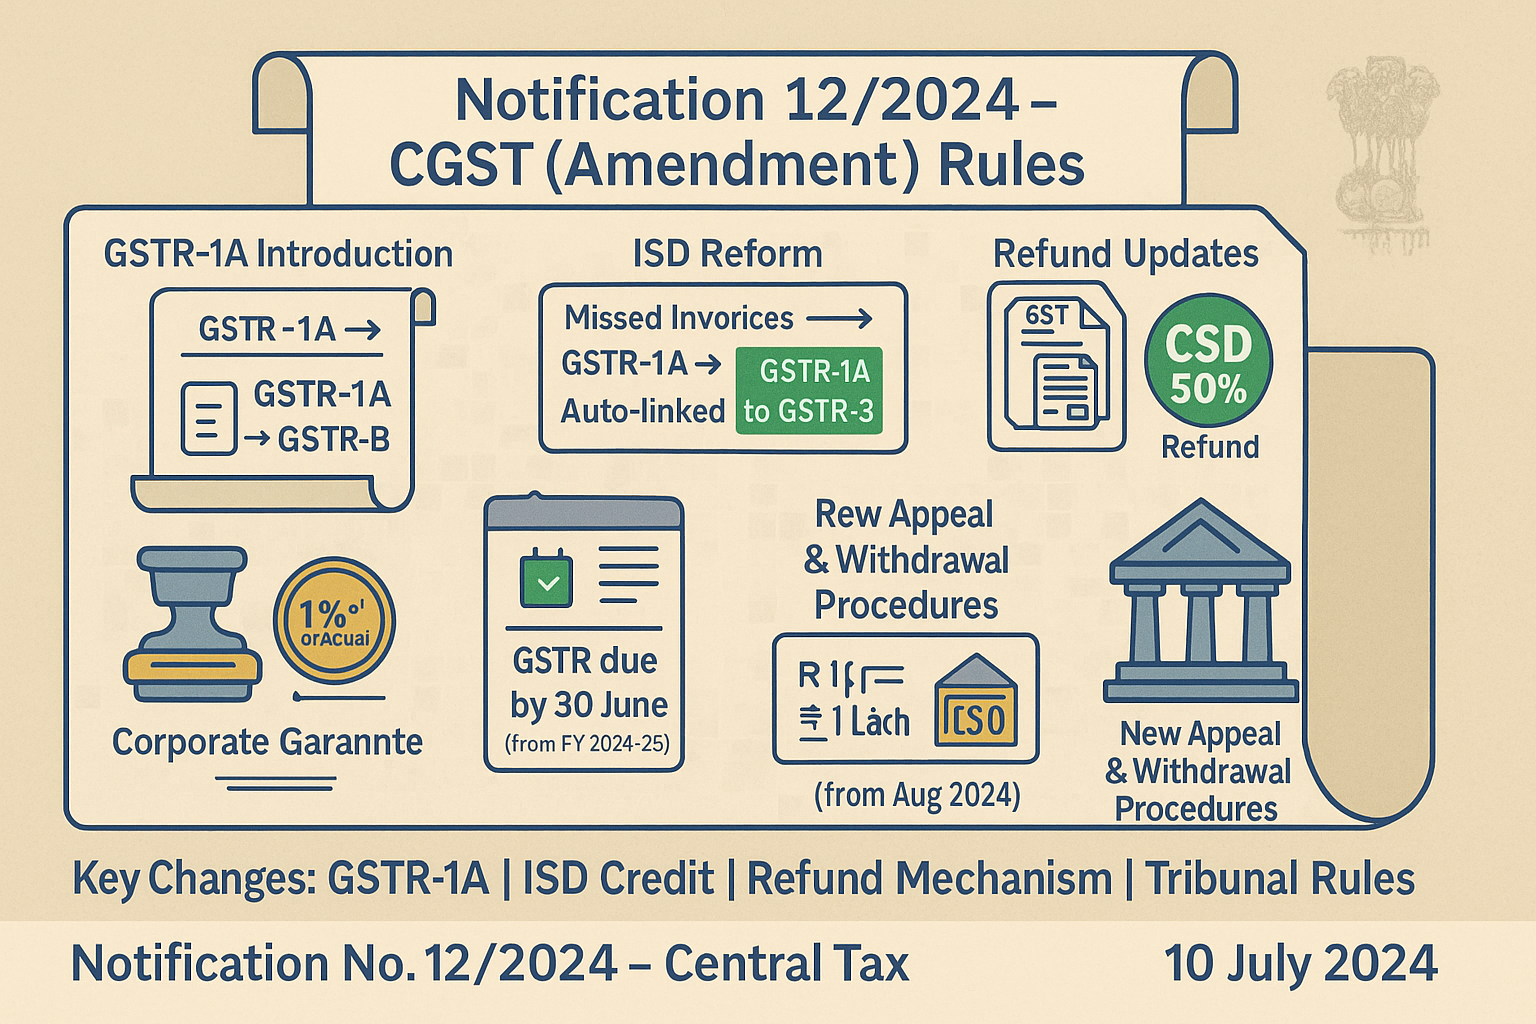
- Clarified that guarantee services between related parties located in India valued at 1% per annum of guarantee or actual amount, whichever higher.
- If recipient has full ITC, invoice value is deemed acceptable.
- Returns & Amendments:
- GSTR-1A introduced – allows amendment/addition of outward supplies after GSTR-1 filing but before GSTR-3B.
- Threshold for invoice-wise reporting reduced from ₹2.5 lakh to ₹1 lakh (effective 1st Aug 2024).
- GSTR-4 (composition return) to be filed by 30th June following FY (from FY 2024-25).
- Major changes in GSTR-5, GSTR-6A, GSTR-7, GSTR-8 for enhanced details.
- Input Service Distributor (Rule 39):
- Comprehensive substitution for distribution of ITC, introducing formula-based apportionment (C1 = t1/T × C).
- Introduces mechanism for transfer of common credits by distinct persons via invoice/credit note to ISD.
- Refunds:
- New Rule 95B & RFD-10A: Canteen Stores Department (CSD) can claim 50% refund of tax paid on inward supplies quarterly.
- Exporters allowed refund of additional IGST paid on upward price revision of exports through new Statements 9A & 9B in RFD-01.
- Appeals & Tribunal Procedures:
- New Rules 110–113A introduced for filing appeals/applications before the Appellate Tribunal.
- Filing primarily electronic (APL-05, APL-06, APL-07). Provisional acknowledgment issued on filing.
- Withdrawal of appeal/application permitted through APL-05/07W, subject to Tribunal approval if final acknowledgment already issued.
- Demand & Recovery:
- DRC-01A substituted to enhance intimation/submission process.
- DRC-03A introduced – allows adjustment of payments made via DRC-03 against demand orders.
- DRC-04 substituted – system-generated acknowledgment of voluntary payment.
- E-Way Bill & Unregistered Persons:
- New Form ENR-03 for unregistered persons to obtain enrolment number to generate e-way bills.
- Annual Returns (GSTR-9 & 9C):
- For FY 2023-24 onwards, new reporting requirements include supplies covered under Section 9(5) (ECO liable).
- Clarifications on ITC reversal/reclaim timelines extended till 30th Nov 2024.
- GSTR-9C instructions updated for FY 2023-24.