Notification No.: 56/2019 – Central Tax
Date of Notification: 14th November 2019
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 164 – Power to make rules
- CGST Rules, 2017:
- Rule 89 – Refunds
- Rule 61 – FORM GSTR-3B
- Rule 66 – TDS returns
- Supersedes/Amends:
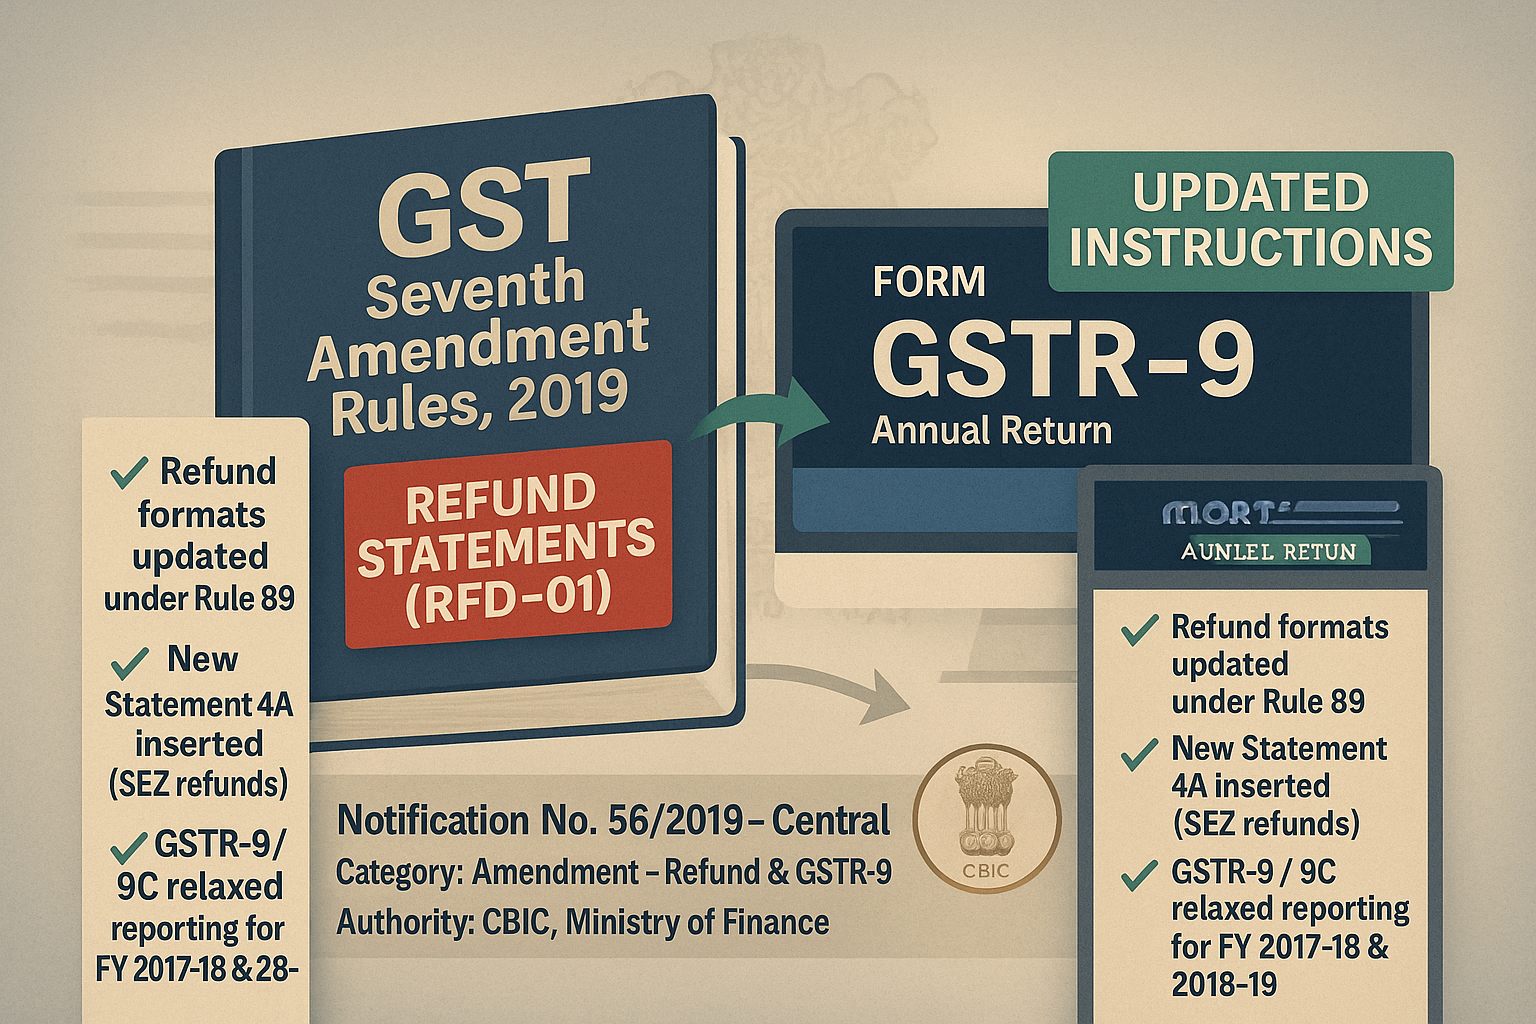
- Amends various refund-related statements in FORM GST RFD-01
- Amends Annual Return FORM GSTR-9 and Reconciliation Statement FORM GSTR-9C
- Integrated GST Act: Not applicable
Summary of Notification
- Overhaul of Statements in Refund Application (FORM GST RFD-01):
The notification substituted Statements 1A to 6 under Annexure 1 of FORM GST RFD-01. These relate to various refund types including:
- Inverted duty structure
- Export with/without payment of tax
- SEZ supplies
- Deemed exports
- POS correction (inter-state/intra-state)
New formats include enhanced tables for document-wise details, BRC/FIRC entries, SEZ endorsements, and supply classifications to streamline refund processing.
- Amendments to FORM GSTR-9 (Annual Return):
Numerous clarifications and flexibilities introduced for FY 2017–18 and 2018–19:
- Optional reporting of net values in specific tables (e.g., credit/debit note adjustments, amendments).
- Consolidated disclosure allowed for exempted/nil-rated/non-GST supplies.
- Optional breakup of ITC into inputs, capital goods, input services.
- Flexibility in declaring reversals and adjustments.
- Auto-population logic clarified for Table 8A (GSTR-2A matching), with manual upload allowed in GSTR-9C.
- Amendments to FORM GSTR-9C (Reconciliation Statement):
Key modifications include:
- Optional reporting for FY 2017–18 and 2018–19 in Tables 5B to 5N (with provision to report adjustments in Table 5O instead).
- Flexibility in declaring ITC breakdowns and supply classifications.
- Revised certification format in Part B with clearer responsibilities and disclaimers by the auditor or self-certifier.