Notification No.: 45/2023 – Central Tax
Date of Notification: 6th September 2023
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 164 – Power of Government to make rules
- CGST Rules, 2017 (Amended):
- Rule 31B (Inserted) – Value of supply in case of online gaming including online money gaming
- Rule 31C (Inserted) – Value of supply of actionable claims in case of casino
Summary of Notification:
- This notification introduces the Central Goods and Services Tax (Third Amendment) Rules, 2023 by inserting two new rules, namely Rule 31B and Rule 31C, specifically addressing valuation of supplies in the context of online gaming, online money gaming, and casinos.
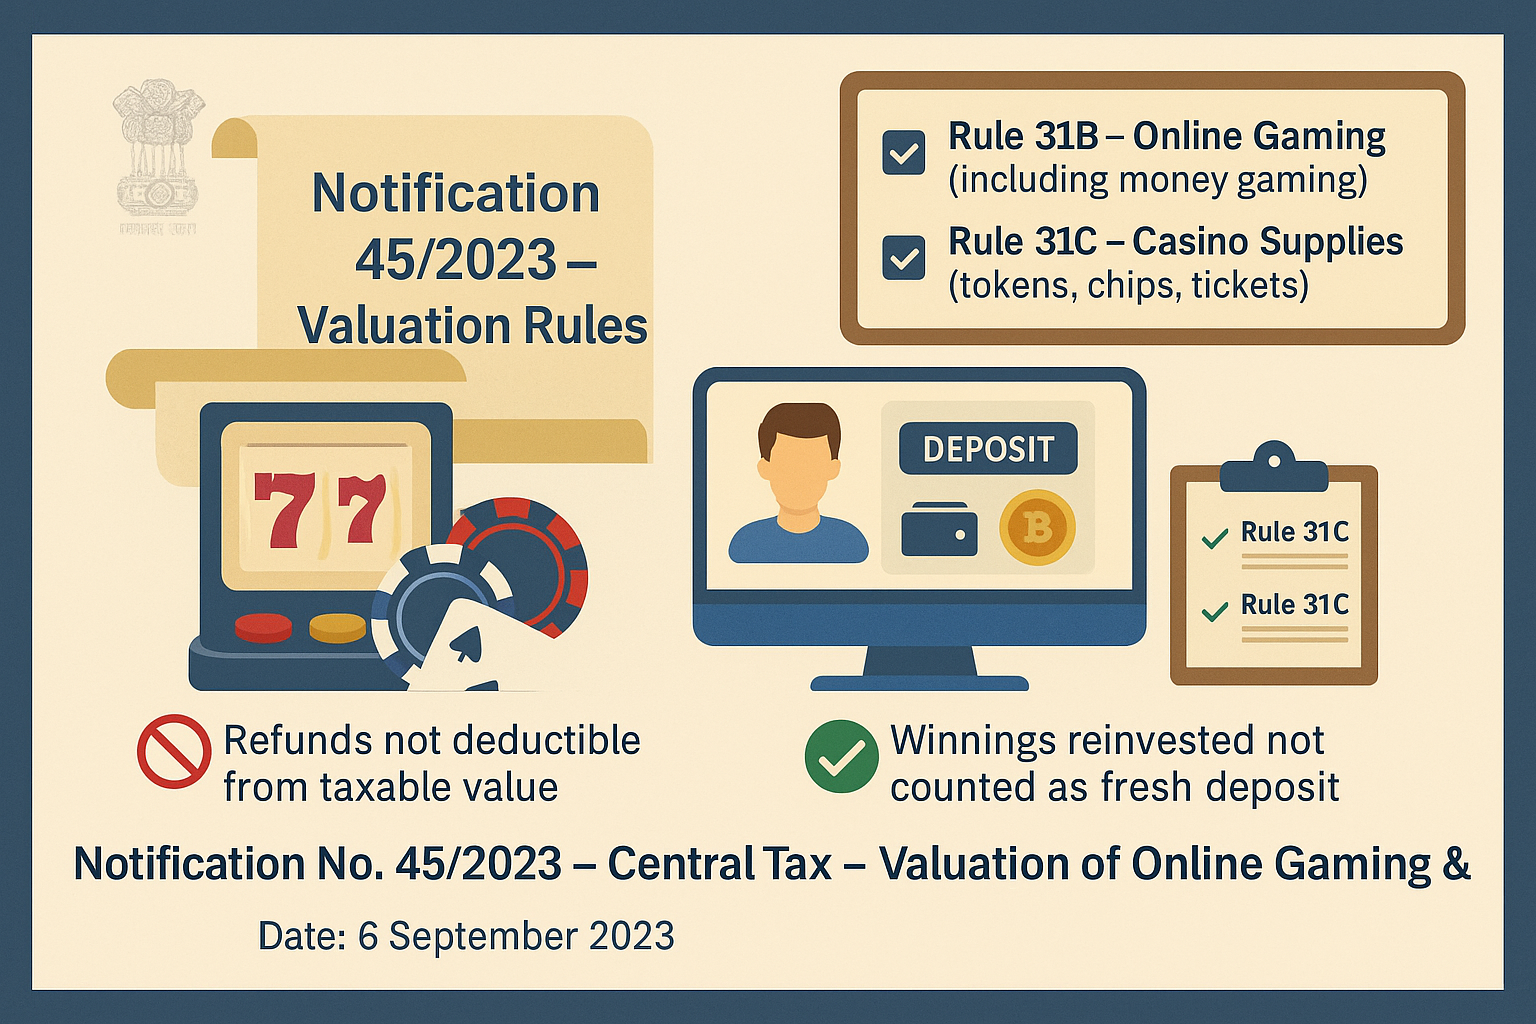
- Rule 31B – Online Gaming (including money gaming):
- The value of supply shall be the total amount paid or payable to or deposited with the supplier by way of money or money’s worth (including virtual digital assets) by or on behalf of the player.
- Any amount refunded or returned by the supplier (including unused balances) shall not be deductible from the value of supply.
- Rule 31C – Casinos:
- The value of supply of actionable claims in a casino shall be the total amount paid or payable for:
(i) purchase of tokens, chips, coins, or tickets, or
(ii) direct participation in any casino event, game, or competition. - Refunds or returns of tokens/chips/tickets shall not be deductible from the value of supply.
- The value of supply of actionable claims in a casino shall be the total amount paid or payable for:
- Explanation to Rules 31B & 31C:
- Any winnings received by a player and subsequently used for further play without withdrawal shall not be treated as fresh payment or deposit for valuation purposes.
- This amendment clarifies the valuation mechanism for taxation of online gaming and casinos, aligning with the policy framework of taxing the full face value of entry amounts rather than net balances or refunds.