Notification No.: 49/2017 – Central Tax
Date of Notification: 18th October 2017
Relevant Sections and Rules:
- Central GST Act, 2017: Section 54 (Refund of tax)
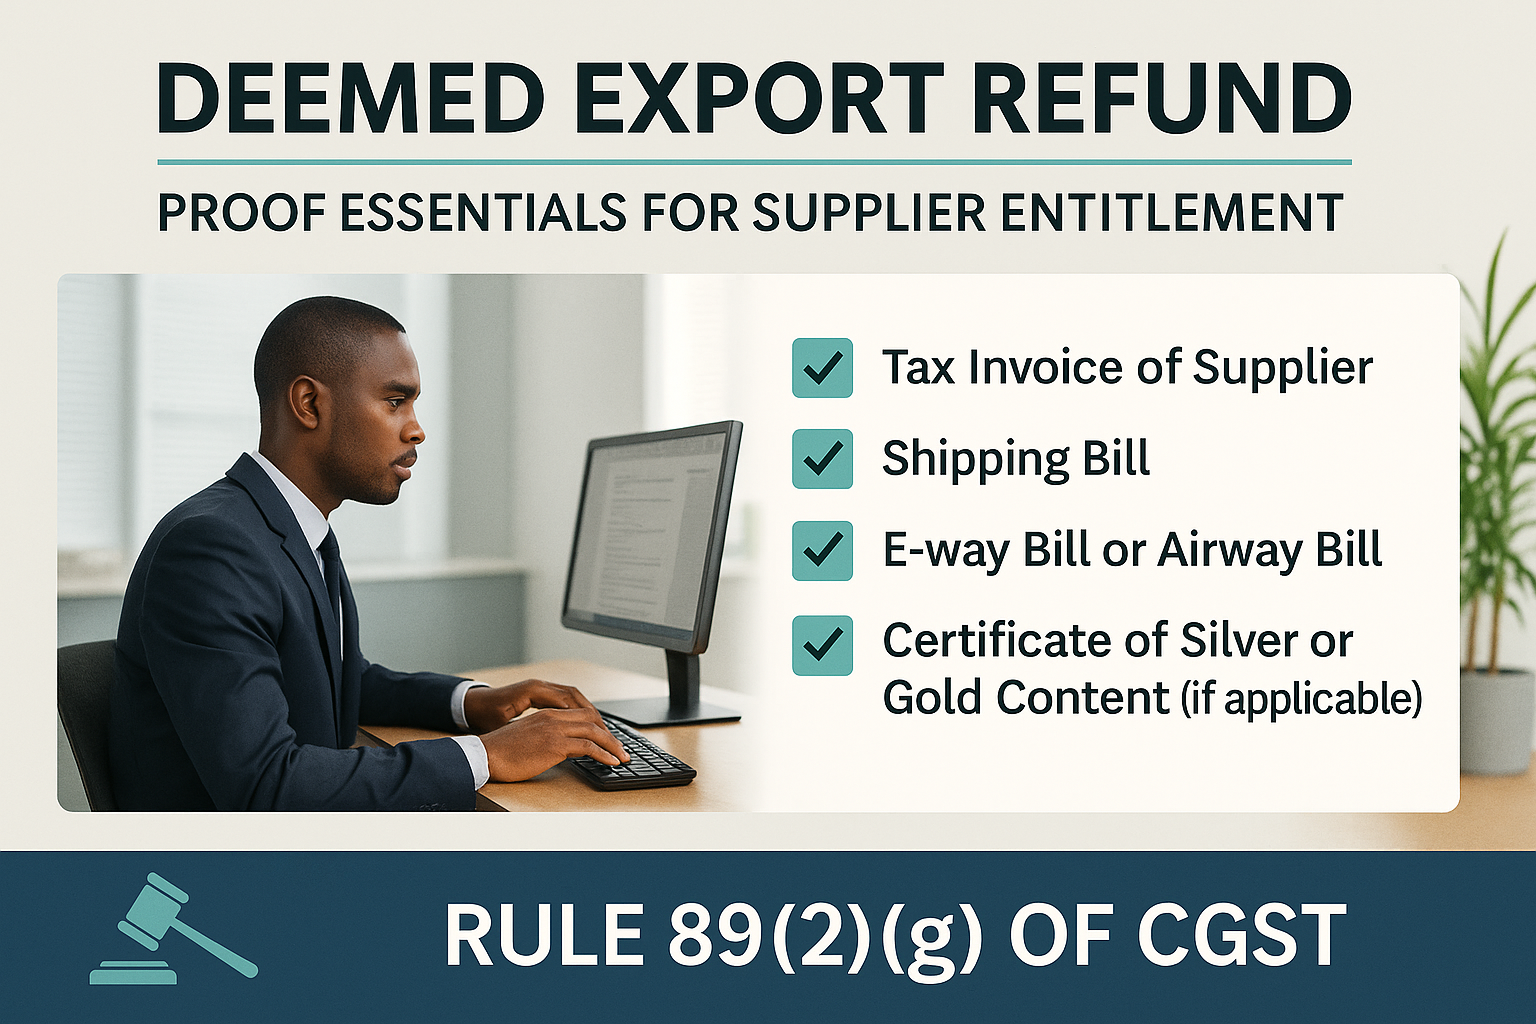
- CGST Rules, 2017: Rule 89(2)(g) – Evidence required for refund of deemed exports
- Read With: Notification No. 48/2017 – Central Tax (Deemed exports notified under Section 147)
- Integrated GST Act: Not directly applicable
Summary of Notification
Specification of Evidences for Claiming Refund on Deemed Export Supplies:
The Central Government, in continuation of Notification No. 48/2017, notifies the evidentiary documents to be furnished by suppliers claiming refund of tax paid on deemed exports under Rule 89(2)(g) of the CGST Rules, 2017.
Required Evidences:
- Proof of Receipt of Supplies:
- Either an acknowledgment by the jurisdictional tax officer of the Advance Authorisation or EPCG Authorisation holder, or
- A copy of the tax invoice, duly signed by the recipient EOU, confirming receipt of the goods.
- Undertaking – No ITC Availed:
- A written undertaking from the recipient of deemed export supplies that no input tax credit has been availed on such supplies.
- Undertaking – No Refund to Recipient:
- A written undertaking from the recipient that he shall not claim refund on such supplies and that the supplier is entitled to claim the refund.
These documents ensure proper verification and prevent dual claims of refund or ITC benefit in respect of deemed export transactions.