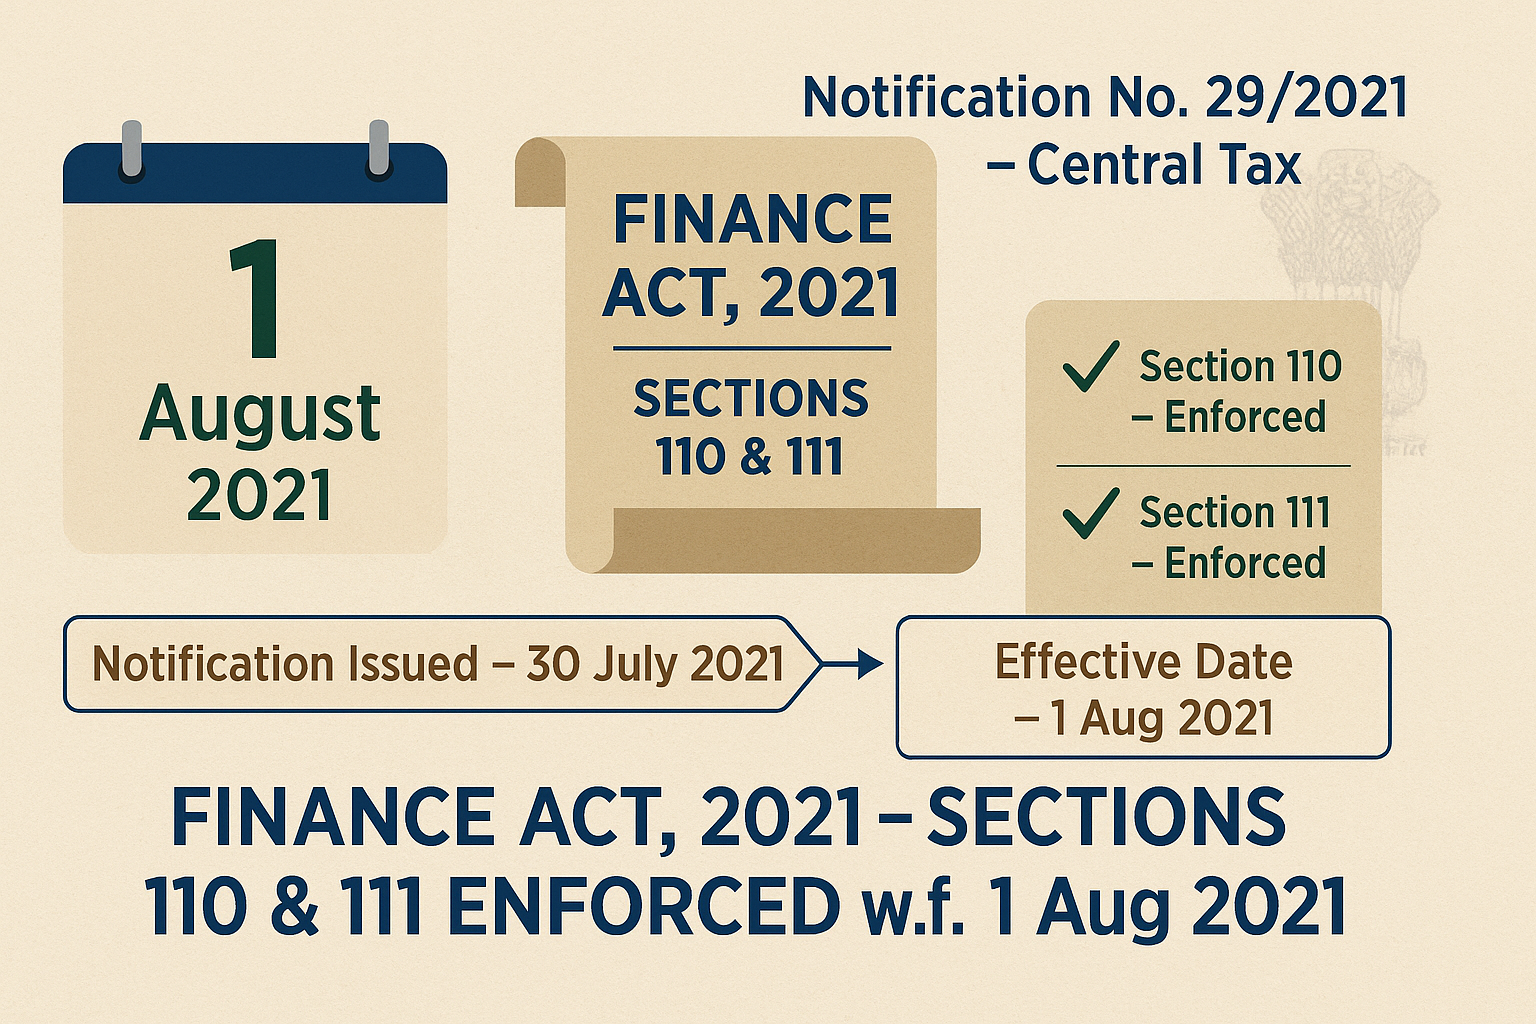
Notification No.: 29/2021 – Central Tax
Date of Notification: 30th July 2021
Relevant Sections and Rules
Central GST Act, 2017:
- Section 44 – Annual return (substituted by Finance Act, 2021)
- Section 35(5) – Audit by CA/CMA (omitted by Finance Act, 2021)
Finance Act, 2021 (13 of 2021):
- Section 1(2)(b) – Power to appoint commencement dates
- Sections 110 and 111 – Notified into force w.e.f. 1st August 2021
CGST Rules, 2017:
- Rule 80 – Annual return (aligned through separate notification after Section 44 substitution)
Integrated GST Act, 2017:
- Not applicable
Summary of Notification
- Commencement of Sections 110 and 111 of Finance Act, 2021:
The Government appoints 1st August 2021 as the date from which Sections 110 and 111 of the Finance Act, 2021 come into force. These sections amend the CGST Act by substituting Section 44 and omitting Section 35(5). - Removal of Mandatory Audit Requirement (Section 35(5)):
With effect from 1st August 2021, the requirement of audit and certification of reconciliation statement by a Chartered Accountant/Cost Accountant under Section 35(5) is omitted. - Simplification of Annual Return (Section 44):
Section 44 has been substituted to provide for self-certified annual return. Taxpayers are no longer required to get the return certified by professionals, except where specifically notified. - Consequential Change in Rules:
Rule 80 of the CGST Rules, dealing with annual returns, stands amended through a separate notification to align with the substituted Section 44 framework.