Notification No.: 16/2017 – Central Tax
Date of Notification: 7th July 2017
Relevant Sections and Rules:
- Central GST Rules, 2017: Rule 96A(5)
- Central GST Act, 2017: Section 54 read with Section 164 (rule-making power)
- Integrated GST Act: Not directly applicable
Summary of Notification
Conditions for Furnishing Letter of Undertaking (LUT) in Place of Bond for Exports without IGST Payment:
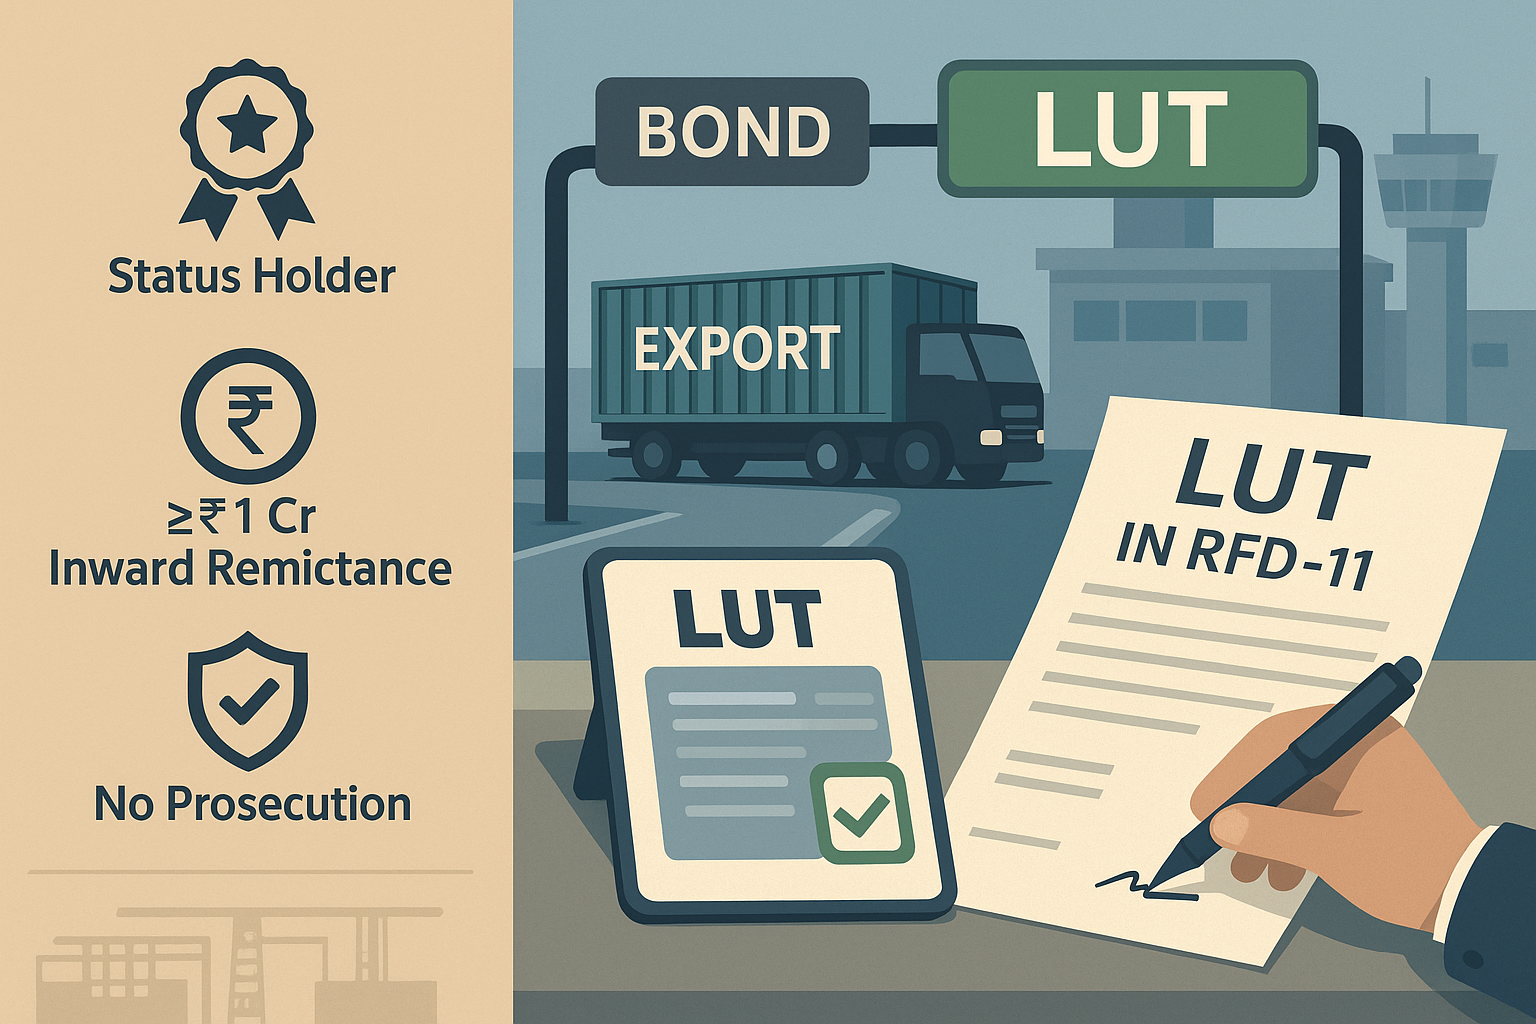
In exercise of the powers under Rule 96A(5) of the CGST Rules, 2017, the Central Board of Excise and Customs notified the conditions and safeguards for exporters who wish to furnish a Letter of Undertaking (LUT) instead of a bond for making exports without payment of Integrated Tax (IGST). Eligibility criteria are:
- Status Holder Exporters as defined in Para 5 of the Foreign Trade Policy 2015–2020; or
- Exporters who received foreign inward remittance of at least:
- 10% of export turnover, and
- Not less than ₹1 crore in the preceding financial year.
Additionally, the exporter must not have been prosecuted for any tax evasion offence exceeding ₹2.5 crore under GST or any previous tax laws.
Procedure for Submission:
- The LUT must be submitted in duplicate for each financial year, using the annexure to FORM GST RFD-11.
- It must be executed on the registered person’s letterhead by an authorized signatory such as:
- Working Partner
- Managing Director
- Company Secretary
- Proprietor
- Or any authorized person by the Board of Directors