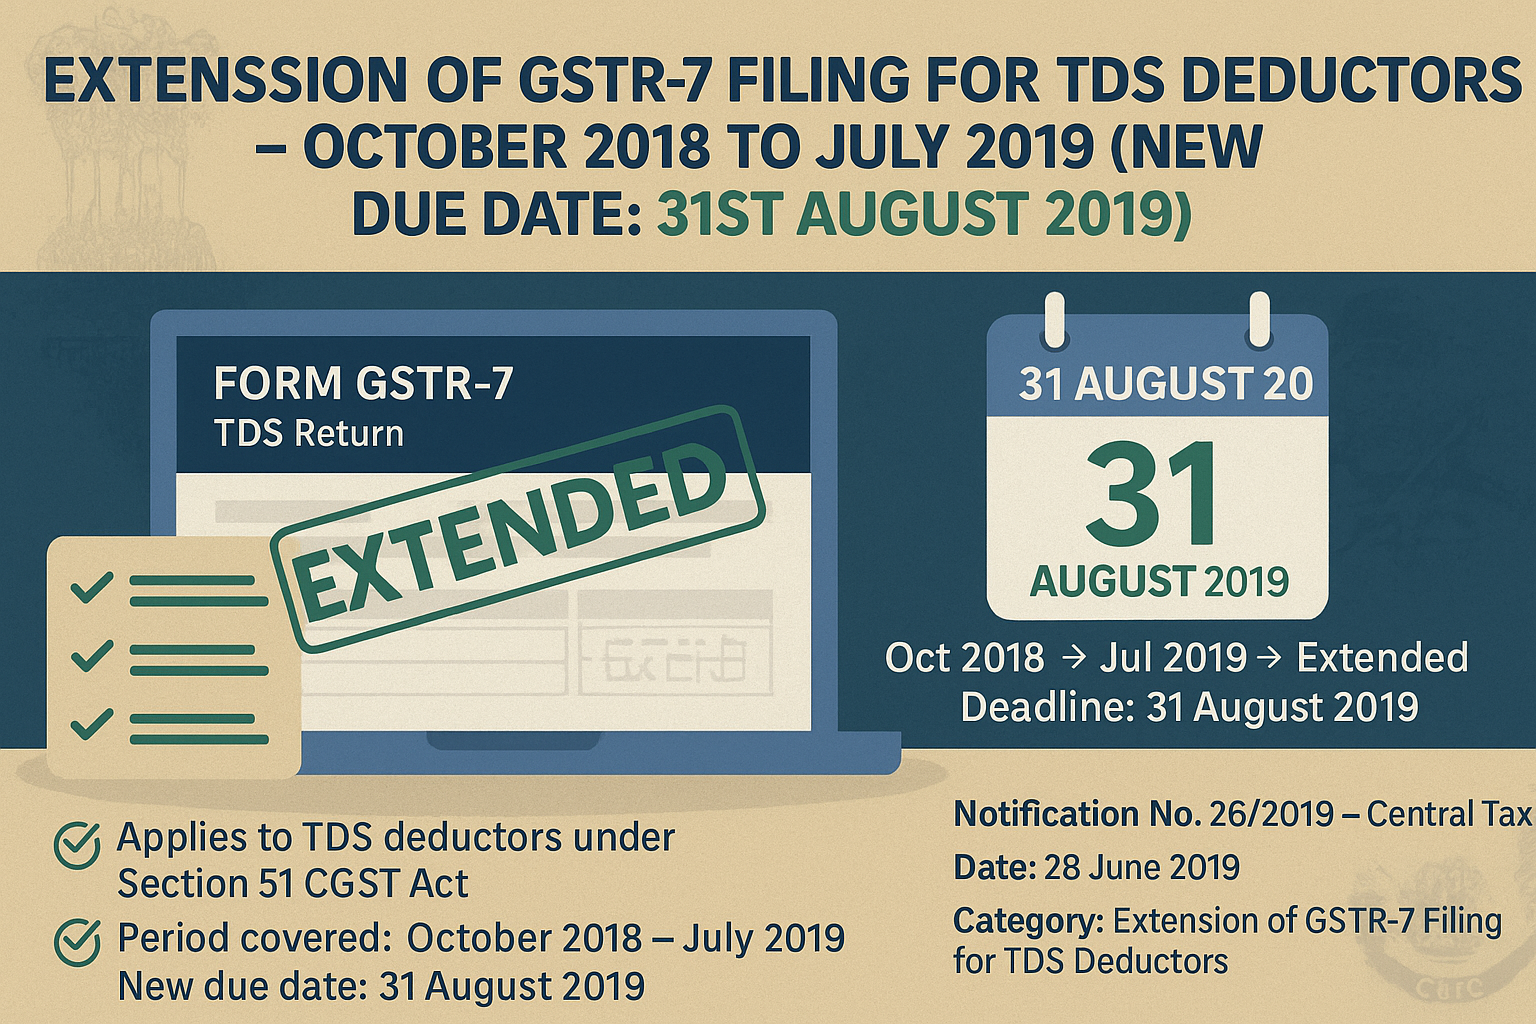
Notification No.: 26/2019 – Central Tax
Date of Notification: 28th June 2019
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 39(6) – Extension of time for return filing
- Section 51 – Tax Deduction at Source (TDS)
- Section 168 – Power to issue instructions
- CGST Rules, 2017:
- Rule 66 – Filing of GSTR-7 (TDS Return)
- Supersedes:
- Notification No. 66/2018 – Central Tax (29th November 2018)
- Notification No. 8/2019 – Central Tax (8th February 2019)
- Notification No. 18/2019 – Central Tax (10th April 2019)
Summary of Notification
Unified Extension of Due Date for GSTR-7 Filing (TDS Returns: Oct 2018 – July 2019):
The Central Government, through this notification, superseded three previous notifications and issued a single consolidated extension for the due date of filing FORM GSTR-7 for the months October 2018 to July 2019.
Revised Due Date for All Affected Periods:
31st August 2019
Applicability:
Registered persons liable to deduct tax at source under Section 51 of the CGST Act.
This comprehensive extension was issued to simplify compliance for TDS deductors who faced delays in return filing across multiple months due to ongoing system changes and notifications.