
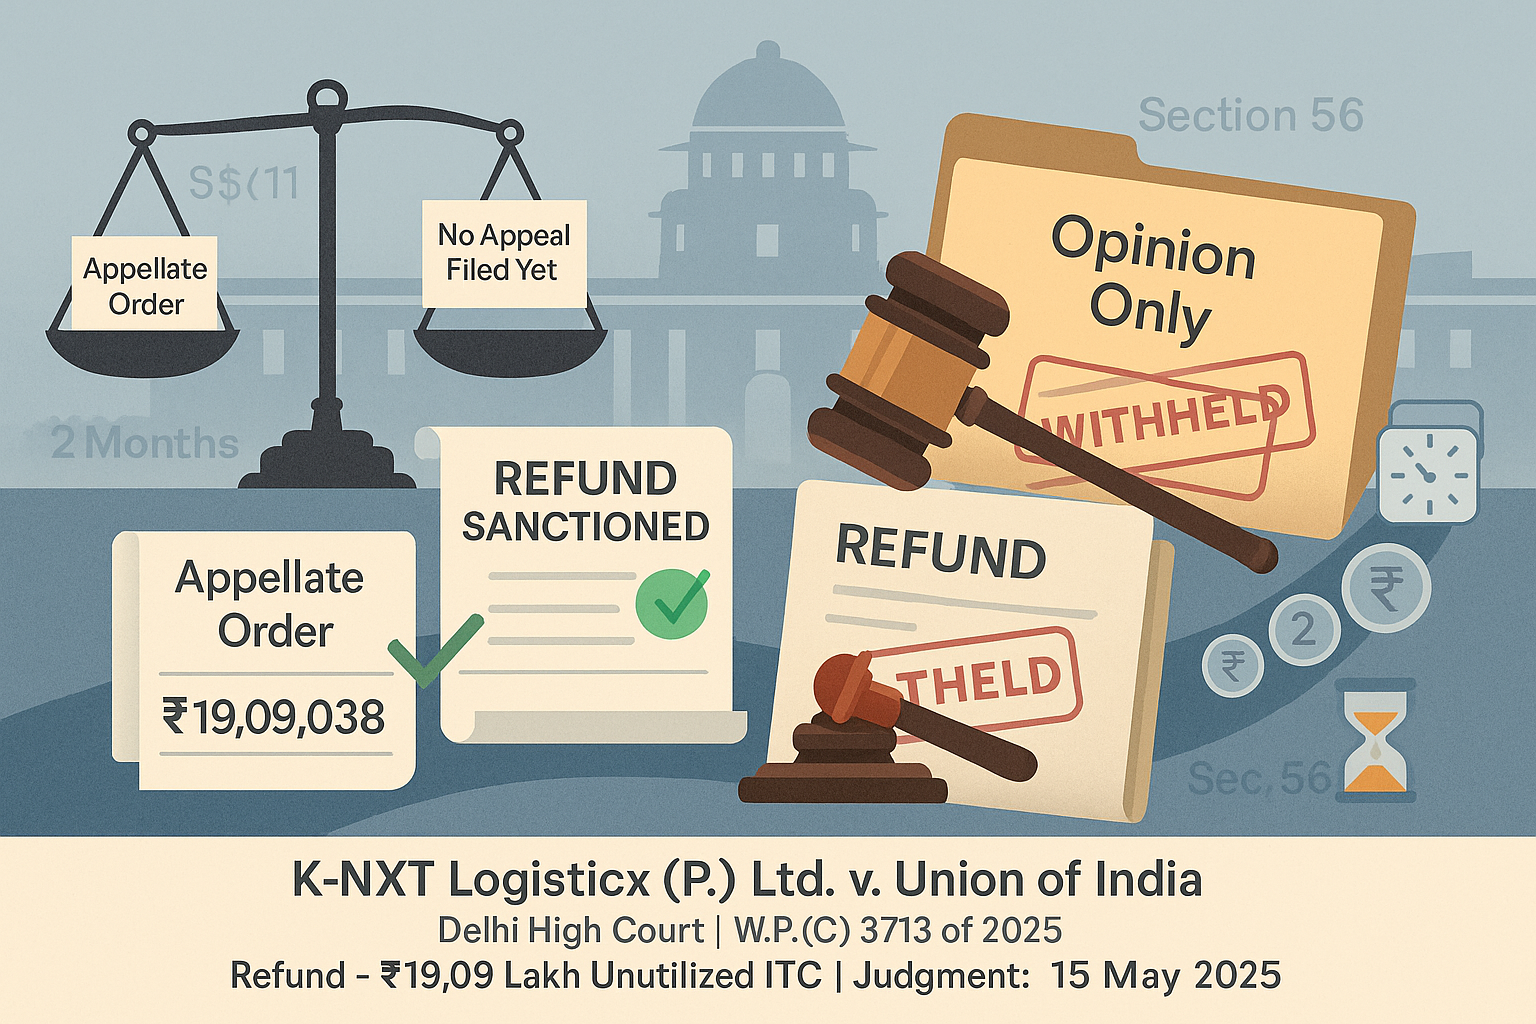
Case Title: K-NXT Logisticx (P.) Ltd. v. Union of India
Court: High Court of Delhi
Petition Number: W.P. (C) No. 3713 of 2025, CM APPL. No. 17335 of 2025
Category: Refund – Unutilized Input Tax Credit
Judgement Date: 15th May 2025
Relevant Sections: Section 54(11) and Section 56 of the CGST Act, 2017
Judges: Prathiba M. Singh and Rajneesh Kumar Gupta, JJ.
Facts of the Case [Paras 2–6]
- The Petitioner, K-NXT Logisticx Pvt. Ltd., engaged in freight forwarding, filed a refund claim of ₹19,09,038 for unutilized ITC for January 2023, citing accumulation of ITC due to output supplies taxed at 18%.
- The refund was filed on 07.04.2023; however, it was rejected by the Assistant Commissioner on 12.06.2023 even while the show cause proceedings were pending.
- On appeal, the Appellate Authority allowed the refund claim on 16.01.2024.
- Despite multiple representations thereafter, the refund was not disbursed.
- The Department invoked Section 54(11) to withhold the refund, citing potential revenue loss due to alleged malfeasance and pending appellate proceedings.
Questions in Consideration [Paras 6–9]
- Can the Department withhold refund sanctioned by the Appellate Authority using Section 54(11) of the CGST Act without actually challenging the said appellate order?
- Does mere expression of the Commissioner’s opinion constitute sufficient grounds to withhold refund under Section 54(11)?
Observations of the Court [Paras 7–17]
- Section 54(11) permits withholding of refund only when:
- An appeal or other proceedings against the refund order are pending, and
- The Commissioner opines that refund could adversely affect revenue due to malfeasance or fraud.
[Para 13]
- Relying solely on the Commissioner’s opinion without an actual challenge to the appellate order is insufficient to delay the refund. [Para 14]
- The Court referred to its prior rulings (Shalender Kumar and G.S. Industries) affirming that refund cannot be denied merely because the Department intends to challenge the order, unless such challenge is pending. [Paras 14–15]
- The Department has not filed any appeal or sought stay; hence, it cannot unilaterally override the Appellate Authority’s order. [Para 14]
Judgement of the Court [Paras 15–17]
- The Court directed the Department to process the refund with interest under Section 56 within two months. [Para 16]
- It clarified that if any appeal is subsequently filed by the Department, the refund granted shall be subject to the outcome of such appeal. [Para 16]
- The petition was disposed of accordingly. [Para 10]
Between Fine Lines
- Refunds allowed by the Appellate Authority cannot be withheld solely on the basis of the Commissioner’s opinion under Section 54(11).
- Actual appellate proceedings must be pending for Section 54(11) to be invoked.
- The Department cannot delay refunds indefinitely by citing “intention to appeal.”
- Statutory interest will accrue on delayed refunds, which may financially impact the Department.
- The High Court reinforces judicial discipline in executing appellate orders.
Summary of Referred Cases
| S. No. | Name of Case | Citation | Summary | Verdict |
| 1. | Shalender Kumar v. CGST Commissioner | [2025] 174 taxmann.com 138 (Delhi) | Refund withheld citing Section 54(11); Court ruled refund must be processed if no pending appeal exists. | Refund allowed |
| 2. | G.S. Industries v. Union of India | Order dated 03.01.2022 | Refund was not disbursed despite favourable appellate order; court upheld refund unless appeal is filed. | Refund to be processed immediately |
| 3. | Brij Mohan Mangla v. Union of India & Ors. | W.P.(C) 14234/2022, dated 23.02.2023 | Reaffirmed the legal position that refund can’t be withheld on mere intention to appeal. | Refund allowed unless appeal is pending |
Takeaway
“No Appeal, No Withholding – Refunds Must Flow When Orders Prevail”



