
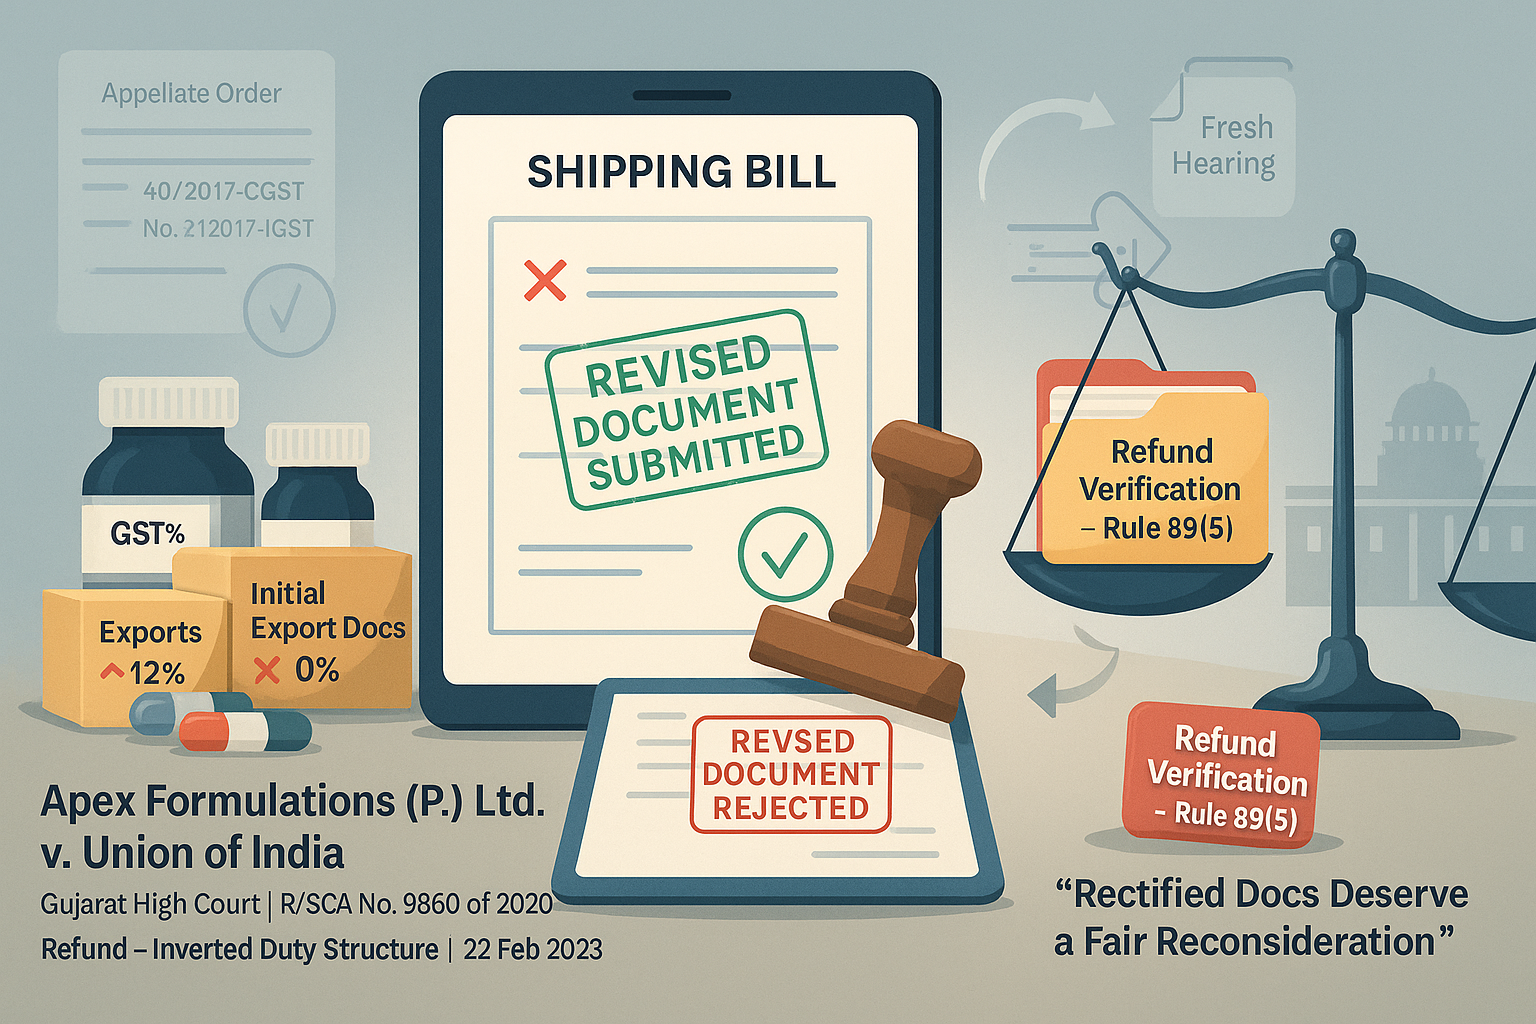
Apex Formulations (P.) Ltd. v. Union of India
High Court of Gujarat
R/Special Civil Application No. 9860 of 2020
Category: Refund – Inverted Duty Structure
Date of Judgment: 22 February 2023
Relevant Section: Rule 89(5) of CGST Rules, 2017; Notification No. 40/2017-CGST (Rate); Notification No. 41/2017-IGST (Rate)
Facts of the Case
[Para 5–6]
- The petitioner, Apex Formulations Pvt. Ltd., manufactures and sells pharmaceutical products. It procures inputs taxed at 18% GST while output supplies are taxed at 12%, and to exporters at 0.1% under Notifications 40/2017-CGST and 41/2017-IGST dated 23-10-2017.
- Due to the inverted duty structure, the petitioner applied for refund under Rule 89(5) of CGST Rules, which was granted via order dated 26.03.2019.
[Para 6]
- The refund was challenged by the CGST department on the grounds that the Exporter had not mentioned the petitioner’s name and GSTIN on the shipping bill, an essential condition under the said Notifications. The Appellate Authority accepted the department’s appeal and reversed the refund order on 01.05.2020.
Question(s) in Consideration
[Para 2]
- Whether omission of the petitioner’s name and GSTIN in the Exporter’s shipping bill invalidates the refund granted under Rule 89(5)?
- Whether revised documents submitted subsequently can cure such a defect and entitle the petitioner to refund?
Observations of the Court
[Para 10]
- The Court noted that initially the Exporter failed to mention the petitioner’s name and GSTIN in the shipping bill.
- However, refund was sanctioned based on factual verification of goods supplied by petitioner to the Exporter.
- Subsequently, a revised form containing correct details was submitted, but the Appellate Authority failed to consider this material aspect.
Judgment of the Court
[Para 11]
- The Court allowed the writ petition and quashed the appellate order dated 01.05.2020.
- The matter was remanded back to the Appellate Authority to decide afresh considering all documents, including revised submissions, without being influenced by previous orders.
- The appeal filed by the CGST is revived, and the petitioner is permitted to file further supporting documents with affidavit.
Between Fine Lines
- The Gujarat High Court held that a technical omission in the exporter’s shipping bill (name and GSTIN of the supplier) can be cured through revised documentation.
- Refund granted earlier was not devoid of factual foundation.
- The case emphasizes the importance of considering subsequent compliance during appeal.
- All issues are left open for re-adjudication by the appellate authority.
- No adverse inference should be drawn based solely on initial technical defects if corrected in time.
Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
| None cited explicitly in judgment | — | — | — |
Takeaway: Rectifiable Technical Lapses Cannot Eclipse Genuine Refund Claims



