
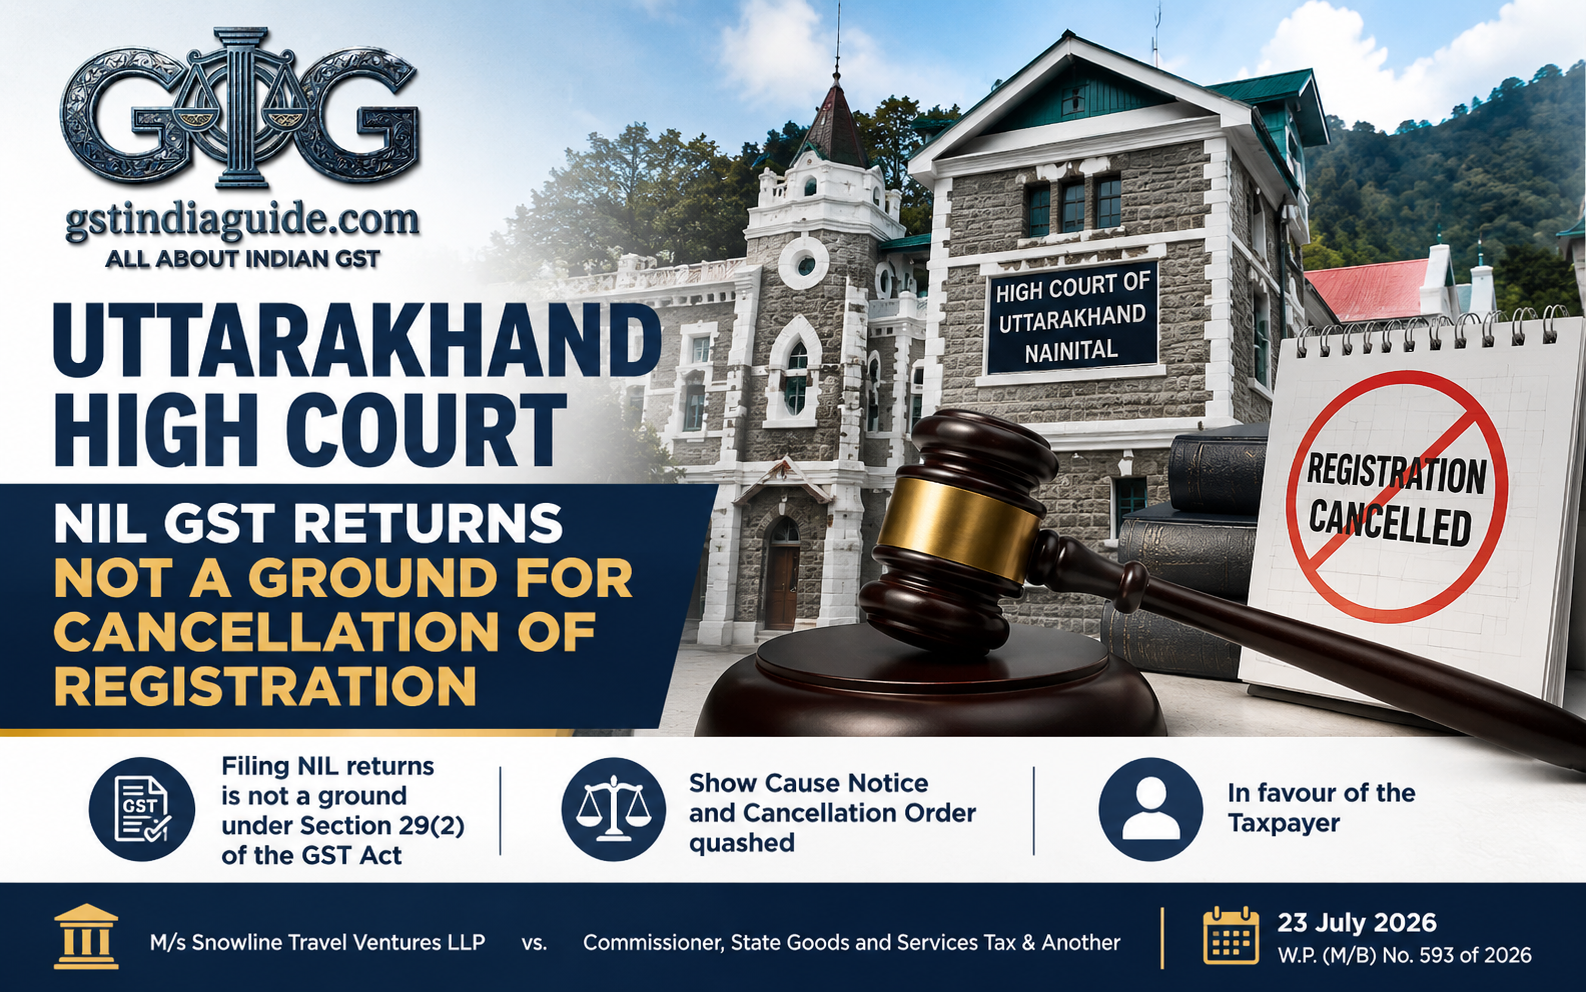
The Uttarakhand High Court has held that the mere filing of NIL GST returns for several months is not a legally recognised ground for cancellation of GST registration under Section 29(2) of the GST Act. The Court accordingly quashed both the show cause notice and the consequential registration cancellation order issued against M/s Snowline Travel Ventures LLP.
The petitioner approached the High Court challenging a show cause notice dated 6 November 2024 and the cancellation order dated 26 December 2024. The registration had been cancelled on the stated ground that the petitioner had been “filing NIL return from last several months.”
Whether Filing NIL Returns Justifies GST Cancellation
The principal issue before the Court was whether continued filing of NIL returns falls within any of the circumstances specified under Section 29(2) of the GST Act, which empowers the proper officer to cancel a taxpayer’s registration.
The petitioner argued that cancellation of registration is permissible only on one or more of the statutory grounds specifically enumerated under Section 29(2). Since filing NIL returns is not included among those grounds, the cancellation action was stated to be without authority of law.
The petitioner also relied upon the Andhra Pradesh High Court’s decision in Kali Shanker Enterprises v. Additional Commissioner, Goods and Service Tax Officer, reported in 2024 (1) TMI 430.
High Court’s Findings
The Division Bench accepted the petitioner’s submission and agreed with the view taken by the Andhra Pradesh High Court. It held that filing NIL returns is not a ground contemplated under Section 29(2) of the GST Act.
The Court emphasised, in effect, that the power to cancel GST registration must be exercised within the limits prescribed by the statute. An authority cannot introduce an additional ground for cancellation that does not find place in Section 29(2).
Since the very basis of the proceedings was legally unsustainable, the Court held that neither the show cause notice nor the cancellation order could survive.
Show Cause Notice and Cancellation Order Quashed
The Uttarakhand High Court quashed the show cause notice dated 6 November 2024 as well as the consequential order dated 26 December 2024 cancelling the petitioner’s GST registration. The writ petition was allowed, and all pending applications were disposed of.
Key Legal Principle
Filing NIL GST returns for several months, by itself, is not a statutory ground for cancellation of GST registration under Section 29(2) of the GST Act. Cancellation proceedings initiated solely on that basis are without legal foundation and are liable to be quashed.
Why This Judgment Matters
The ruling reinforces that GST registration cannot be cancelled merely because a registered person reports no taxable turnover for a particular period. Proper officers must identify and establish one of the specific statutory grounds contained in Section 29(2) before exercising the power of cancellation.
The judgment is relevant for businesses with seasonal operations, temporarily inactive enterprises, start-ups, travel operators and other registered persons who may legitimately file NIL returns during periods in which no taxable supplies are made. It also reiterates that administrative action affecting registration must remain strictly within the statutory framework.
Conclusion
The Uttarakhand High Court has clarified that regular filing of NIL returns does not constitute non-compliance warranting cancellation of GST registration. Where the taxpayer continues to file returns, the absence of taxable transactions cannot, without any other statutory violation, provide an independent basis for cancellation under Section 29(2).

 of the GST Act.)