Notification No.: Corrigendum to Notification No. 32/2017 – Central Tax
Date of Corrigendum: 10th July 2017
Relevant Sections and Rules:
- Central GST Act, 2017: Section 23(2) (relating to exemption from registration)
- Corrigendum to: Notification No. 16/2017 – Central Tax dated 7th July 2017
- Integrated GST Act: Not applicable
Summary of Corrigendum
Correction in Reference to Foreign Trade Policy Paragraphs for Status Holder Exporters:
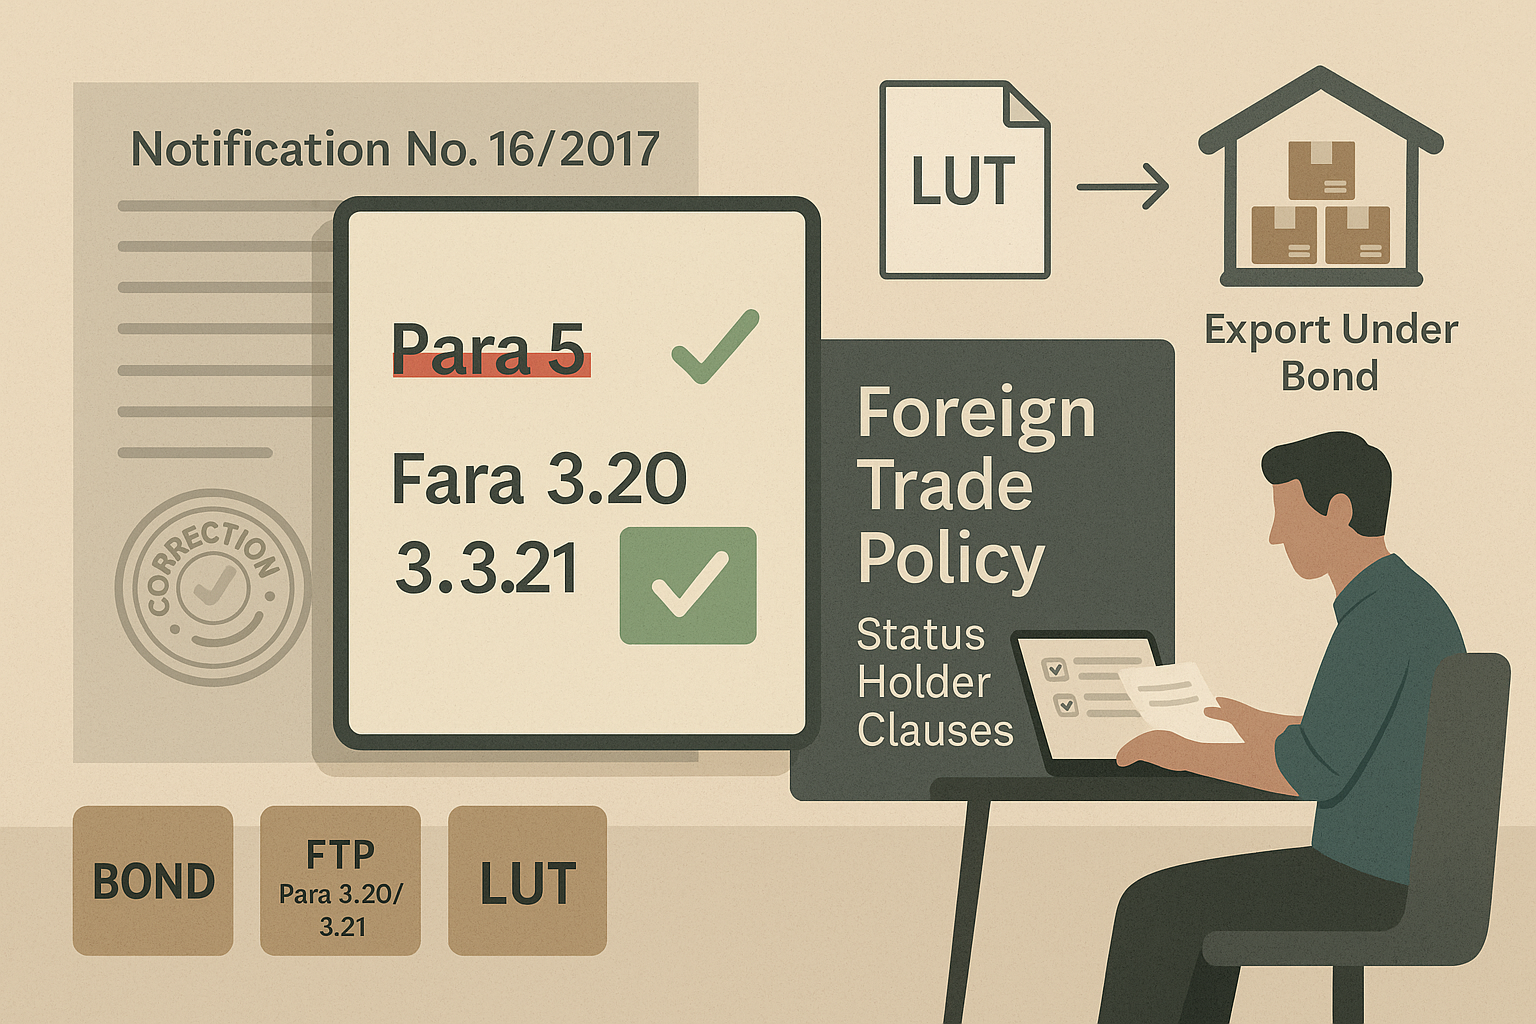
This corrigendum addresses a textual correction in Notification No. 16/2017 – Central Tax, which specified eligibility conditions for furnishing a Letter of Undertaking (LUT) in place of a bond for exports without IGST payment.
- Original Text: Cited “Paragraph 5” of the Foreign Trade Policy (FTP) 2015–2020.
- Corrected Text: Replaces it with “Paragraphs 3.20 and 3.21” of the FTP 2015–2020.
These corrected paragraphs specifically define the criteria for recognizing status holder exporters, ensuring precision in eligibility determination under Rule 96A of the CGST Rules.
Source: Notification No.: Corrigendum to Notification No. 32/2017 – Central Tax