Notification No.: 34/2017 – Central Tax
Date of Notification: 15th September 2017
Relevant Sections and Rules:
- Central GST Act, 2017: Section 164
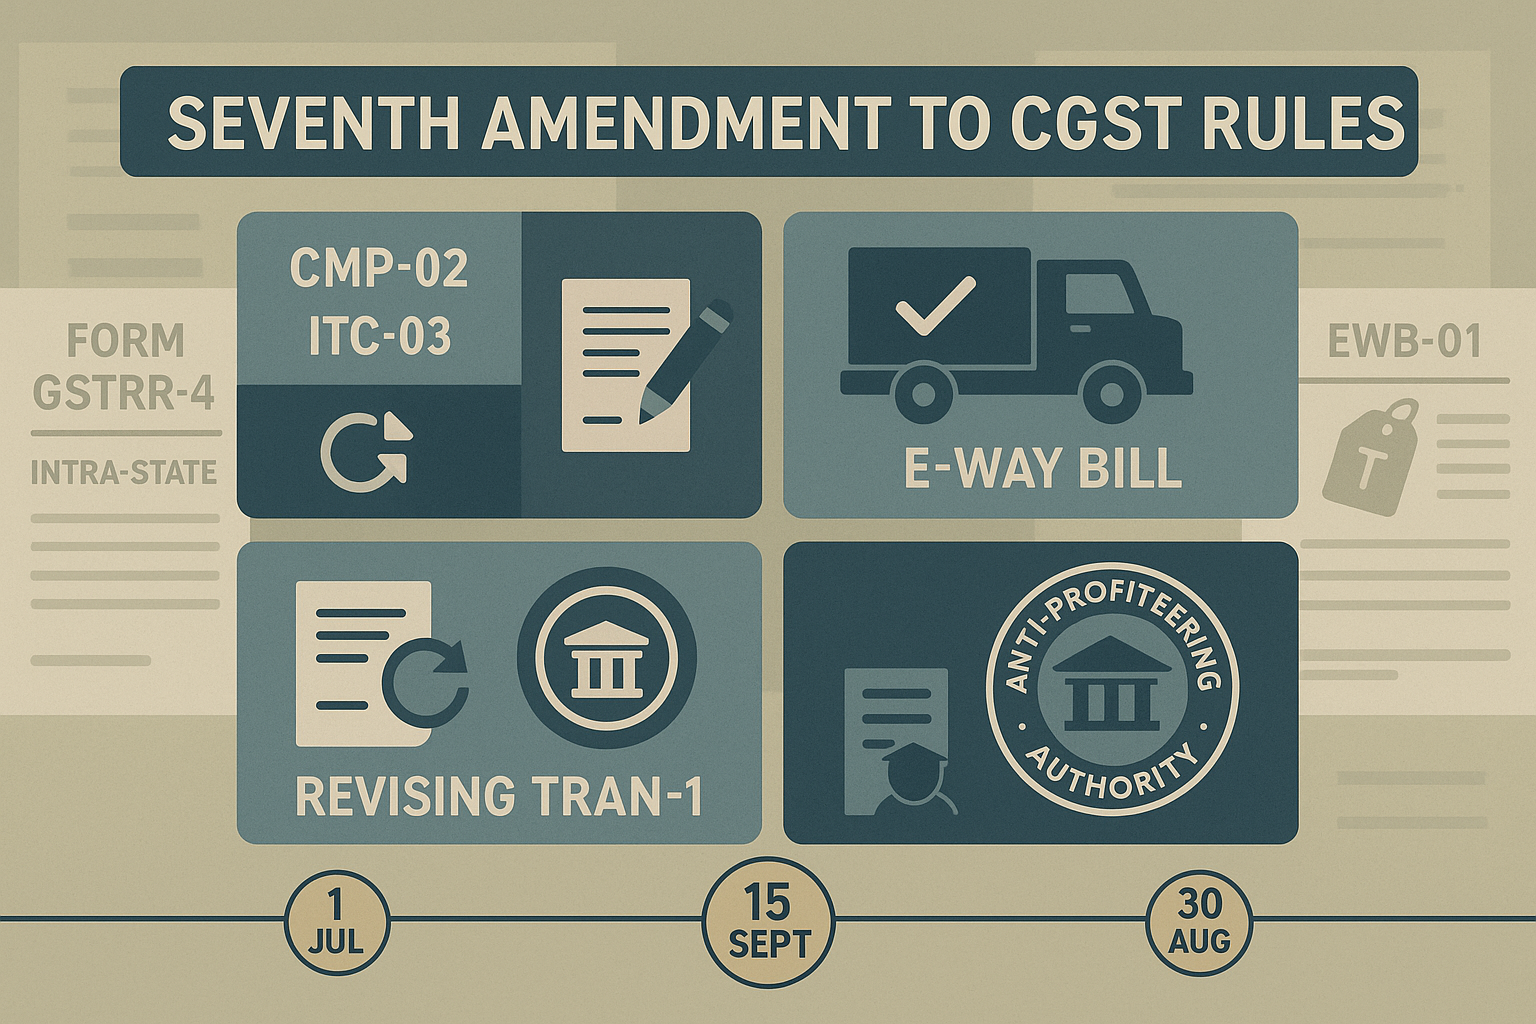
- CGST Rules, 2017 (Amendments): Rules 3, 120A, 122, 124, 127, 138; Forms: TRAN-1, GSTR-4, EWB-01
- Integrated GST Act: Not directly applicable
- Linked Notifications: 32/2017 – Central Tax (definition of handicrafts)
Summary of Notification
- Composition Scheme Opt-in (Rule 3):
New sub-rule 3A allows provisionally registered or new applicants to opt into the composition scheme under Section 10 by filing FORM CMP-02 by 1st October 2017. They must file FORM ITC-03 within 90 days. Once this is done, they cannot file TRAN-1. - Introduction of Rule 120A – One-Time Revision of TRAN-1:
Allows registered persons to revise TRAN-1 once if already filed under Rules 117–120, within the allowed or extended period. - Rule 122 – Tenure Added for Anti-Profiteering Members:
Members must have served at least one year as State/Central Tax Commissioner to qualify. - Rule 124 – Conditions for Termination of Anti-Profiteering Authority Members:
- Salary structure revised for Technical Members (pension adjustment for retired officers).
- Central Government may terminate Chairman or Technical Member based on GST Council’s recommendation and after hearing.
- Rule 127 – Quarterly Performance Report:
The Authority must submit performance reports to the GST Council by the 10th of the next quarter. - Rule 138 – E-way Bill Requirements Clarified:
- Mandatory e-way bill even below ₹50,000 for:
- Inter-State job work transfers
- Handicraft goods transported inter-State by unregistered but exempt suppliers
- “Handicraft goods” as defined in Notification 32/2017.
- Form Changes:
- TRAN-1: Clarifies use for Section 140(4)(a), (9); introduces CTD credit reporting.
- GSTR-4: Corrects entry 8B(2) from “Intra-State” to “Inter-State” supplies.
- EWB-01: Specifies that for imports, Bill of Entry is to be entered in place of invoice.