Circular No.: 26/26/2017-GST
Date of Circular: 29th December 2017
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 168(1): Power to issue instructions
- CGST Rules, 2017:
- Rules 61–67: Returns under GST
- Relevant Notifications:
- Notification Nos. 35/2017, 56/2017, 71/2017, 72/2017, 59/2017, 64/2017, etc.
Summary of Circular:
This circular consolidates and clarifies various aspects regarding the filing of GST returns, including timelines, late fees, and corrections in FORM GSTR-3B, in accordance with decisions taken in the 23rd GST Council meeting.
- Return Filing Calendar and Options:
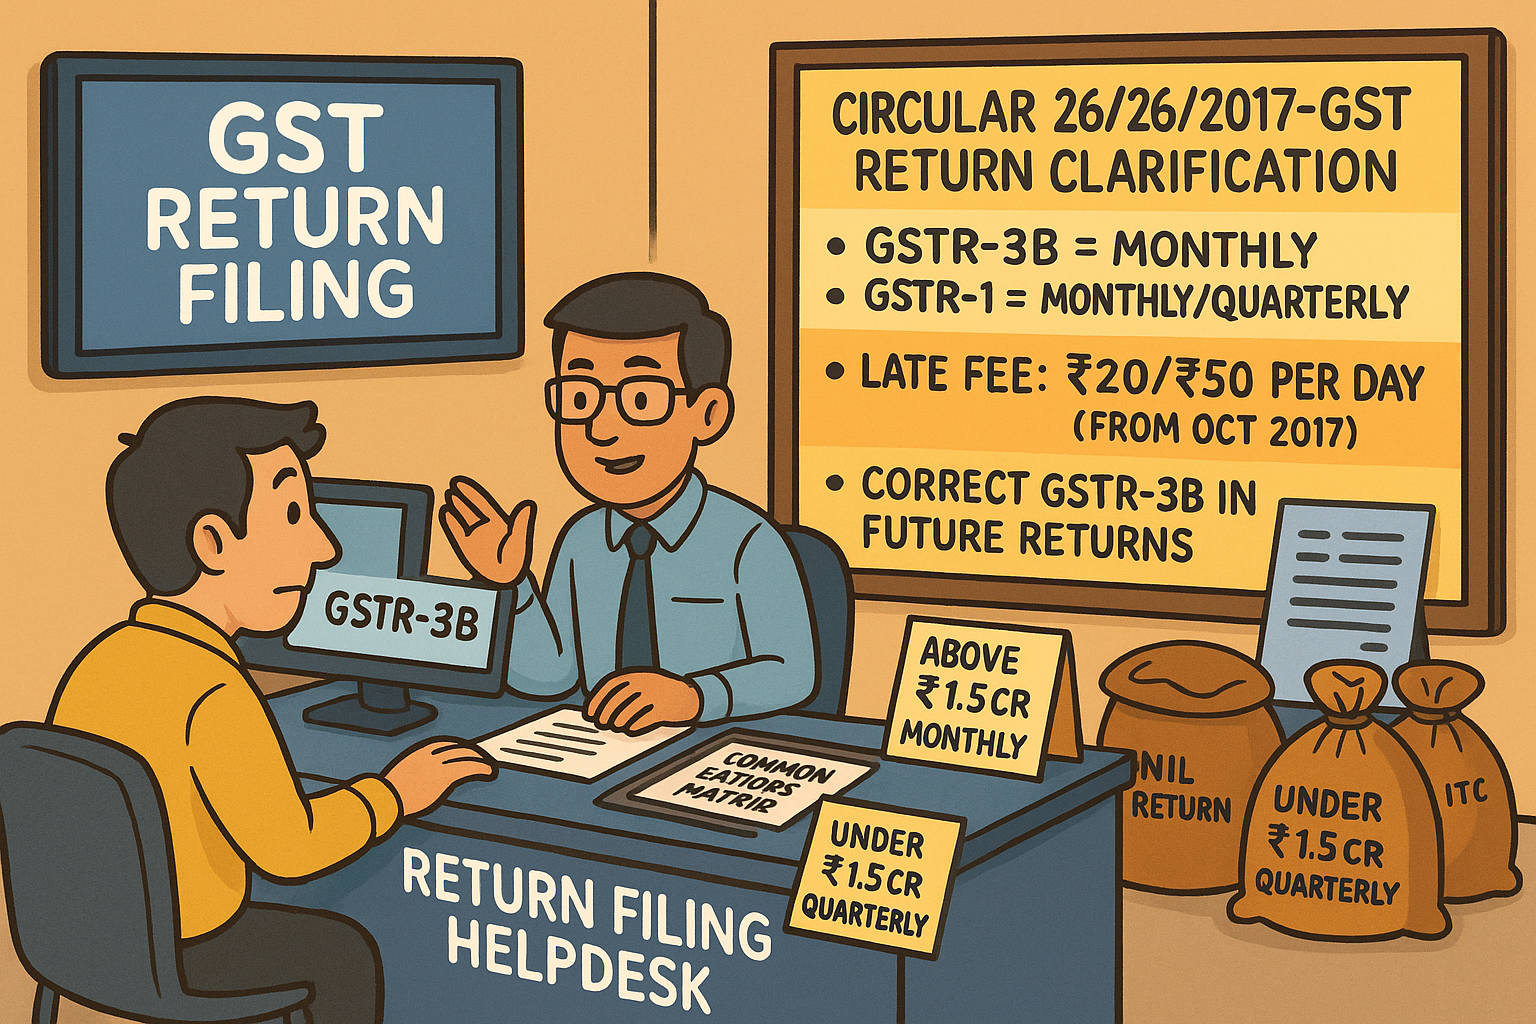
- All registered persons must file FORM GSTR-3B monthly.
- GSTR-1 to be filed:
- Quarterly by taxpayers with turnover ≤ ₹1.5 Cr.
- Monthly by taxpayers with turnover > ₹1.5 Cr.
- Taxpayers can choose monthly GSTR-1 filing even if eligible for quarterly, but must continue the same for the full financial year.
- Late Fee for GSTR-3B:
- Waived for July to September 2017 (via Notifications 28/2017 and 50/2017).
- From October 2017 onward:
- ₹20/day for NIL return (₹10 CGST + ₹10 SGST).
- ₹50/day for other cases (₹25 CGST + ₹25 SGST).
- Amendment and Correction Mechanism:
- Errors in GSTR-3B can be rectified in subsequent returns.
- GSTR-3B does not allow negative entries; adjustments must be made on a net basis in current or future returns.
- Circular No. 7/7/2017-GST on auto-reconciliation kept in abeyance pending system development.
- Common Error Scenarios and Corrections:
The circular provides a detailed matrix (7 common errors) covering:- Under-reporting or over-reporting of liability.
- Misreporting of IGST/CGST/SGST.
- Wrong ITC claims.
- Wrong tax head in challans.
- Provides step-by-step solutions based on the stage of error detection (submission, cash ledger, offset, or filed).
- Editing Option in GSTR-3B:
- Taxpayers can edit GSTR-3B before offsetting liability.
- Once offset and submitted, corrections must be made in subsequent months.
- Departmental Reconciliation:
- GSTR-3B will be matched with GSTR-1 (and eventually with GSTR-2/3 once enabled).
- Discrepancies will be dealt with under the provisions of CGST Act and Rules.
- Trade and Implementation Instructions:
- Field formations must issue trade notices to ensure uniform understanding and implementation.
Source: Circular No.: 26/26/2017-GST