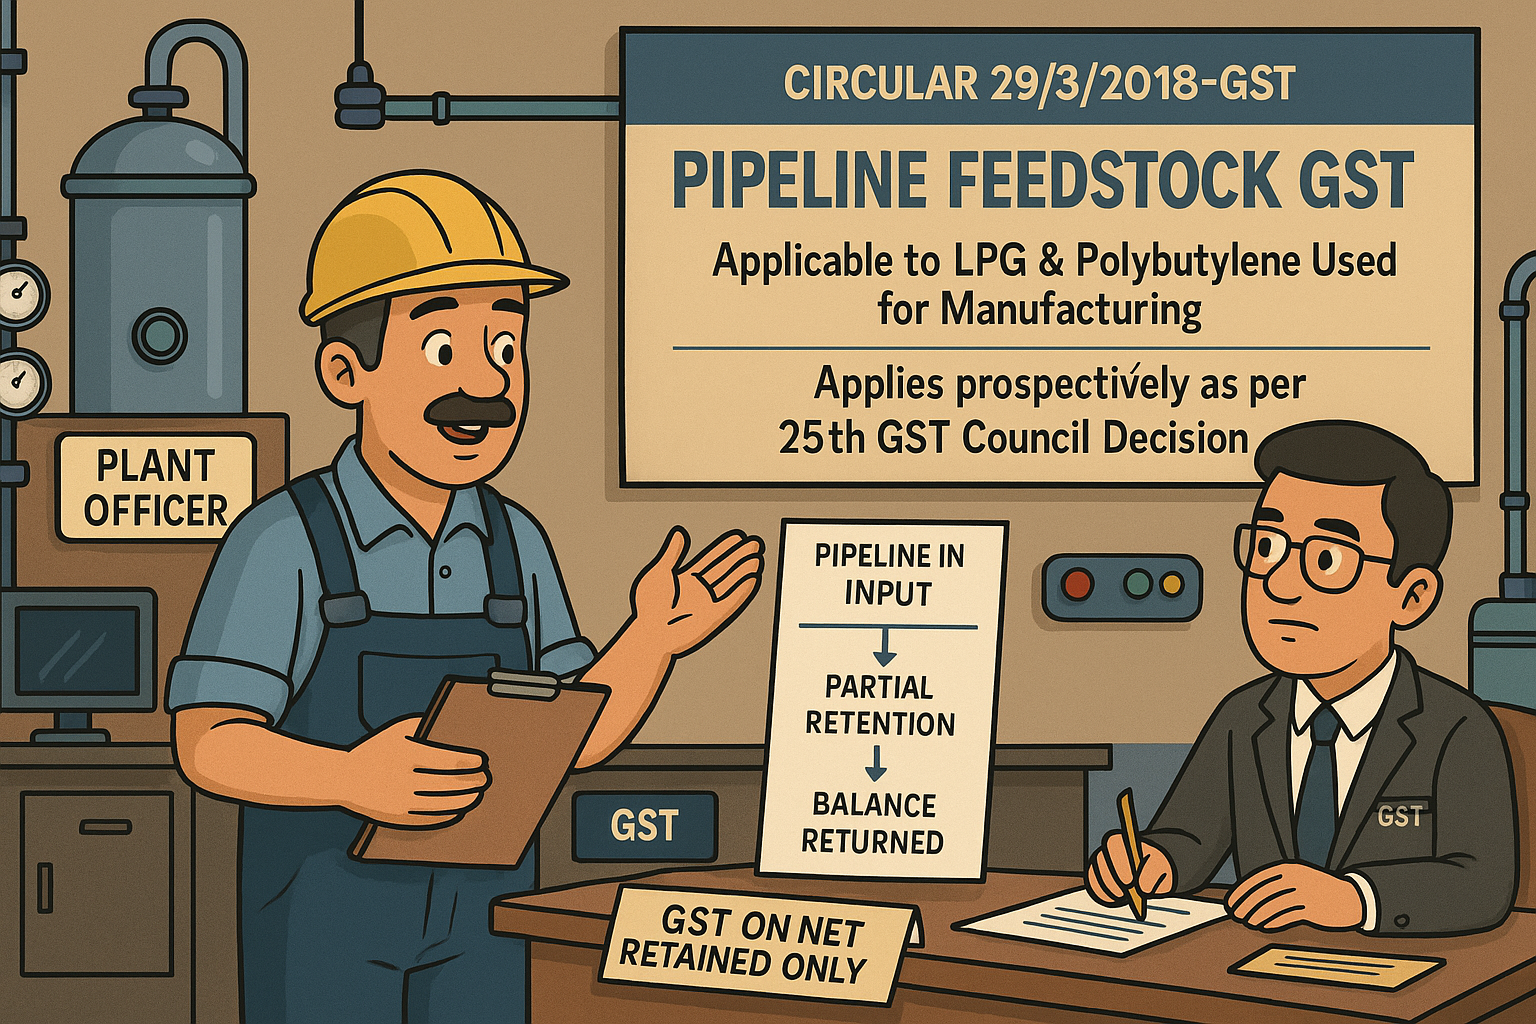
Circular No.: 29/3/2018-GST
Date of Circular: 25th January 2018
Relevant Sections and Rules:
- Central GST Act, 2017: General provisions on supply and taxability
- GST Council Reference: 25th GST Council Meeting held on 18.01.2018
Summary of Circular:
The circular clarifies the GST applicability on Polybutylene feedstock and Liquefied Petroleum Gas (LPG) used in the manufacture of Poly Iso Butylene, Propylene, and Di-butyl para Cresol, where:
- The raw materials are supplied continuously by oil refineries through pipelines.
- A portion is retained by the manufacturer, and the rest is returned to the refinery.
The issue was whether GST is to be levied on the entire quantity supplied or only on the net retained quantity.
Based on the 25th GST Council’s recommendation, it is clarified that:
- GST shall be payable only on the net quantity retained by the manufacturer for production.
- If the returned quantity is subsequently supplied by the refinery to another party, GST would apply on that onward supply.
This clarification applies prospectively and does not cover past cases, which are to be dealt with as per the law prevailing at the time of the transaction.
Source: Circular No.: 29/3/2018-GST