
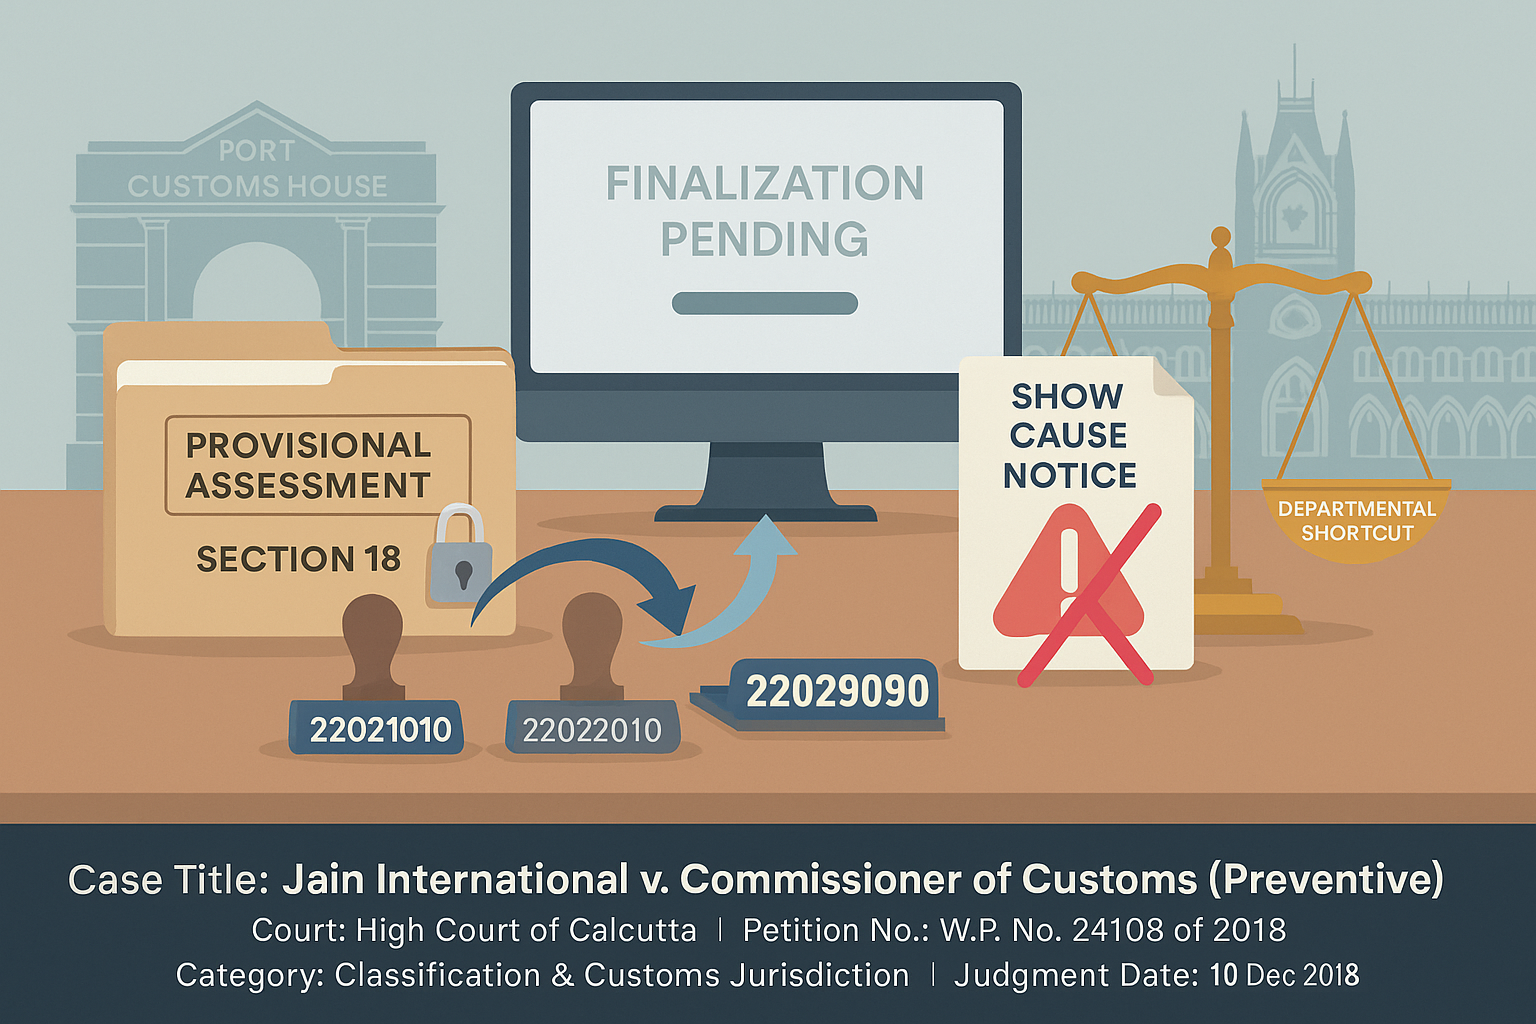
Case Title: Jain International (Importer/Exporter) v. Commissioner of Customs (Preventive)
Court Name: High Court of Calcutta
Petition Number: W.P. No. 24108 of 2018
Category of Dispute: Classification under Customs Tariff Act
Date of Judgement: December 10, 2018
Relevant Sections: Section 18, Section 28, Section 28AA of the Customs Act, 1962
Issue Type: Classification & Jurisdiction
Facts of the Case
[Para 1–3]
- The petitioner, Jain International, imported “Power Energy Drinks” initially classified under Tariff Item 22021010.
- The customs department directed reclassification under 22029090 through communication dated December 16, 2015. The petitioner accepted this reclassification and paid the differential duty.
- Subsequent imports were classified as 22029090. However, the department later issued a show-cause notice (SCN) proposing to reclassify the goods back to 22021090 and recover duties, interest, and potential penalties.
[Para 3]
- The adjudicating authority issued an order-in-original confirming the classification as 22021090 and demanded differential customs duty of ₹19,85,042 under Section 18(2), with interest under Sections 28AA and 18(3).
- The authority, however, did not impose any penalty under the now-rescinded Provisional Duty Assessment Regulations, 2011.
Question(s) in Consideration
[Para 1, 4, 5, 6]
- Whether the department could invoke Section 28 of the Customs Act when the assessment was provisional and not finally concluded.
- Whether the department could issue a reclassification order contradicting its own earlier directive dated December 16, 2015.
- Whether the writ petition was maintainable despite the existence of an alternative appellate remedy, considering alleged breach of jurisdiction and violation of natural justice.
Observations of the Court
[Para 6–7]
- The High Court noted that although there exists a statutory appeal remedy, the writ is maintainable in cases of lack of jurisdiction or violation of natural justice.
- The Court held that invoking Section 28 was inappropriate since the final assessment under Section 18 had not occurred.
- The Court accepted the petitioner’s reliance on precedents like Pramod Kumar Nathani v. UOI and Jaju Petro Chemical (P.) Ltd. v. Commissioner of Customs (Port), which held similar departmental actions to be ultra vires.
Judgement of the Court
[Para 7–9]
- The High Court held that the impugned order-in-original was without jurisdiction, as it invoked Section 28 prematurely.
- Consequently, both the show-cause notice and the order-in-original were quashed.
- Writ Petition No. 24108(W) of 2018 was accordingly disposed of with no order as to costs.
Between Fine Lines (Outcome in 5 lines)
The High Court of Calcutta quashed the customs demand raised through a reclassification of imported energy drinks. The department’s earlier reclassification directive was binding and could not be arbitrarily reversed. Section 28 could not be invoked without completing provisional assessment under Section 18. The Court held the adjudication to be without jurisdiction. Writ was maintainable due to breach of legal process and jurisdiction.
Summary of Referred Cases
| Name of Case | Citation | Summary | Verdict |
| Pramod Kumar Nathani v. Union of India | 2016 (340) ELT 642 (Cal.) | Section 28 cannot be invoked before finalisation under Section 18 of Customs Act. | Department barred from invoking Sec 28. |
| Jaju Petro Chemical (P.) Ltd. v. Commr. of Customs (Port) | 2017 (354) ELT 614 (Cal.) | Reclassification after provisional assessment without final order is without jurisdiction. | SCN and reclassification invalid. |
Takeaway
“Provisional Assessment Can’t Justify a Final Blow — Classification Change Without Closure Invalid”



