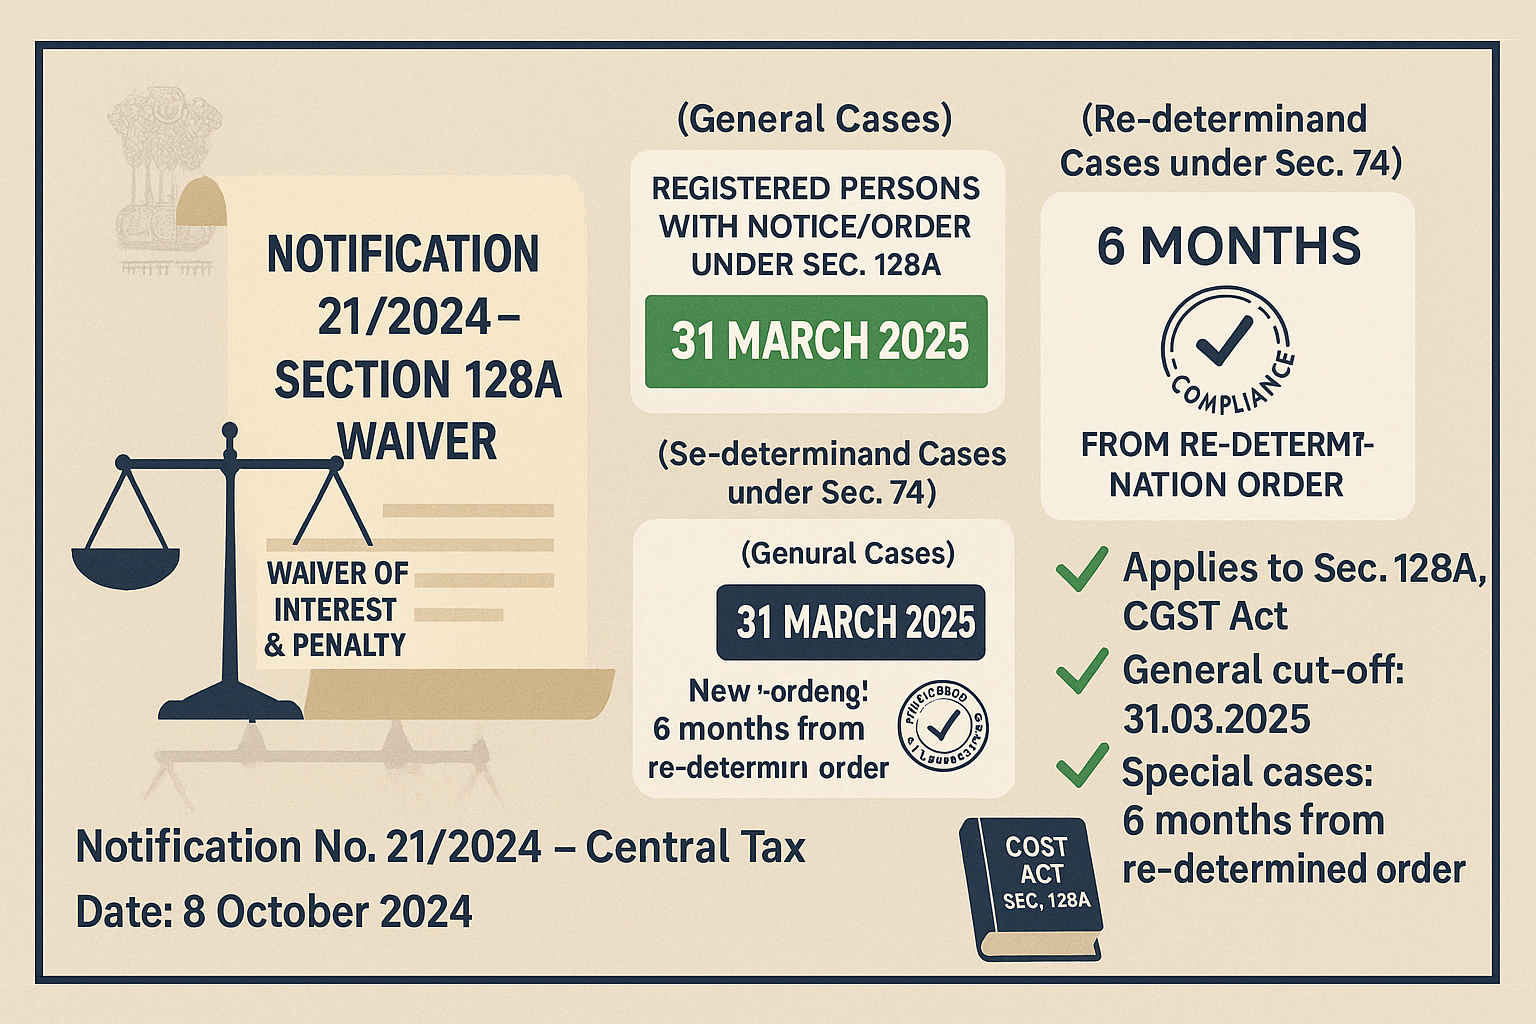
Notification No.: 21/2024 – Central Tax
Date of Notification: 8th October 2024
Relevant Sections and Rules:
- Central GST Act, 2017:
- Section 128A(1) – Power of Government to notify waiver of interest/penalty upon payment of tax within a specified time
- Section 73 & 74 – Determination of tax not paid/short paid (non-fraud & fraud cases)
- Section 75(2) – Redetermination of tax after appellate authority/tribunal/court directions
Summary of Notification:
- This notification, issued under Section 128A(1) of the CGST Act, 2017, specifies timelines for waiver of interest and penalty for certain registered persons, subject to payment of outstanding tax dues.
- The timelines are as follows:
- Sl. No. 1 – General Cases:
- For registered persons issued notices/statements/orders under clauses (a), (b), or (c) of Section 128A, payment of tax dues can be made up to 31st March 2025 to avail waiver of interest and penalty.
- Sl. No. 2 – Cases Converted from Section 74 to Section 73:
- For taxpayers initially issued notices under Section 74(1) (fraud cases), but later redetermined under Section 73 pursuant to appellate/tribunal/court directions (under Section 75(2)), payment must be made within six months from the date of such redetermination order by the proper officer.
- Sl. No. 1 – General Cases:
- The notification provides a one-time relief mechanism for taxpayers to settle tax dues with waiver of interest and penalties under Section 128A.
- It comes into effect from 1st November 2024.